

Nyheter
David Hargreaves on precious metals, Week 1 2012

David Hargreaves
We warned in the 10/12/2011 issue, but three weeks ago, that the precious metals might retreat. They have. We blamed it on the fear factor receding and it has, so let’s not be surprised if we see more on the downside. The world lost an unpredictable dictator in North Korea’s Kim Jong Il last week and the young replacement in the expensive overcoat will take time to learn the ropes. Iran is muttering about blockading the Straits of Hormuz and thus 20% of the world’s traded oil. This need not worry China, 50% dependant, or Japan 75% reliant on that seaway for their oil imports, because it is where the US 5th Fleet sits. That toy factory has enough fire power to turn Tehran into a moon of Saturn, so no fears there, eh? Anglo American might win its spat with Chile’s Codelco over 49% of a juicy copper mine. Britain has warned Argentina that if it gets ambitious about the Falklands again, the nuclear sub patrol will be put on high alert. This is big boy time. Venezuela has most of its gold back home and worth a lot less than when it called for it. Only one dictator to go (hi Bob!) and his threat to embargo platinum exports can only cheer the South Africans. The fear factor has switched from fisticuffs to financial. The further we lever ourselves into recession, the cheaper goods will become and that includes the precious.
Gold
The price run up in H2 owed much to the Euro crisis whilst the spike which saw it momentarily top $1900/oz mirrored fears of a sovereign debt failure. That gold has now subsided to beneath $1550 on the downside does not indicate that problem has been solved. It has been digested. The world would survive a Euro break up and $1500 would still be its highest ever pre Q2 2011 level. We may be still a long drop from a floor in the next few months of which the US dollar, which exerts an opposite pull, continues to remind us.
Investment demand remains the driver. The other two, jewellery and industrial, have been relatively constant since Q2 2010 whilst much has been made of changes in Central Bank holdings. They are relatively small.
The close of 2010 saw a gold price of $1408/oz, registering the 10th successive annual rise. This continued to the short lived peak of $1900 in mid 2011 until the sobering pull back to $1500 on Dec. 30th. The major structural changes have been in private investment demand, particularly in China, India and other developing countries. Central Bank buying has been noted by developing countries but not the expected surge by China. The significance of such holdings is measured not only in their total tonnage, but as a percentage of total foreign assets. By mid 2011 they showed:
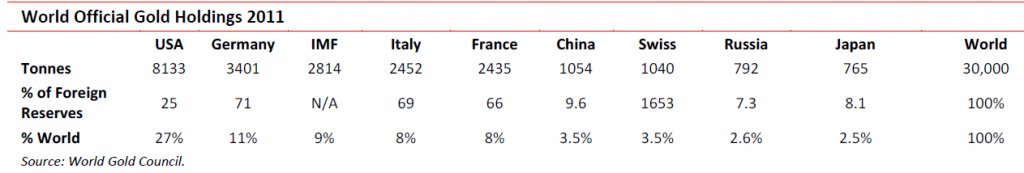
Of perhaps greater significance are total above ground stocks of gold, broadly estimated at 163,000 tonnes. Of these, c.84,000 tonnes is held as jewellery. In December a report by MacQuarie Bank suggested India alone accounted for 17,000 tonnes of this. The Chinese and Indians are displaying similar personal buying tendencies.
Supply
The pattern of mined supply remained similar to the previous five years, with the continuing decline of South Africa but increases from West Africa and Eurasia. The major producing countries remained China (13%), USA (11%), Australia (10%), RSA (8%), Russia (7%) and Peru (6%).
Outlook 2012
Gold. Any return to a major upside for gold will be driven by fear factors, not economic ones. The Middle East basin remains highly unstable and a knee-jerk oil price rise would pull gold along. Iran is clearly itching to put on a show, but unless fear becomes reality we do not see gold challenging its highs again, indeed the reverse. For supply it means South Africa may put on hold its plans to revamp the deep basin deposits and for marginal ventures worldwide to struggle with funding. The majors sit on healthy balance sheets, but cannot expect a market rerating. Of the larger ones:
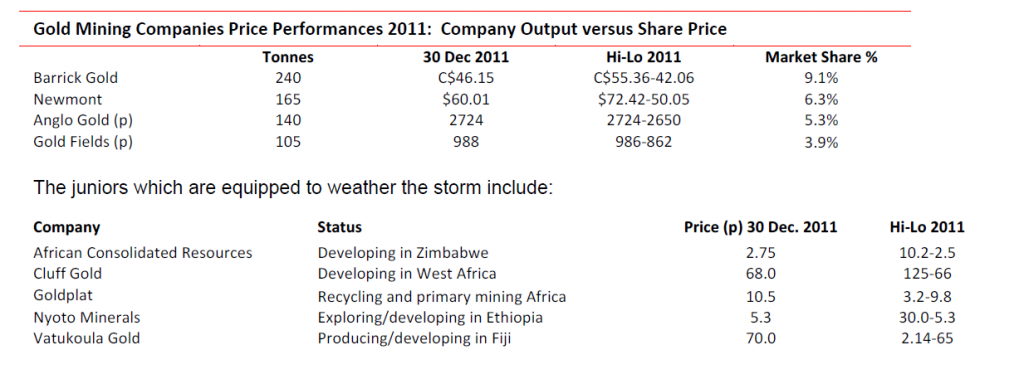
The final day flip in gold (up $45 to $1578/oz) should not be confused with a rally. Only an ungovernable geological or political event is liable to drive it skywards. The world economy will stabilise and we should remember that as recently as 2008, gold was at $700/oz.
Platinum
This was the year the industry got it wrong. If ever a commodity was ripe for cartel action, in theory it is platinum. A single country, South Africa, supplies 75% of all newly mined metal and with Russia does 85% of all the platinum and palladium combined. Only four companies dominate and just two end uses, autocatalysts and jewellery, account for 70% of demand. Yet there is no cartel. London – based free market, daily fixing pricing dominates. That price has fallen progressively in 2011 from an opening $1745/oz to a closing $1407/oz, a fall of 19%. A weak economy, increased output and more intensive recycling, particularly of spent catalysts, were the culprits. Another feature – of longer term significance – was a round of overgenerous wage settlements, which have saddled the South African industry with untenable costs. This is an industry at a crossroads. A small surplus of c. 200,000 oz is calculated for 2011 from a mined supply of 6,400,000 oz and a total demand of 8,100,000 oz. The balance of supply is made up of recycling. Industrial demand is c. 2,000,000 oz and investment c. 500,000 oz.
The shares had a miserable run:
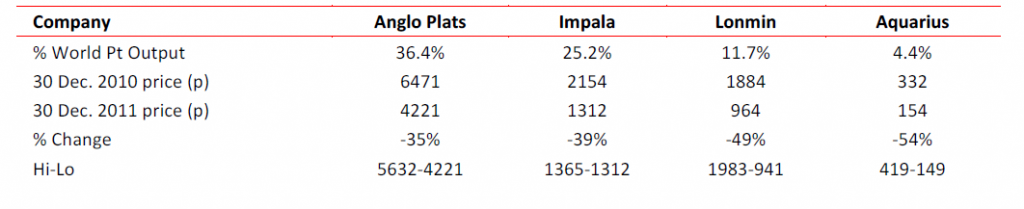
There is nothing to suggest a short term rally, rather further weakness.
Silver
Silver owes its classification ‘precious’ more to its chemical characteristics than its scarcity. It is mined at an annual rate of c. 23,500 tonnes, or ten times that of gold. Yet its price ratio is far higher. Were it in relation to its production, the price of silver would be c. $160/oz, not $30. Its 2010-2011 open and closing levels of $30/oz and $28/oz disguise a run up in Q3 to over $50, prompting some analysts to call for $200.
This is not going to happen. Why?
- The total volume of silver on surface is vastly greater than its production ratio to gold. It has been mined in large quantities for much longer and was for centuries the world’s currency backing.
- Almost 50% is used industrially which, combined with other fabrication and jewellery accounts for c. 85% of all arisings.
- Ten countries combine to produce 80% of newly mined output and vast quantities are available for dishoarding at the right price.
- Most silver is recovered as a by-product of base metal mining, the few pure silver producers including Fresnillo (5.2% market share), Pan American (3.3%), Hochschild (2.4%) and Coeur D’ Alene (2.3%). We believe silver will continue to track gold at a price ratio of 50:1 – 60:1 with a narrowing in a bull market.
[hr]
About David Hargreaves
David Hargreaves is a mining engineer with over forty years of senior experience in the industry. After qualifying in coal mining he worked in the iron ore mines of Quebec and Northwest Ontario before diversifying into other bulk minerals including bauxite. He was Head of Research for stockbrokers James Capel in London from 1974 to 1977 and voted Mining Analyst of the year on three successive occasions.
Since forming his own metals broking and research company in 1977, he has successfully promoted and been a director of several public companies. He currently writes “The Week in Mining”, an incisive review of world mining events, for stockbrokers WH Ireland. David’s research pays particular attention to steel via the iron ore and coal supply industries. He is a Chartered Mining Engineer, Fellow of the Geological Society and the Institute of Mining, Minerals and Materials, and a Member of the Royal Institution. His textbook, “The World Index of Resources and Population” accurately predicted the exponential rise in demand for steel industry products.

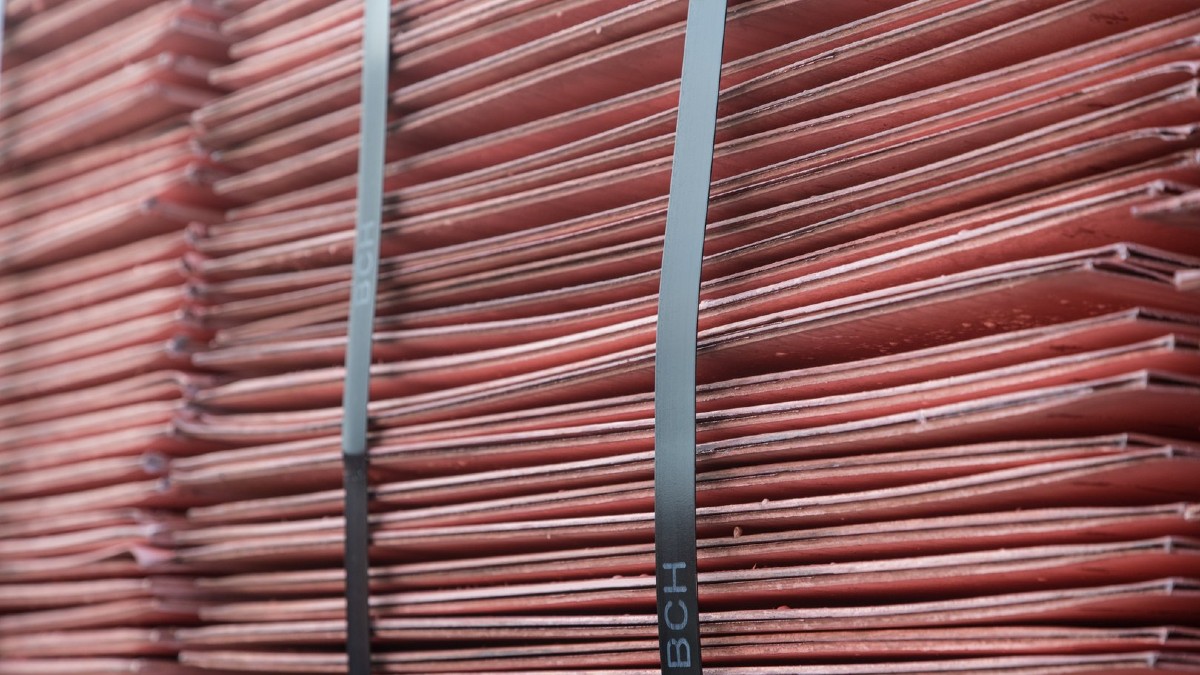
Kopparpriset var uppe över 14 500 dollar per ton, det borde få allas uppmärksamhet skriver Jeffrey Currie. Det är det senaste tecknet på att den fysiska ekonomin omvärderar knappheten i den verkliga världen.
En del av gårdagens kursrörelse speglar spekulation inför tullhöjningar och att metallen flyttas in i amerikanska lager. Men det ger inte hela bilden är han tydlig med.
Metall som fastnat i en del av världen är otillgänglig för alla utanför den delen. Knapphet handlar inte bara om hur många ton som finns, utan om att ha tonen på rätt plats vid rätt tidpunkt.
Man kan inte bygga datacenter, bygga ut elnät, elektrifiera industrin eller bygga dubbla försörjningskedjor utan koppar. Ändå kan utbudet inte reagera tillräckligt snabbt på grund av samma begränsningar som Jeff Currie har lyft fram tidigare.
Detta är den senaste vändningen i råvarucykeln. Förra månaden var det spannmål. Förra veckan var det diesel. Idag är det koppar.
Väder, krig och politiska beslut har tillsammans skapat ett bristproblem som inte visar några tecken på att lösas enligt Currie. De som tror att priserna kommer att gå ner argumenterar för att metallen finns. Men om den är inlåst i ett lager är den bara en hög med metall.

Den nederländska centralbanken DNB har flyttat 86 ton av landets guldreserver från USA och Kanada till London. Beslutet motiveras med ett allt mer oroligt geopolitiskt läge och behovet av att kunna använda reserverna snabbare i en krissituation.
London ger snabbare tillgång
DNB uppger att guld som förvaras i London är enklare att omsätta än reserverna i New York och Ottawa. London är världens djupaste och mest likvida guldmarknad, vilket gör det lättare för centralbanker att sälja eller låna ut guld vid behov.
Nederländernas totala guldreserv uppgick vid slutet av 2025 till 612,4 ton, värd omkring 72,2 miljarder euro. Efter flytten finns 32,1 procent av reserverna i London, jämfört med 18,1 procent tidigare. Andelen i både USA och Kanada har samtidigt minskat till 18,5 procent vardera.
Geopolitiken bakom beslutet
DNB hänvisar uttryckligen till den ökade geopolitiska oron. Enligt centralbankschefen Olaf Sleijpen handlar flytten om att stärka bankens motståndskraft och beredskap, även om förhoppningen är att reserverna aldrig ska behöva användas i en kris.
Själva överföringen genomfördes mellan mars och augusti. En del av guldet flyttades fysiskt, medan andra delar hanterades genom köp och försäljningar. Mer än 27 ton fysiskt guld transporterades från USA och Kanada till Nederländerna och därefter vidare till London.
Kan fler centralbanker följa efter?
Bedömare konstaterar att centralbanker har flyttat runt sina guldreserver under ungefär ett decennium. Den politiska utvecklingen i USA kan samtidigt göra att vissa länder föredrar andra förvaringsplatser.
John Plassard vid Cite Gestion Private Bank beskriver den nederländska åtgärden som ett sätt att säkerställa mer omedelbar tillgång till guldet vid en kris. Han varnar samtidigt för att ett större skifte från amerikanska förvaringsplatser skulle kunna påverka förtroendet för USA.
Tyskland har exempelvis diskuterat säkerheten kring sina guldreserver i New York, men Bundesbank har hittills valt att behålla sina reserver där.

Mindre blåst och regn innebär också mindre vindkraft och lägre vattennivåer. Detta i kombination med mindre kärnkraft har minskat tillgången på el och höjt elpriserna. Även prisskillnaderna har ökat mellan norra och södra Sverige med anledning av flaskhalsar i nätet. Det gör att det är svårare att föra billig el från områden med överskott till områden med större behov. Mer ostadigt höstväder med mer nederbörd och blåst kan dämpa elpriserna.
Månadsmedelpriset för augusti på den nordiska elbörsen Nord Pool utan påslag och exklusive moms blev 66,67 öre/kWh i elområde 3, södra Mellansverige, och 38,77 öre/kWh i elområde 1, norra Sverige.
– Augusti blev dyrare än de två föregående åren. Kraftproduktionen har varit lägre och när det regnar mindre i områden med vattenkraft behöver man hushålla med vattnet så att det ska räcka till vintern. Men får vi mer nederbörd och framförallt att det blåser mer, så kommer det att direkt påverka elpriset nedåt men det gör också att priserna blir mer volatila, det vill säga mer svängiga, säger Jonas Stenbeck, privatkundschef på Vattenfall Försäljning.
Den nordiska kärnkraften ligger just nu 70 procent av installerad kapacitet men kommer att sjunka till drygt 50 procent i september bland annat med anledning av planerat underhållsarbete. Södra Norge har väldigt låga vattennivåer vilket även slår över på priserna i södra Sverige. De svenska vattennivåerna ligger på normalen vilket dämpar elpriset i norra Sverige.
Flaskhalsarna i elnätet gör att elöverföringen från norr till söder är begränsad. Idag är en tredjedel av elanläggningarna äldre än 40 år och närmar sig slutet av sin tekniska livslängd. Svenska Kraftnät planerar att investera 70 mdr kronor åren 2027–2029, samtidigt som Vattenfall Eldistribution fram till 2030 planerar att investera 47 mdr kronor i region- och lokalnätet.
Oljepriset har ökat men även gaspriset har stigit betydligt på kontinenten med anledning av låga lager, konkurrens om flytande naturgas och oro för leveranser genom Hormuzsundet. Eftersom elmarknaden är sammanlänkad kan även de nordiska elpriserna påverkas, framförallt södra Sverige.




Kopparpriset stiger när den fysiska världen gör sig påmind

Tightness today versus risk of surplus tomorrow

Nederländerna flyttar guld från USA och Kanada till London
Ostadigt höstväder kan dämpa de höga elpriserna

Priset på råolja är fel signal att titta på, det är bensin och diesel som visar allvaret
No reopening of SoH anytime soon. Winter could be expensive for oil product consumers

Saskatchewan bygger en av världens största urangruvor, kan stå för en femtedel av den globala produktionen

Pirater från Somalia kapar tankfartyg som fraktat oljeprodukter från Iran

Guldet rör sig i ton, betalningarna rör sig i millisekunder: Vad finansmarknadernas infrastruktur lär oss om digital penningrörelse

Jeffrey Currie – Råvarorna skickar en varningssignal, guld gynnas från två håll
-
Analys4 veckor sedan
No reopening of SoH anytime soon. Winter could be expensive for oil product consumers
-
 Nyheter2 veckor sedan
Saskatchewan bygger en av världens största urangruvor, kan stå för en femtedel av den globala produktionen
-
 Nyheter3 veckor sedan
Pirater från Somalia kapar tankfartyg som fraktat oljeprodukter från Iran
-
 Uncategorized4 veckor sedan
Guldet rör sig i ton, betalningarna rör sig i millisekunder: Vad finansmarknadernas infrastruktur lär oss om digital penningrörelse
-
 Nyheter2 veckor sedan
Jeffrey Currie – Råvarorna skickar en varningssignal, guld gynnas från två håll
-
Analys3 veckor sedan
Stay long or buy-on-dips in the run-up to the US midterm elections on 3 Nov
-

 Nyheter2 veckor sedan
Irland har inlett en debatt om att ta bort förbudet av kärnkraft
-
Analys2 veckor sedan
Oil close to technical levels while EU nat gas is gripped by winter-panic