

Analys
SEB – Råvarukommentarer, 28 september 2012

Sammanfattning av rekommendationer
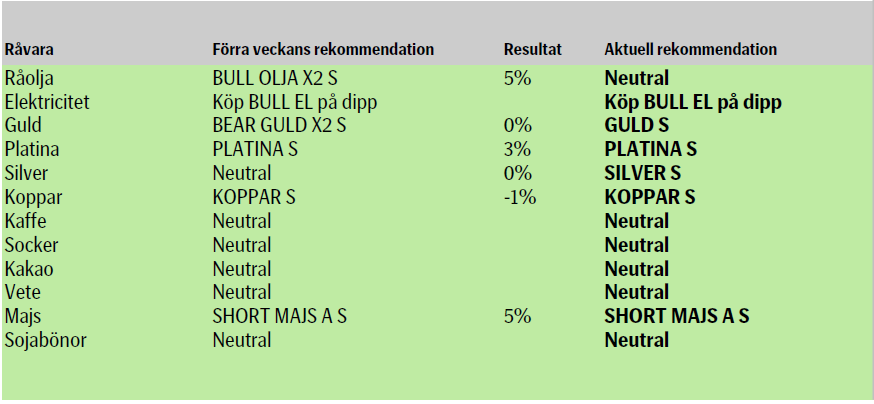
Summan av resultatet blev vinst på 12%, efter förra veckans förlust på -1%.
Viktigast den här veckan är att vi tror att det kan komma en rekyl i guldpriset. Det ser ut så rent tekniskt. Priset har rusat iväg väldigt fort och är uppe på nivåer där det sannolikt finns många som vill ta hem vinster. Vi ser detta som en teknisk och kortsiktig rekyl. Vi anser att det finns gott om värde i Platina och väljer att ligga kvar köpta den, samtidigt som vi mycket kortsiktigt rekommenderar en kort position i guld. Råolja går vi över till neutral rekommendation på, liksom på silver, som ligger någonstans mellan guld och platina i vår vy nu.
Jordbruksprodukterna är vi neutrala till negativa till. Det kommer viktig lagerstatistik från USDA senare idag, som är värt att hålla koll på. Kaffe, socker och kakao ligger alla lågt i pris, och tycks bilda bottenformationer inför en eventuell trendvändning. För närvarande är vi neutrala.
Råolja – Brent
Det blev ingen omedelbar prisuppgång i Brentolja efter USAs tredje omgång av kvantitativa lättnader. Brentoljan faktiskt har fallit snarare än motsatsen. Den främsta orsaken till detta är på den ökande oron över situationen i Europa vilket resulterar i en starkare USD och en svagare euro. Medan Mellanösterns försörjningsavbrott och olösta situationen håller oljepriset sig högt men den grundläggande makrobilden ser svag ut och drar i baisseriktning. Vi har en neutral syn på Brentolja för närvarande till ett pris av $ 110 / b. Saudiarabien skulle gärna se att oljepriset blev lägre i syfte att lindra den globala makrosituationen men har inte lyckats hittills. Saudiarabien fortsätter dock att försöka hålla ner oljepriset genom att hålla sin oljeproduktion på en förhöjd nivå.
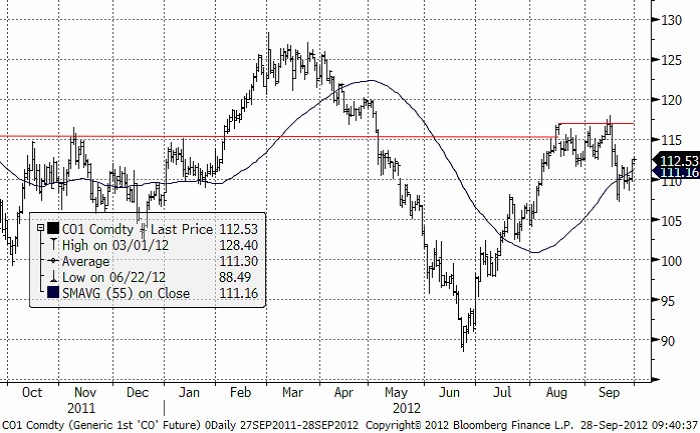
I nuläget förhåller vi oss neutral men ser nivåer kring 105 USD som en mycket attraktiv nivå för en lång position.
Elektricitet
Elmarknaden föll genom stödet, men vände sedan upp igen och ligger nu precis under motståndet. Den kortsiktiga trenden är nedåtriktad och vi ser uppgången som en rekyl. Ser vi till marknaden för kol, vars pris helt och hållet styr priset på el i Norden, är den marknaden i en tydlig nedåttrend sedan en topp i början på augusti. Däremot är priset på kol nere på en nivå, där priset funnit stöd flera gånger förut, i maj, juni och juli. Marknaden testar alltså historiska bottennivåer i såväl kol som el. Vi har ännu inte en köprekommendation, utan behåller neutral rekommendation.
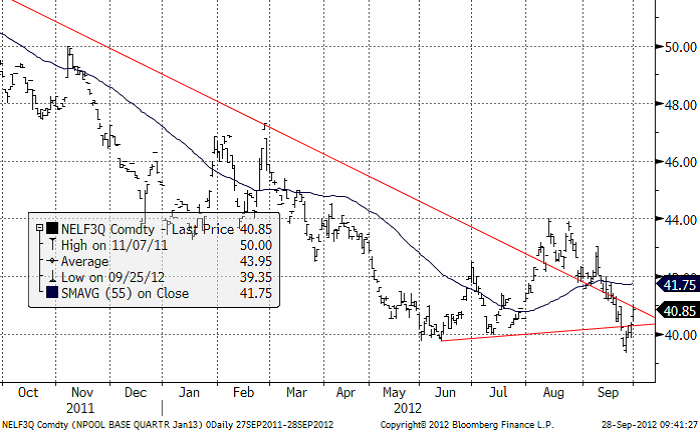
Vidare kan nämnas att väderleksrapporten visar riklig nederbörd, reservoarerna är på 5-årshögsta och hydrobalansen är 12 till 15 TWh över det normala. Nordiska kärnkraftverk väntas vara helt online från den 26 oktober och global ekonomisk aktivitet minskar såväl i Asien som i Europa och är svag och oförutsägbar i USA. Detta gör att vi är oroliga för ytterligare nedsida i elpriset. Icke desto mindre, handlas kontraktet för det första kvartalets genomsnittliga spotpris för 2013, som är underliggande för våra ETN:er, nära 40 euro per MWh, som vi anser är ett bra pris inför vintern. Första kvartalet är trots allt det kallaste kvartalet. Det finns möjligheter till kortsiktiga uppgångar till 44 euro.
Guld och Silver
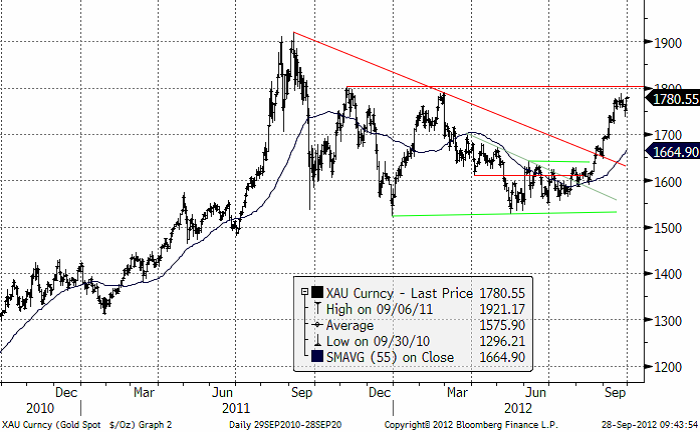
Efter den initiala reaktionen efter FED har guld och silver inte orkat klättra vidare. Många aktörer som köpt på förväntningar om ytterligare stimulanser har legat beredda att ta hem vinster. Det gamla ordspråket ”buy the rumour and sell the fact” verkar gälla även den här veckan. Undertonen är ändå stark och rekylerna endast marginella. Vi bedömer att priserna har fortsatt mer att ge med nivån $1800 inom räckhåll för guld (spot i London handlas kring $1862 i skrivandes stund). En tänkbar strategi (för den som inte redan köpt) är att bevaka den tidigare högsta nivån $1780 och agera på ett genombrott. Scenariot är likartat för silver med rekommenderad bevakning av förra veckans toppnivå på $35/oz ($34,50 i skrivandes stund). Vår tekniska analys indikerar en större rekyl på nedsidan om nivån 1748 bryts på stängningsbasis. Se våra tekniska kommentarer nedan:
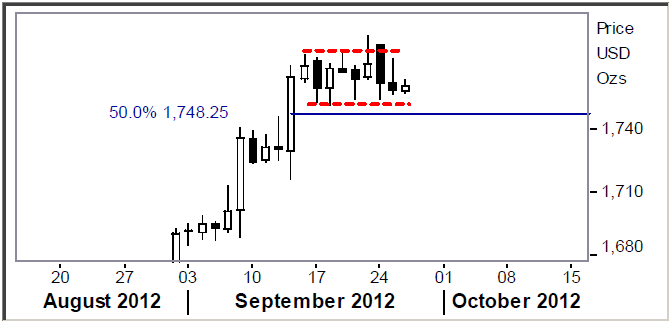
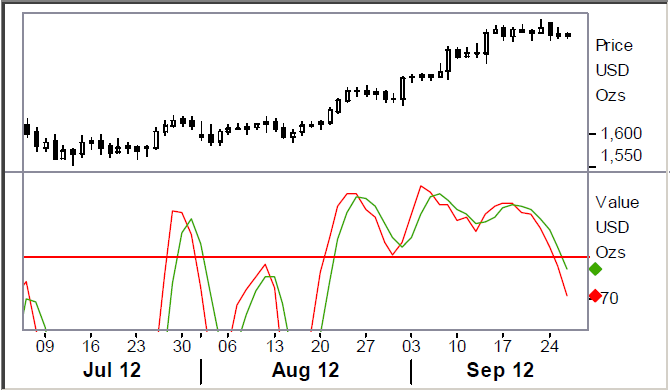
Bankens tekniska analytiker menar så här: “Last Friday printed an up-thrust top, a false break higher. The move was on Monday followed by a gap higher and an immediate reversal creating a bearish engulfing/key day reversal candle. A break below 1752 will confirm at least a short term top formation (and more so breaking below the mid body pt, 1748, of the latest rising benchmark candle).” Dessutom ser man en divergens mellan den tekniska indikatorn stochastics, som ofta används som en överköpt/översåldindikator:
“There is a confirmed bear divergence between price and stochastic i.e. a higher top in price and a lower one in the indicator”. Vi ser en bild på detta nedan:
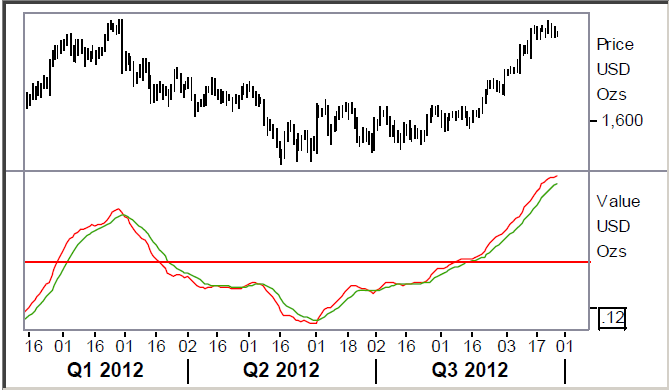
En annan teknisk indikator, MACD, visar på en överköpt marknad, som vi ser i nedanstående diagram, samtidigt som priset på guld ligger väldigt nära toppnivåerna från det första kvartalet.
Nedan ser vi lite längre historik för guld i dollar per troy ounce.
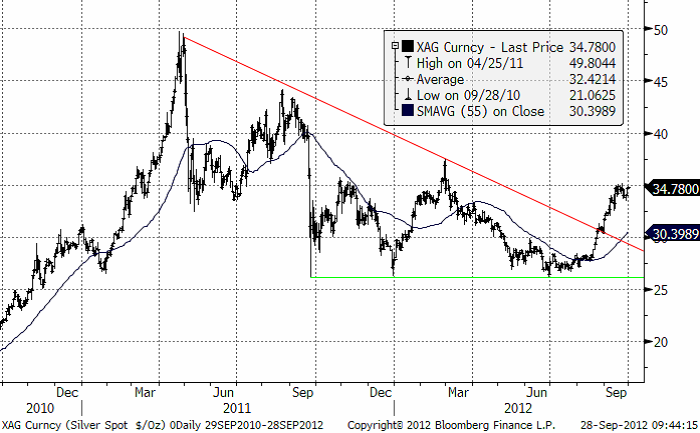
Nedan ser vi kursdiagrammet för silver i dollar per troy ounce, som ligger precis under 35 dollar. Vi har sett att det verkar finnas säljare på 35 dollar.
Platina
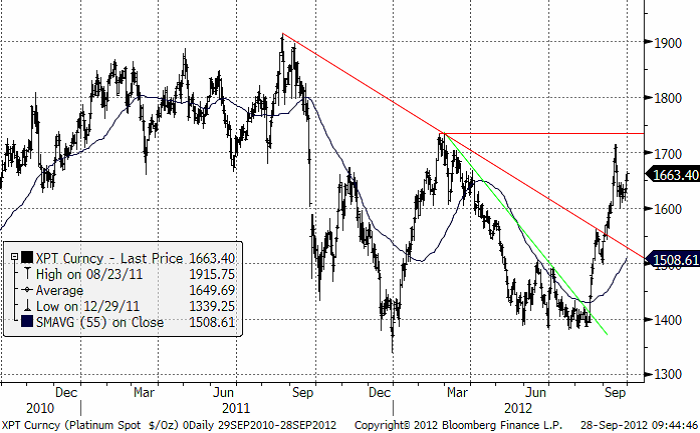
Trots strejkslutet vid Lonmins gruva i Sydafrika vände marknaden uppåt i veckan. Spotnoteringen i London är upp ca 1,5 % sen förra fredagen. Lonmin har finansiella problem och strejkvågen riskerar att sprida sig till andra platinagruvor. Flera guldgruvor har produktionsstopp p.g.a. nya strejker. Risken är stor för minskat utbud från regionen. Den industriella efterfrågan är relativt svag i Europa men fordonsindustrin i Kina förväntas skapa god tillväxt. Vi kvarstår med köprekommendationen.
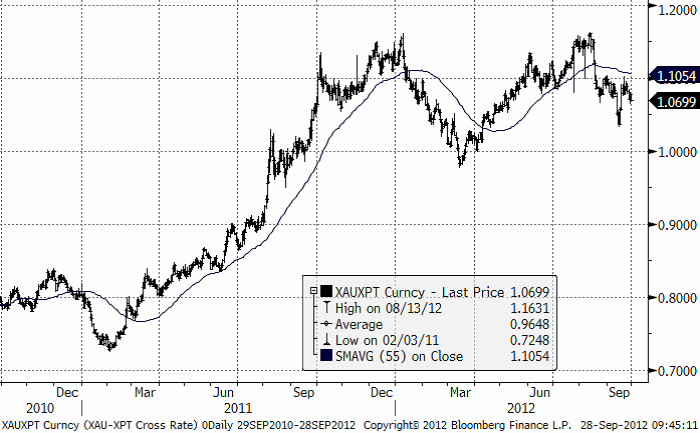
Nedan ser vi priset på guld dividerat med priset på platina. Vi ser att guld har utvecklats sämre än platina sedan mitten avaugusti. Tekniskt ser den här trenden stark ut och har potential att gå från 1.05 till 1, dvs en outperformance på ytterligare 7%till platinas fördel. Som vi ser av den längre historiken brukar platina vara betydligt dyrare än guld. Dagens rabatt på platina iförhållande till guld är väldigt ovanlig.
Koppar
Prisutvecklingen har varit lite ”tråkig” för basmetallerna under veckan. Fokus har återigen skiftat tillbaka till Europa. Preliminära PMI- siffror från Eurozonen kom in lägre än väntat, 45,9 mot 46,3 förra månaden. IFO-Index (företagsklimatet) från Tyskland ingav inte heller något ökat förtroende. Ingen viktig statistik från Kina, men marknaden känner sig tveksam till aktiviteten där just nu. Det är egentligen bara US som faktiskt visar positiva tecken, på den för den amerikanska ekonomin så viktiga bostadsmarknaden, som nu verkar ha bottnat ur.
Basmetallerna handlades med blandad tendens under veckan. Koppar föll, aluminium och zink höll sig oförändrade, medan nickel visar styrka just nu och är upp 2 %.
När det gäller koppar, räknade vi med en stabilisering efter rekylen i förra veckan och därefter nya försök på uppsidan, men marknaden har inte haft kraft nog. Priset har istället fallit ca 1 %. Vi kvarstår med bedömningen att det mesta talar för en fortsatt stark underton. Den kan dock dröja lite till innan en ny rusning. Nya signaler från Kina är nog vad som behövs. Kina konsumerar 40 % av världens koppar.
Vi bedömer att finansiella aktörer som tidigare spekulerat i nedgång, nu har återköpt positioner. Tekniska fonder har börjat gå långa. Industrin är än så länge avvaktande och brottas med en prisuppgång som inte riktigt speglar den fundamentala situationen, och i många fall överstiger lagda budgetnivåer. Frågan är när (och om) industrin tvingas ”bita i det sura äpplet” och täcka in framtida behov. Centralbankerna visar att de menar allvar och stimulanserna fortsätter. Aktörerna väntar på mer från Kina. Mycket talar för en fortsatt stark trend i nästa vecka med test av nivåer upp mot $8500.
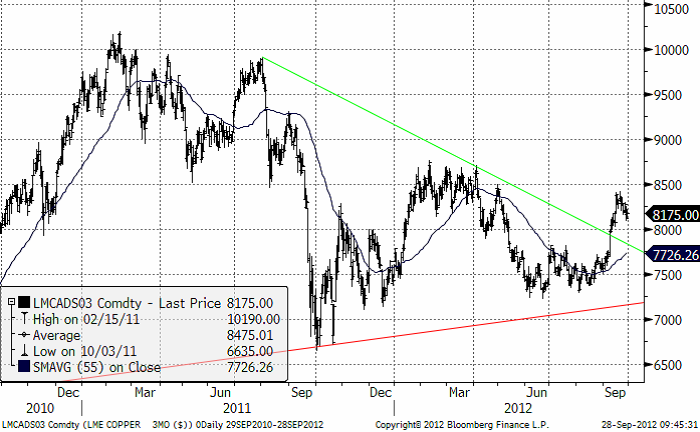
Vi väljer att på kort sikt rekommendera en lång position i koppar.
Kaffe
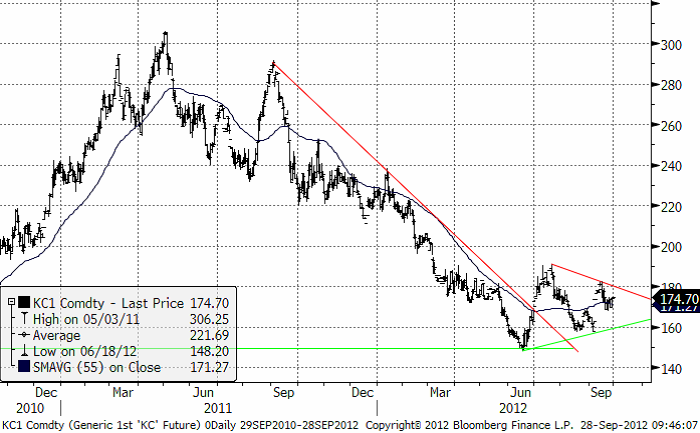
Kaffepriset har rekylerat ner från toppen tidigare i månaden, men funnit stöd vid 55 dagars glidande medelvärde. Tekniskt noterar vi att det efter bottennoteringen i juni på 148 cent, har en tid av konsolidering i marknaden bildat en triangelformation. Triangelformationer kan ofta signalera en trendvändning uppåt, som bekräftas av ett brott uppåt i så fall. Triangelformationen är ett observandum. Vi behåller en neutral rekommendation i väntan på brott uppåt – eller nedåt från formationen, som du kan se inritad i diagrammet nedan.
Socker
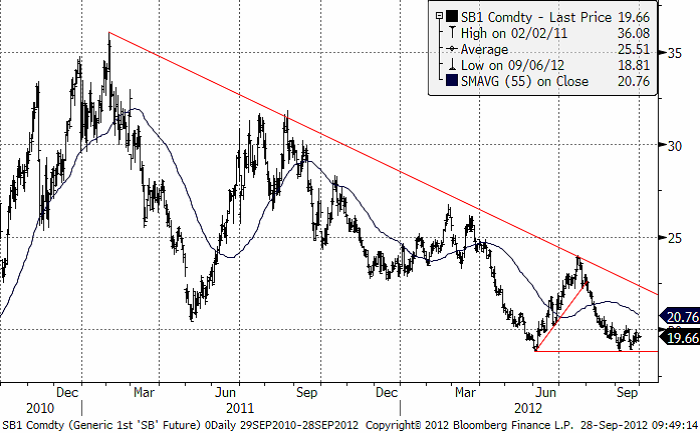
Marknaden för socker pressas av ideliga dåliga nyheter. Till exempel väntas nu det tredje året med överskott (lageruppbyggnad) pga hög produktion. Priset tycks dock inte ta mycket intryck av detta, utan håller det tekniska stödet, än så länge.
Kakao
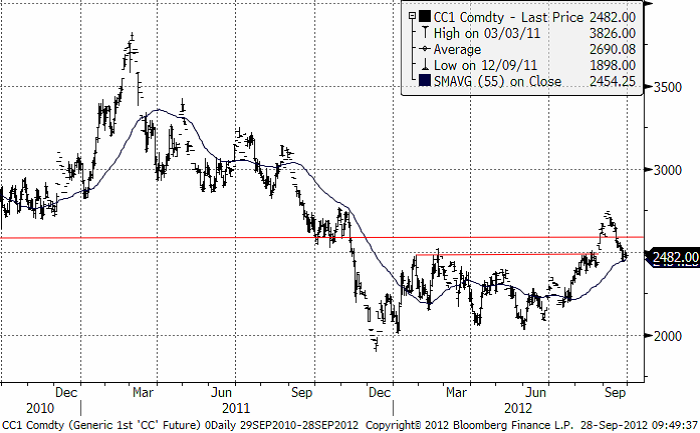
Kakaopriset har fortsatt falla ner mot stödområdet. Vi behåller förra veckans neutrala rekommendation.
Stocks report idag från det amerikanska jordbruksdepartementet
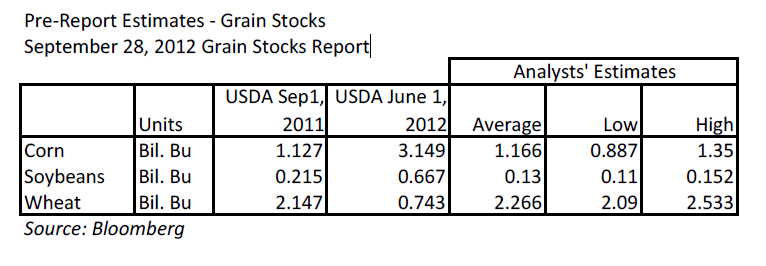
Idag, fredag publicerar USDA stocksrapporten per den 1 september. Vi har sammanställt marknadens förväntningar från analytikers bidrag till Bloomberg och du ser dem i tabellen nedan:
 För spannmål och övriga jordbruksprodukter hänvisas till gårdagens nyhetsbrev om jordruksprodukter.
[box]SEB Veckobrev Veckans råvarukommentar är producerat av SEB Merchant Banking och publiceras i samarbete och med tillstånd på Råvarumarknaden.se[/box]
Disclaimer
The information in this document has been compiled by SEB Merchant Banking, a division within Skandinaviska Enskilda Banken AB (publ) (“SEB”).
Opinions contained in this report represent the bank’s present opinion only and are subject to change without notice. All information contained in this report has been compiled in good faith from sources believed to be reliable. However, no representation or warranty, expressed or implied, is made with respect to the completeness or accuracy of its contents and the information is not to be relied upon as authoritative. Anyone considering taking actions based upon the content of this document is urged to base his or her investment decisions upon such investigations as he or she deems necessary. This document is being provided as information only, and no specific actions are being solicited as a result of it; to the extent permitted by law, no liability whatsoever is accepted for any direct or consequential loss arising from use of this document or its contents.
About SEB
SEB is a public company incorporated in Stockholm, Sweden, with limited liability. It is a participant at major Nordic and other European Regulated Markets and Multilateral Trading Facilities (as well as some non-European equivalent markets) for trading in financial instruments, such as markets operated by NASDAQ OMX, NYSE Euronext, London Stock Exchange, Deutsche Börse, Swiss Exchanges, Turquoise and Chi-X. SEB is authorized and regulated by Finansinspektionen in Sweden; it is authorized and subject to limited regulation by the Financial Services Authority for the conduct of designated investment business in the UK, and is subject to the provisions of relevant regulators in all other jurisdictions where SEB conducts operations. SEB Merchant Banking. All rights reserved.


Dated Brent and Oman crude are showing the way higher. The Brent crude M1 contract (October) gained another 0.75% yesterday. It traded in a range of $95.97-95.06/b and closed at $97.0/b. This morning it gains another 1.4% to $98.4/b. The Dubai M1 contract which is settled in November is showing the way at $105/b while Dated Brent settled ydy at $106.8/b. Brent crude M1 is now well above both the 50dma, 100dma and 200dma and is heading towards the 61.8% Fibo level of $100.55/b with $110.44/b next in line technical level thereafter.

Tight oil product markets are helping to drive crude oil prices higher as well. The strong push upwards for the Dated Brent price with ydy price reaching $106.8/b. Behind that drive upwards it very tight oil product markets with balance of month diesel refining margins in ARA now close to $90/b and gasoil cracks have been reported to top $100/b for the first time ever. That means extreme profitability for refineries. In response refineries here, there and everywhere want to get their hands on physical crude as quickly as possible. Convert it to oil products and sell the products into the ultra-tight spot oil product markets. Especially the diesel segment (Jet, diesel, gasoil). The economic incentive is huge for refineries.
This drive by refineries to process more crude in response to high refining margins, usually kicks in at much lower levels. Thereby normally transferring tightness from the oil product market over to the crude oil market. That normal mechanism hasn’t really worked properly in this crisis so far since there hasn’t been all that much spare refining capacity left as Ukraine is constantly damaging Russian refineries while the semi-closure of the SoH has sharply reduced oil product exports.
Stronger Chinese crude oil imports but higher oil product exports as well. Chines crude imports rose 6.2% MoM in August to 9.21 mb/d. That was still 2.9 mb/d below the 2025 average of 12.1 mb/d. But China’s net oil product exports rose to 0.91 mb/d in August which is the highest level since February 2023. As a result, Chinese imports of crude and oil products was still 3.5 mb/d below the 2025 average versus 3.6 mb/d in July. That is a strengthening of net imports of only 0.1 mb/d. Not much change in total. But it shows that Chinese refineries, probably with the blessing of government, are importing more crude and re-export these as oil products. That helps to transfer oil product tightness to crude oil tightness. India is doing the same. In July it exported about 1.4 mb/d of oil products and the highest since September.
The Iran-Oman deal on the SoH will give China a forceful political option. The Iran-Oman agreement over how to operate the SoH is just days away from finalization says Iran. The IMO and the US is said to have been involved in the process. Once it is agreed and published, China will have the option to sail a Chinese flagged VLCC through the SoH according to the new, official regulation of the SoH, load oil at Kharg Island and take it back to China. That is a very forceful option for China.
Oil and the SoH will for sure be a hot topic when Trump and Xi Jinping meets in the US on 25 September. And China will have some forceful bargaining chips to play versus Donald Trump regarding the SoH and oil.
ARA balance of month refining margins at close to $90/b giving refineries strong incentives to run hard converting crude to products = stronger refinery crude oil demand

Dated Brent and Oman crude (settled outside of the Persian Gulf) are showing the way upwards

Chinese crude (crude) and net crude and oil product imports (red) versus the 2025 average. Net crude and oil product imports was 3.5 mb/d below the 2025 average in August and 3.6 mb/d below in July. Almost the same. Stronger crude imports but also higher oil product exports

Chinese oil product exports rose to 0.91 mb/d in August and highest since Feb 2023. (numbers in reverse)

Oil markets remain tight as the Strait of Hormuz (SoH) continues to be constrained. Things could become much tighter if it is fully closed. However, the outlook could change rapidly if flows normalise in early 2027. A large underlying surplus, rebuilding supply and the risk of more volume from OPEC+ could turn today’s tightness into a significantly weaker oil market in 2027-28.
Eventual reopening looks set to bring surplus
The SoH is constrained, not fully closed. Enough crude is escaping, while alternative pipelines, decreased Chinese imports and SPR releases have helped keep Brent at c. USD 90/bbl. Oil products are much tighter. A full reopening of the SoH would flip the market into surplus. We assume SoH flows normalise from early 2027. The market could then face a 4-5m bbl/d surplus before restocking. We forecast Brent at USD 75/bbl in 2027 and USD 70/bbl in 2028.
We expect OPEC+ to opt for more volume once SoH exports normalise
OPEC+ will likely opt for more volume. The UAE has already chosen volume, Iraq wants to expand and Venezuela looks set to exit. There is a clear risk of controlled OPEC+ supply growth, adding to downside risks for 2027-28.
Natural gas market: Winter risk ahead, yet LNG balance to loosen from 2026
Natural gas inventories in Europe are well below normal. The market had hoped for a revival in Persian Gulf LNG exports from Qatar. However, with no signs of any imminent reopening of the SoH, it might be too late for Middle East LNG cargoes to arrive in Europe before the end of winter 2026/27. TTF natural gas winter prices have rallied in response, but that is predominantly a winter risk with prices trading sharply lower after March 2027. Growing global LNG export capacity in the years to come should push prices lower.
Brent crude converging to technical levels. Brent crude has traded in a range of $90-95/b over the past five days. It pulled back 2.4% yesterday to a close of $92.17/b. This morning it is trading close to unchanged at $92.1/b. That is just above the 100dma of $91.9/b and the 50% Fibo level of $92.6/b. The next technical level would be $100/b. Vortexa stated in a report ydy that ”Record crude shortfall building – and market may miss it in summer lull”. If so, then $100/b is maybe where we are heading in the near term. Argus reported however on Friday that CPC Blend exports (Kazakhstan) has increased to 1.8 mb/d from only 0.85 mb/d in the second half of July. This has eased the crude tightness in Europe as it coincides with lower crude processing by European refineries due to maintenance and seasonal turnarounds.
China is standing in the way for US sanctions towards Iran. The US is threatening Iran with economic destruction via sanctions. But China is normally buying 90% of Iran’s crude and is strongly opposed to sanctions arguing that they don’t work. China cannot allow the US to dictate from whom it can buy crude oil or not. Xi Jinping is set to meet Trump in the US in a couple of weeks from now. There is no chance that the US will hit secondary sanctions on Chinese entities dealing in Iranian oil. How to make economic sanctions against Iran work when China is not a part of if is Trump’s big headache.
Natural gas – Winter panic sets in as there is no opening of Hormuz in sight. European natural gas is rallying amid low seasonal nat gas stocks and no reopening of the SoH in sight. European nat gas for December delivery is trading at EUR 67.5/MWh or about $136/boe. That is more than a 50% premium to Brent crude delivered in December. That measure traded in a range of 30% to 40% premium from mid-July to mid-August but has now jumped straight to 50%.
European natural gas inventories are currently at 63% versus a seasonal norm of 80.6%. That is 17.6% lower than 2010-2025 average.
The European nat gas market has stayed relatively calm for a long time in the hope that the Strait of Hormuz would open ”very soon” as Trump insisted all the time. Assuming that stocks ahead of winter could be rebuilt rapidly once the SoH was reopened. Now, however, there is no clarity on a reopening. No one expects it to happen anytime soon. As a result, the European nat gas market has run into a bit of a winter-panic over the past week.
Asian LNG buyers are part of the winter bidding-war. The European nat gas prices are however not set by European nat gas buyers alone. It is set in a cross-bidding for LNG cargoes between Asia and Europe. The fact that nat gas for December delivery has rallied to a 50% premium to Brent crude is probably indicating that Asian buyers are bidding strongly into this rally as well.
There are no strategic reserves for natural gas. The problem with natural gas is that there are no large inventories since gas is difficult and expensive to store. That is why the nat gas market is much more stressed over having lost 20% of seaborn supply normally coming from the SoH.
Dry rivers and low hydroelectric levels adds to Europe’s winter risk. Europe has also gotten into trouble due to the record hot and dry summer. Hydroelectric reservoirs are unusually low ahead of winter while low river levels are holding back nuclear and other thermal power plants from running.
A warm 2026/27 winter would help a lot. But the 2026/27 winter looks set to be warmer than normal according to seasonal forecasts for what they are worth.
European natural gas inventories are significantly below the 2010-2025 average

TTF nat gas for December delivery has jumped to a 53% premium to Brent crude.

Nat gas forward prices versus Brent crude forward prices. Nat gas is about winter risk as there are no strategic reserves (inventories) of natural gas other than commercial stocks.





Dieselpriset i USA passerade idag upp över 200 USD per fat

Finska kärnkraftverket Loviisa förlänger livstiden till 2050 med hjälp av Google
Dated Brent and Oman crude are showing the way higher

Kopparpriset stiger när den fysiska världen gör sig påmind
Tightness today versus risk of surplus tomorrow
No reopening of SoH anytime soon. Winter could be expensive for oil product consumers

Saskatchewan bygger en av världens största urangruvor, kan stå för en femtedel av den globala produktionen

Pirater från Somalia kapar tankfartyg som fraktat oljeprodukter från Iran

Guldet rör sig i ton, betalningarna rör sig i millisekunder: Vad finansmarknadernas infrastruktur lär oss om digital penningrörelse

Irland har inlett en debatt om att ta bort förbudet av kärnkraft
-
Analys4 veckor sedan
No reopening of SoH anytime soon. Winter could be expensive for oil product consumers
-
 Nyheter2 veckor sedan
Saskatchewan bygger en av världens största urangruvor, kan stå för en femtedel av den globala produktionen
-
 Uncategorized4 veckor sedan
Guldet rör sig i ton, betalningarna rör sig i millisekunder: Vad finansmarknadernas infrastruktur lär oss om digital penningrörelse
-
 Nyheter3 veckor sedan
Pirater från Somalia kapar tankfartyg som fraktat oljeprodukter från Iran
-
 Nyheter2 veckor sedan
Irland har inlett en debatt om att ta bort förbudet av kärnkraft
-

 Nyheter2 veckor sedan
Jeffrey Currie – Råvarorna skickar en varningssignal, guld gynnas från två håll
-
Analys3 veckor sedan
Stay long or buy-on-dips in the run-up to the US midterm elections on 3 Nov
-
Analys2 veckor sedan
Oil close to technical levels while EU nat gas is gripped by winter-panic