

Analys
SEB – Jordbruksprodukter, vecka 50

 I detta det sista veckobrevet för 2011 om marknaderna för jordbruksprodukter kan vi summera året. Det senaste året har priset på kvarnvete sjunkit med 23%, rapsfrö med 12%. Mjölkpriset har stigit med 35% och urea med 52%. Tack vare gynnsamt väder har priset på potatis fallit med 71% på Eurexbörsen i Frankfurt. Dollarn är upp med 3% mot svenska kronor och euron är oförändrad, faktiskt.
Konjunkturoron och med den oron för svagare efterfrågan på mat tynger marknaderna just nu. Precis som väntat åstadkom EU-ledarna ingenting, vilket gick upp för marknaden på måndagen när stora kursfall noterades på råvaru-, kapital- och kreditmarknader i hela världen. Det hela sjönk in ordentligt på onsdagen, när panikförsäljning startade i guldmarknaden och sedan spred sig till oljemarknaden och slutligen till hela råvarumarknaden. OPEC kom under onsdagens möte i Wien fram till att öka produktionen av olja (höja produktionstaket). Det hjälpte inte upp situationen på marknaden.
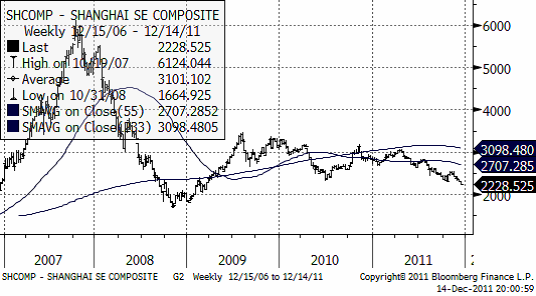
Den ledande kinesiska websidan för fastighetsbranschen sade i måndags att antalet fastighetsaffärer har fallit mer än 50% i 13 av de 35 största städerna och sjunkit i 27 av dem. Kinas ekonomi bromsar in och Shanghaibörsens aktieindex noterade ett kursfall i onsdags till den lägsta nivån på mer än 2 år.
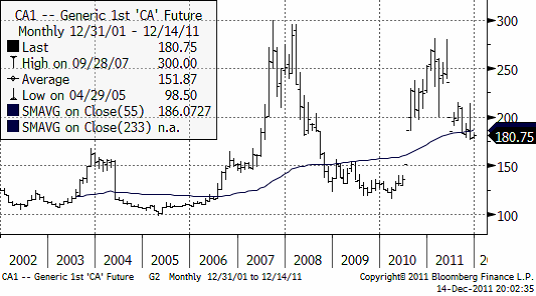
Nedan ser vi vetepriset på Matif de senaste tio åren. Priset är faktiskt ganska högt ännu i ett historiskt perspektiv och det är fortfarande attraktiva priser att säkra framtida försäljning till genom att sälja terminskontrakt.
Vete
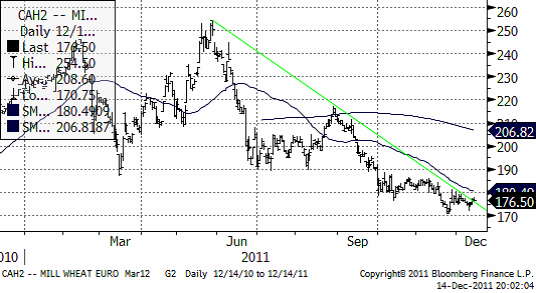
Terminspriset på Matif-vete (mars) ligger i en stadig trend nedåt.
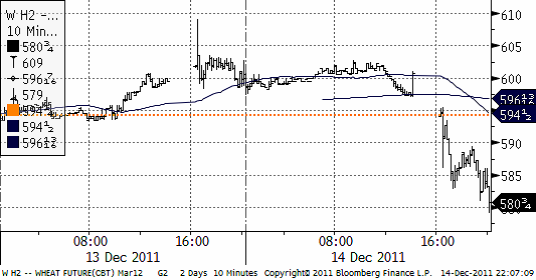
När handeln öppnade på CBOT i onsdags eftermiddag satta kursfallet fart. Priset för mars-leverans föll från 600 cent / bushel ner till 580 cent, som vi ser i diagrammet nedan.
Fredagens WASDE rapport bjöd inte på några större överraskningar då marknaden förväntade sig en höjning av estimaten för produktion samt utgående lager. Några dagar innan hade dessutom FAO kommit med sin decemberrapport där man justerade upp den globala vete produktionen till rekordhöga 694.8 mt, vilket är en ökning med 6.5% jämfört med 2010 och 10 mt mer än den tidigare högsta nivån från 2009.
 Den globala vete produktionen justerades upp 5.7 mt till en all-time-high på 688.97 mt, där USDA höjer sina estimat för Argentina, Australien, Kanada och Kina medan estimaten för Nordafrika sänks något.
Produktionen för EU-27 noterades oförändrad (137.49 mt) från föregående rapport. Även produktionen i Ryssland och Kazakhstan var oförändrad (56 mt resp 21 mt) medan FAO tidigare i veckan estimerade produktionen till 58 mt resp 24 mt för dessa länder.
Utgående lager (world wheat ending stocks) för 2011/12 justeras upp till 208.52 mt jämfört med 202.60 mt för en månad sedan. Detta gör att vi nu börjar närma oss historiska rekordnivåer. Intressant var också utgående lager för USA. Innan rapporten förväntade sig marknaden en snittsiffra på ca 830 miljoner bushels, en liten förändring från novembers 828 miljoner bushels, men när rapporten kom hade USDA justerat upp siffran med 50 miljoner och landade på 878 miljoner till följd av en nedjustering på 50 miljoner bushels för estimerad export.
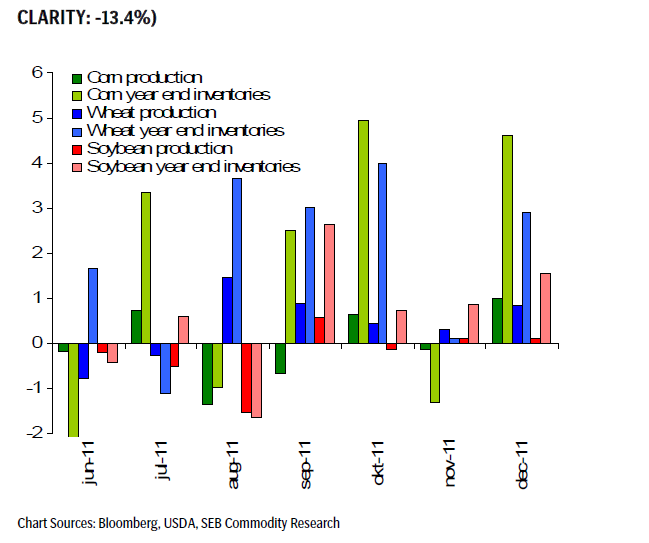
Terminspriserna sjönk som en första reaktion på WASDE-rapporten för att sedan återhämtade sig trots att rapporten var starkt ”bearish” för vetet med rekordskördar, höga lagernivåer och minskad export. Vi ser i grafen nedan (procentuell förändring) att detta är femte månaden i följd som USDA har reviderat upp produktionen och utgående lager för vete!
PRODUCTION AND INVENTORY ESTIMATE
REVISIONS
(WASDE, MONTHLY DATA, %, JUNE CORN INV. EST. CUT FOR
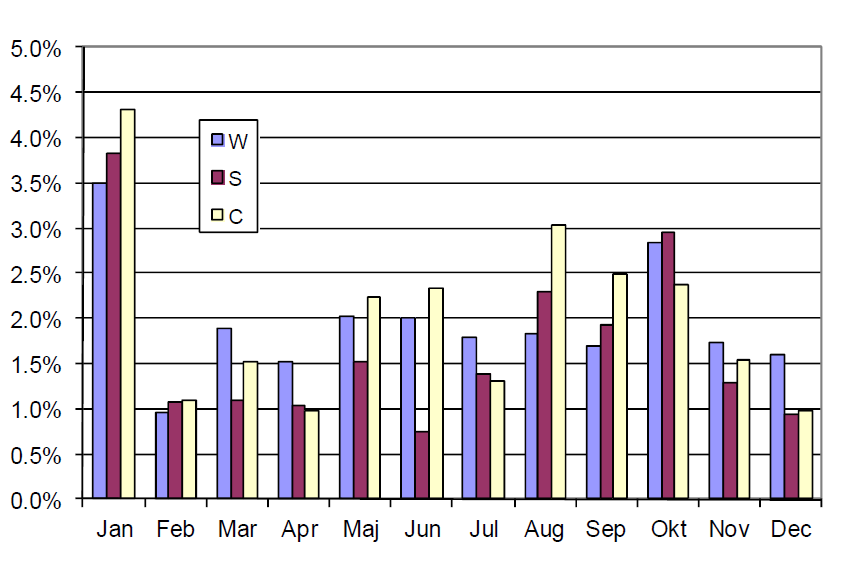
Men redan nu börjar marknaden att blicka fram emot januaris WASDE-rapport. Det är den rapportsom brukar ge de största prisrörelserna när den kommer ut:
Genomsnittlig prisrörelse på WASDE-rapporteringsdagar sedan 2002 (10 år):
I fredags publicerade också FranceAgriMer sina arealprognoser för nästa säsong där man räknar med följande ökningar av arealen; vete (+1,61%), durumvete (2,79%), korn (0,91%) och raps (+1,75%). Frankrike är EU:s största producent och exportör av vete.
Enligt Coceral kommer den europeiska (EU-27) vete produktionen att uppgå till 129.64 mt i år, vilket är en justering från 128.39 mt från förra månaden.
Egyptens GASC köpte 180,000 ton vete i tisdags med jämn fördelning mellan Ryssland, Argentina och… Frankrike! Priset på det franska vetet som vann budgivningen kom in på 240.50 usd / ton, vilket var ca 3.50 usd / ton billigare än det ryska vetet på 243.98 usd / ton (FOB). Ryssland har dock ett övertag mot Frankrike vad gäller frakt (kostnad) till Egypten. Argentina erbjuder fortfarande det billigaste vetet (226.19 usd / ton) men har dyrare fraktkostnad emot sig.
Nämnvärt är också att US White Wheat fanns med i denna budgivning, men exkluderades då leveransen inte avsåg 60,000 ton. Vi ser dock att gapet i prisskillnaderna nu minskar och att både det franska och amerikanska vetet börjar bli konkurrenskraftigt mot FSU länderna.
Även det kraftiga fallet i euron ger stöd åt jordbruksprodukterna på Matif och gör att Europa åter kan konkurrera på den internationella marknaden.
Nedan ser vi terminskurvan för Chicagovete och Matif nu och för en vecka sedan. De ”feta” kurvorna är de aktuella. De ”smala” är förra veckans. Matif är nästan inte förändrat alls, medan priserna liksom förra veckan gått upp i Chicago – för längre löptider. Bakom ligger oro för kommande skörd pga La Niña kanske och förmodligen också för att räntorna (som man kan låna till) är högre.
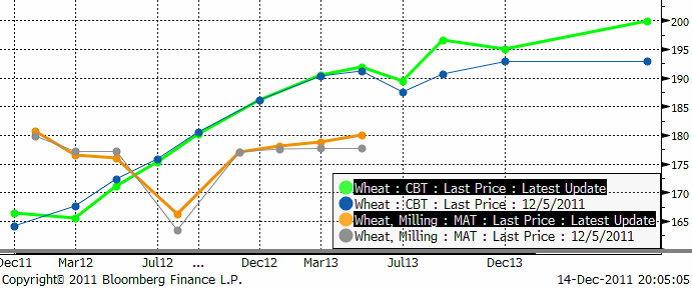
Allt talar för att Matif-vete faller ner i första hand till 150 – 160 – euro-nivån.
Maltkorn
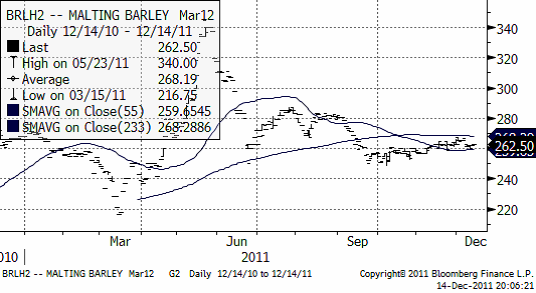
Maltkornsmarknaden har behållit sin styrka relativt andra spannmål med marsleverans på Matif på 262 euro per ton.
I Ryssland försöker regeringen att stödja produktionen av maltkorn genom subventioner av inköp av utsäde och bekämpningsmedel. Även om Ryssland producerar 17 MMT foderkorn så importeras det 400 000 ton maltkorn varje år sedan 2007 för att möta de behov som finns.
Potatis
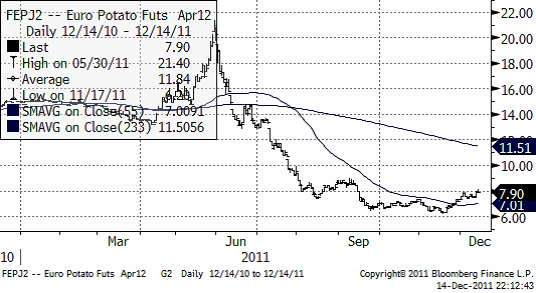
Priset på potatis av årets skörd fortsatte stiga i veckan, ännu en vecka. Rapporten kom från Jordbruksverket tidigare i veckan om en betydligt högre skörd av matpotatis i Sverige, men informationen nådde alltså marknaden redan på försommaren, när priserna började falla. Nedan ser vi kursdiagrammet på europeisk potatis, som handlas på Eurex; terminen avser leverans april 2012.
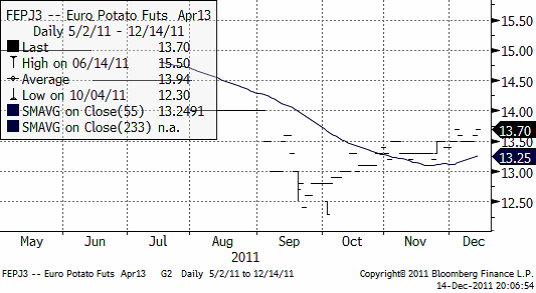
Priset för leverans i april 2013 ligger betydligt högre på 13.37 euro per deciton och har också stigit ännu mer den senaste tiden.
Majs
Majspriset föll liksom det mesta andra kraftigt när börserna öppnade på onsdagseftermiddagen. Den 12 december rapporterade Martell Crop Projections att tork-stressen ökat i Argentina och södra Brasiliens majsfält. De skriver
”Growing conditions have become increasingly stressful in southern South America the past 2-3 weeks with intense drying. The crop area affected by emerging drought includes Argentina’s eastern grain belt in Buenos Aires, Entre Rios and Santa Fe. La Nina is the suspected culprit. Uruguay and Rio Grande do Sul in Brazil also are very dry.”
Kopplingen till etanol och oron kring Irans kärnvapenprogram och dess potentiellt explosiva effekt på oljepriset gör majshandlare oroliga att sälja, fast mycket annat tyder på att priset borde vara lägre.
Nedan ser vi marskontraktet på CBOT, där priset just fallit ner från 600-cent-nivån.
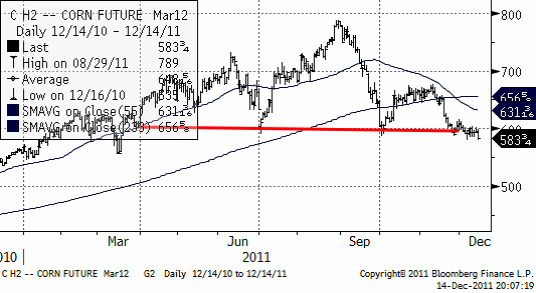
Tekniskt ser det ut som om priset skulle kunna falla ner mot 500 cent.
Sojabönor
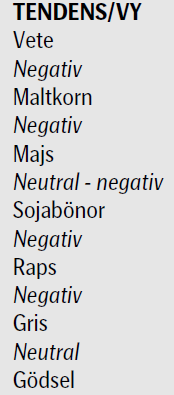
Priset på sojabönor befinner sig i en sjunkande trend. Vi sade i förra veckan att den lilla rekylen uppåt var ett säljtillfälle och det visade sig rätt. Priset ligger just nu på 1100 cent, som har utgjort ett stöd. Troligtvis bryter trenden nedåt igenom nivån och då blir nästa nivå som kan utgöra ett stöd, den jämna siffran 1000 cent.
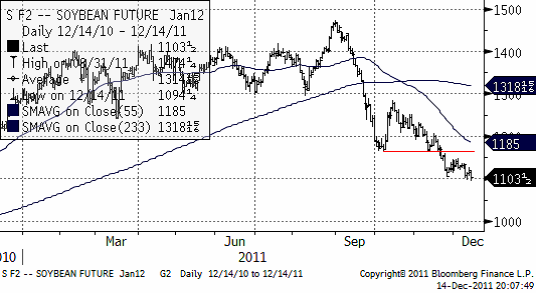
Vi är negativa ur tekniskt perspektiv de närmaste tre månaderna.
Raps
Priset på raps har gått upp och håller sig starkt med stöd från den svaga euron.
Uppgifter om att Hormuz-sundet skulle stängas på grund av militärövning (vilket förnekades av Irans utrikesdepartement) och nyheten om en attack mot en oljeledning i Irak fick råoljepriset att stiga under tisdagen och drog med sig priset på raps. Priset har också påverkats av oro över de extremt torra väderförhållanden som kan komma att påverka ny skörd.
Oljepriset föll under onsdagskvällen mycket kraftigt, med mer än 4% för Brent och mer än 5% för West Texas Intermediate. Detta bör påverka rapsfröet på Matif under torsdag och fredag. Nedan ser vi priset på februariterminen på Matif.
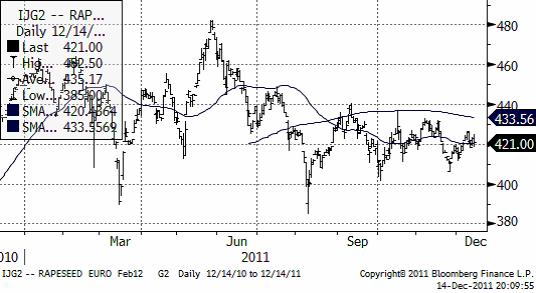
Matifraps var förra veckan 13% dyrare än kanadensisk canola och ligger kvar på samma nivå den är veckan. Raps är ovanligt dyrt.
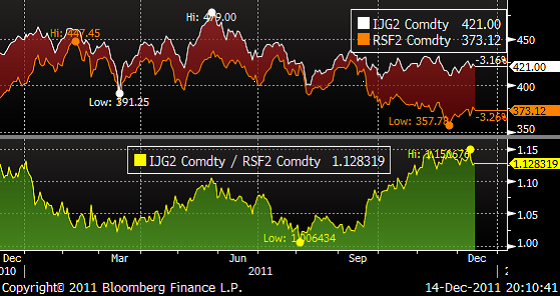
Vi har en negativ vy på Matif raps.
Mjölk
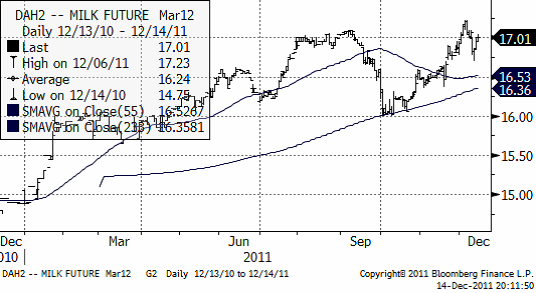
Nedan ser vi priset på marskontraktet på flytande mjölk (kontakt avräknat mot USDA:s prisindex). Priset har varit väldigt rörligt den senaste tiden. Trenden är uppåtriktad, men är vid den nivå som priset toppade vid under sensommaren. Det kan utgöra ett motstånd för ytterligare prisuppgång.
Gris
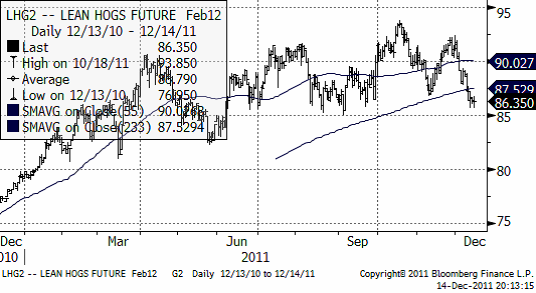
Priset på lean hogs har fallit stadigt den senaste veckan, men priset ligger ännu inom det breda prisintervall som etablerades under senvåren. 85 cent torde utgöra ett stöd, såsom botten på prisintervallet.
Valutor
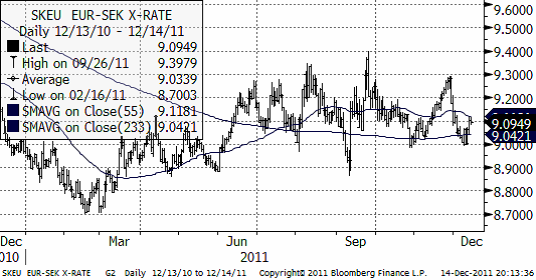
EURSEK har märkligt nog stigit upp från 9 kr. Kanske tycker marknaden att det finns anledning att tveka även om den svenska kronans värde.
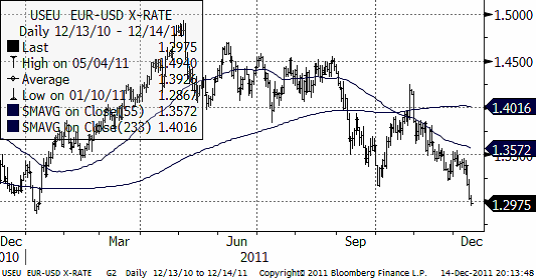
EURUSD är i en tydlig negativ trend.
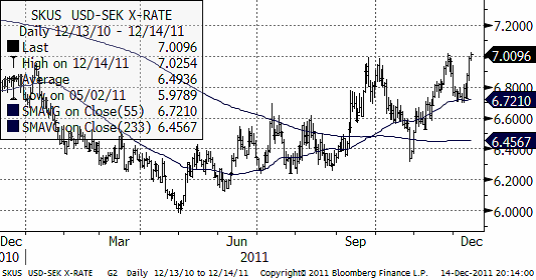
USDSEK har en stigande trend och har nått upp till heltalet 7 kr per dollar. Växelkursen har vänt ner därifrån två gånger tidigare och frågan är nu om kursen ska orka ta sig igenom den här gången.
Gödsel
Kväve
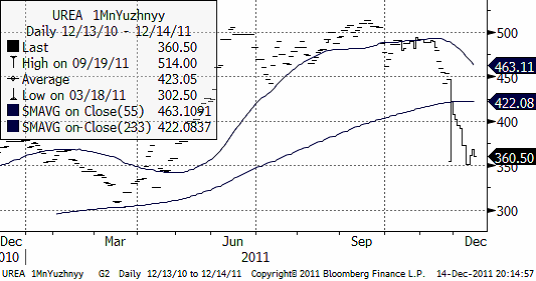
Nedan ser vi 1 månads terminspris på Urea fob Uyzhnyy. Priset har fallit kraftigt under hösten.
[box]SEB Veckobrev Jordbruksprodukter är producerat av SEB Merchant Banking och publiceras i samarbete och med tillstånd på Råvarumarknaden.se[/box]
Disclaimer
The information in this document has been compiled by SEB Merchant Banking, a division within Skandinaviska Enskilda Banken AB (publ) (“SEB”).
Opinions contained in this report represent the bank’s present opinion only and are subject to change without notice. All information contained in this report has been compiled in good faith from sources believed to be reliable. However, no representation or warranty, expressed or implied, is made with respect to the completeness or accuracy of its contents and the information is not to be relied upon as authoritative. Anyone considering taking actions based upon the content of this document is urged to base his or her investment decisions upon such investigations as he or she deems necessary. This document is being provided as information only, and no specific actions are being solicited as a result of it; to the extent permitted by law, no liability whatsoever is accepted for any direct or consequential loss arising from use of this document or its contents.
About SEB
SEB is a public company incorporated in Stockholm, Sweden, with limited liability. It is a participant at major Nordic and other European Regulated Markets and Multilateral Trading Facilities (as well as some non-European equivalent markets) for trading in financial instruments, such as markets operated by NASDAQ OMX, NYSE Euronext, London Stock Exchange, Deutsche Börse, Swiss Exchanges, Turquoise and Chi-X. SEB is authorized and regulated by Finansinspektionen in Sweden; it is authorized and subject to limited regulation by the Financial Services Authority for the conduct of designated investment business in the UK, and is subject to the provisions of relevant regulators in all other jurisdictions where SEB conducts operations. SEB Merchant Banking. All rights reserved.


Dated Brent and Oman crude are showing the way higher. The Brent crude M1 contract (October) gained another 0.75% yesterday. It traded in a range of $95.97-95.06/b and closed at $97.0/b. This morning it gains another 1.4% to $98.4/b. The Dubai M1 contract which is settled in November is showing the way at $105/b while Dated Brent settled ydy at $106.8/b. Brent crude M1 is now well above both the 50dma, 100dma and 200dma and is heading towards the 61.8% Fibo level of $100.55/b with $110.44/b next in line technical level thereafter.

Tight oil product markets are helping to drive crude oil prices higher as well. The strong push upwards for the Dated Brent price with ydy price reaching $106.8/b. Behind that drive upwards it very tight oil product markets with balance of month diesel refining margins in ARA now close to $90/b and gasoil cracks have been reported to top $100/b for the first time ever. That means extreme profitability for refineries. In response refineries here, there and everywhere want to get their hands on physical crude as quickly as possible. Convert it to oil products and sell the products into the ultra-tight spot oil product markets. Especially the diesel segment (Jet, diesel, gasoil). The economic incentive is huge for refineries.
This drive by refineries to process more crude in response to high refining margins, usually kicks in at much lower levels. Thereby normally transferring tightness from the oil product market over to the crude oil market. That normal mechanism hasn’t really worked properly in this crisis so far since there hasn’t been all that much spare refining capacity left as Ukraine is constantly damaging Russian refineries while the semi-closure of the SoH has sharply reduced oil product exports.
Stronger Chinese crude oil imports but higher oil product exports as well. Chines crude imports rose 6.2% MoM in August to 9.21 mb/d. That was still 2.9 mb/d below the 2025 average of 12.1 mb/d. But China’s net oil product exports rose to 0.91 mb/d in August which is the highest level since February 2023. As a result, Chinese imports of crude and oil products was still 3.5 mb/d below the 2025 average versus 3.6 mb/d in July. That is a strengthening of net imports of only 0.1 mb/d. Not much change in total. But it shows that Chinese refineries, probably with the blessing of government, are importing more crude and re-export these as oil products. That helps to transfer oil product tightness to crude oil tightness. India is doing the same. In July it exported about 1.4 mb/d of oil products and the highest since September.
The Iran-Oman deal on the SoH will give China a forceful political option. The Iran-Oman agreement over how to operate the SoH is just days away from finalization says Iran. The IMO and the US is said to have been involved in the process. Once it is agreed and published, China will have the option to sail a Chinese flagged VLCC through the SoH according to the new, official regulation of the SoH, load oil at Kharg Island and take it back to China. That is a very forceful option for China.
Oil and the SoH will for sure be a hot topic when Trump and Xi Jinping meets in the US on 25 September. And China will have some forceful bargaining chips to play versus Donald Trump regarding the SoH and oil.
ARA balance of month refining margins at close to $90/b giving refineries strong incentives to run hard converting crude to products = stronger refinery crude oil demand

Dated Brent and Oman crude (settled outside of the Persian Gulf) are showing the way upwards

Chinese crude (crude) and net crude and oil product imports (red) versus the 2025 average. Net crude and oil product imports was 3.5 mb/d below the 2025 average in August and 3.6 mb/d below in July. Almost the same. Stronger crude imports but also higher oil product exports

Chinese oil product exports rose to 0.91 mb/d in August and highest since Feb 2023. (numbers in reverse)

Oil markets remain tight as the Strait of Hormuz (SoH) continues to be constrained. Things could become much tighter if it is fully closed. However, the outlook could change rapidly if flows normalise in early 2027. A large underlying surplus, rebuilding supply and the risk of more volume from OPEC+ could turn today’s tightness into a significantly weaker oil market in 2027-28.
Eventual reopening looks set to bring surplus
The SoH is constrained, not fully closed. Enough crude is escaping, while alternative pipelines, decreased Chinese imports and SPR releases have helped keep Brent at c. USD 90/bbl. Oil products are much tighter. A full reopening of the SoH would flip the market into surplus. We assume SoH flows normalise from early 2027. The market could then face a 4-5m bbl/d surplus before restocking. We forecast Brent at USD 75/bbl in 2027 and USD 70/bbl in 2028.
We expect OPEC+ to opt for more volume once SoH exports normalise
OPEC+ will likely opt for more volume. The UAE has already chosen volume, Iraq wants to expand and Venezuela looks set to exit. There is a clear risk of controlled OPEC+ supply growth, adding to downside risks for 2027-28.
Natural gas market: Winter risk ahead, yet LNG balance to loosen from 2026
Natural gas inventories in Europe are well below normal. The market had hoped for a revival in Persian Gulf LNG exports from Qatar. However, with no signs of any imminent reopening of the SoH, it might be too late for Middle East LNG cargoes to arrive in Europe before the end of winter 2026/27. TTF natural gas winter prices have rallied in response, but that is predominantly a winter risk with prices trading sharply lower after March 2027. Growing global LNG export capacity in the years to come should push prices lower.
Brent crude converging to technical levels. Brent crude has traded in a range of $90-95/b over the past five days. It pulled back 2.4% yesterday to a close of $92.17/b. This morning it is trading close to unchanged at $92.1/b. That is just above the 100dma of $91.9/b and the 50% Fibo level of $92.6/b. The next technical level would be $100/b. Vortexa stated in a report ydy that ”Record crude shortfall building – and market may miss it in summer lull”. If so, then $100/b is maybe where we are heading in the near term. Argus reported however on Friday that CPC Blend exports (Kazakhstan) has increased to 1.8 mb/d from only 0.85 mb/d in the second half of July. This has eased the crude tightness in Europe as it coincides with lower crude processing by European refineries due to maintenance and seasonal turnarounds.
China is standing in the way for US sanctions towards Iran. The US is threatening Iran with economic destruction via sanctions. But China is normally buying 90% of Iran’s crude and is strongly opposed to sanctions arguing that they don’t work. China cannot allow the US to dictate from whom it can buy crude oil or not. Xi Jinping is set to meet Trump in the US in a couple of weeks from now. There is no chance that the US will hit secondary sanctions on Chinese entities dealing in Iranian oil. How to make economic sanctions against Iran work when China is not a part of if is Trump’s big headache.
Natural gas – Winter panic sets in as there is no opening of Hormuz in sight. European natural gas is rallying amid low seasonal nat gas stocks and no reopening of the SoH in sight. European nat gas for December delivery is trading at EUR 67.5/MWh or about $136/boe. That is more than a 50% premium to Brent crude delivered in December. That measure traded in a range of 30% to 40% premium from mid-July to mid-August but has now jumped straight to 50%.
European natural gas inventories are currently at 63% versus a seasonal norm of 80.6%. That is 17.6% lower than 2010-2025 average.
The European nat gas market has stayed relatively calm for a long time in the hope that the Strait of Hormuz would open ”very soon” as Trump insisted all the time. Assuming that stocks ahead of winter could be rebuilt rapidly once the SoH was reopened. Now, however, there is no clarity on a reopening. No one expects it to happen anytime soon. As a result, the European nat gas market has run into a bit of a winter-panic over the past week.
Asian LNG buyers are part of the winter bidding-war. The European nat gas prices are however not set by European nat gas buyers alone. It is set in a cross-bidding for LNG cargoes between Asia and Europe. The fact that nat gas for December delivery has rallied to a 50% premium to Brent crude is probably indicating that Asian buyers are bidding strongly into this rally as well.
There are no strategic reserves for natural gas. The problem with natural gas is that there are no large inventories since gas is difficult and expensive to store. That is why the nat gas market is much more stressed over having lost 20% of seaborn supply normally coming from the SoH.
Dry rivers and low hydroelectric levels adds to Europe’s winter risk. Europe has also gotten into trouble due to the record hot and dry summer. Hydroelectric reservoirs are unusually low ahead of winter while low river levels are holding back nuclear and other thermal power plants from running.
A warm 2026/27 winter would help a lot. But the 2026/27 winter looks set to be warmer than normal according to seasonal forecasts for what they are worth.
European natural gas inventories are significantly below the 2010-2025 average

TTF nat gas for December delivery has jumped to a 53% premium to Brent crude.

Nat gas forward prices versus Brent crude forward prices. Nat gas is about winter risk as there are no strategic reserves (inventories) of natural gas other than commercial stocks.





Dieselpriset i USA passerade idag upp över 200 USD per fat

Finska kärnkraftverket Loviisa förlänger livstiden till 2050 med hjälp av Google
Dated Brent and Oman crude are showing the way higher

Kopparpriset stiger när den fysiska världen gör sig påmind
Tightness today versus risk of surplus tomorrow
No reopening of SoH anytime soon. Winter could be expensive for oil product consumers

Saskatchewan bygger en av världens största urangruvor, kan stå för en femtedel av den globala produktionen

Guldet rör sig i ton, betalningarna rör sig i millisekunder: Vad finansmarknadernas infrastruktur lär oss om digital penningrörelse

Pirater från Somalia kapar tankfartyg som fraktat oljeprodukter från Iran

Irland har inlett en debatt om att ta bort förbudet av kärnkraft
-
Analys4 veckor sedan
No reopening of SoH anytime soon. Winter could be expensive for oil product consumers
-
 Nyheter2 veckor sedan
Saskatchewan bygger en av världens största urangruvor, kan stå för en femtedel av den globala produktionen
-
 Uncategorized4 veckor sedan
Guldet rör sig i ton, betalningarna rör sig i millisekunder: Vad finansmarknadernas infrastruktur lär oss om digital penningrörelse
-
 Nyheter3 veckor sedan
Pirater från Somalia kapar tankfartyg som fraktat oljeprodukter från Iran
-
 Nyheter2 veckor sedan
Irland har inlett en debatt om att ta bort förbudet av kärnkraft
-

 Nyheter2 veckor sedan
Jeffrey Currie – Råvarorna skickar en varningssignal, guld gynnas från två håll
-
Analys3 veckor sedan
Stay long or buy-on-dips in the run-up to the US midterm elections on 3 Nov
-
Analys2 veckor sedan
Oil close to technical levels while EU nat gas is gripped by winter-panic