

Analys
SEB Jordbruksprodukter, 14 januari 2013

 I fredags på den nya tiden 18:00 publicerade det amerikanska jordbruksdepartementet årets första World Agricultural Supply and Demand Estimates (WASDE) och lagerstatistiken per den 1 december samt sådd höstvete-areal. Vi går igenom WASDE-statistiken under respektive råvara längre fram i veckobrevet.
 Lagerstatistiken i miljoner bushels visade att det fanns mindre sojabönor och majs i lager i USA än marknaden hade väntat sig. Viktigast för dessa var majs, eftersom lagersituationen där är mest ansträngd efter sommarens torka i USA. Lagren visade sig vara ännu mindre än vad marknaden hade väntat sig. Det betyder att foderefterfrågan inom USA har varit större än vad marknaden hade väntat sig. Etanolproduktion och export har vi ju god koll på. Vi minns också att USDA i september gjorde en märklig uppjustering av lagren (1 september), som vi skrev att vi inte trodde på (att lagret borde vara lägre). Man hade ökat lagret per 1 september med den del som var skördad tidigt, skörden var ju ovanligt tidig, men inte i motsvarande mån minskat skörden resten av hösten.
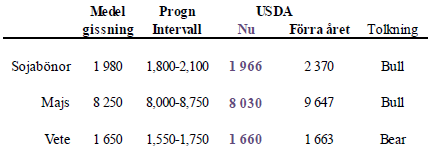
Lagren av sojabönor indikerar att priset bör gå upp något för att nå marknadsjämvikten. För vete motiveras något lägre pris, men det är så lite att det nästan är försumbart.
Om vi så går vidare med vetet för att se hur mycket som var sått i miljoner acres, enligt USDA:s statistik, av höstvete, kan vi se att det är väsentligt mindre Hard Red Winter Wheat, den sort som handlas på Kansas City Board of Trade. Det har såtts mindre HRWW än förra året, till och med. HRWW innehåller mer protein än Chicago-sorten, Soft Red Winter Wheat. Det har såtts mer SRWW än väntat och betydligt mer än förra året. Vi kan alltså vänta oss i år att premien för protein ökar i år.
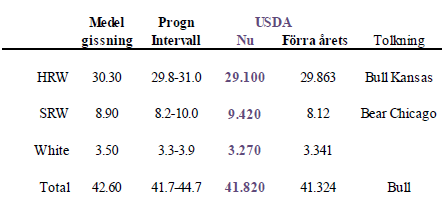
Sammantaget är det en rapport som indikerar högre priser för vete. Möjligtvis kommer detta att locka fram mer sådd av vårvete och i så fall mindre sådd av majs och sojabönor. I vilket fall, sammantaget en rapport som pekar på högre priser på alla dessa grödor.
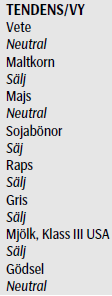
Vi ändrar nu rekommendationen för vete och majs till neutral från sälj.
Odlingsväder
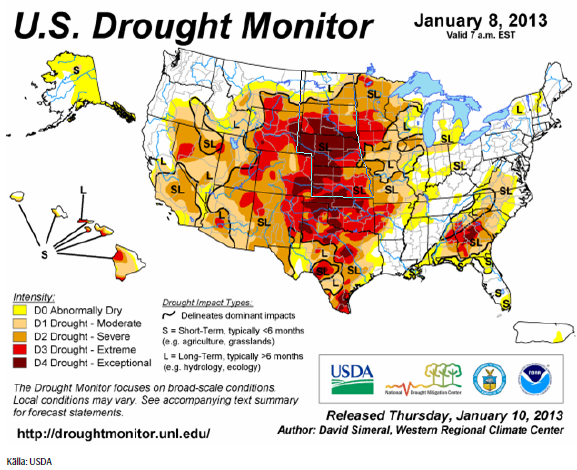
Torkan i USA håller i sig, som vi ser i den senaste ”Drought Monitor”, som publicerades i torsdags. Sedan förra veckan är det en marginell förbättring i torkan, dvs något lite mindre yta är drabbad av torka.
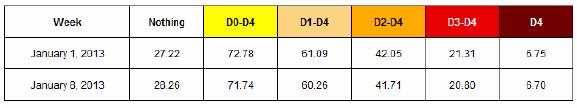
Sedan förra veckan har alla kategorier av torka (D0 – D4) minskat, som vi ser i nedanstående tabell.
I Kina har det varit extremt kallt vilket fått priset på höstvete att nå en rekordnivå. Mer om det nedan. I England har det regnat extremt mycket den senaste veckan. Höstvetet befaras ha tagit skada. Argentina fick tillbaka torrt väder i veckan (majs, sojabönor).
Vete
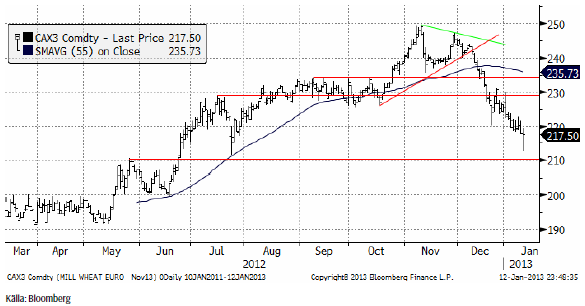
Nedan ser vi november (2013) kontraktet, där priset föll kraftigt i fredags, men återhämtade sig och stängde på 217.50, nästan oförändrat på dagen.
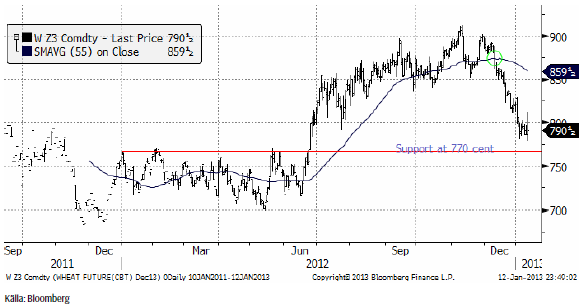
Nedan ser vi decemberkontraktet på CBOT. Chicago stängde upp efter fredagens handel, till skillnad från Matif. GASC, den Egyptiska statens huvudsakliga veteimportör, köpte 115,000 ton amerikanskt och kanadensiskt vete i den senaste tendern, som publicerades i veckan. Till nästa tender GASC franskt vete. Det amerikanska vetet är det billigaste i världen, men frågan är om man lyckas exportera allt eftersom Mississippi-floden har stängts på grund av lågt vattenstånd (orsakat av torkan).
Vi ser här en bild på terminskurvorna för Matif och Chicago, båda omräknade till euro per ton.
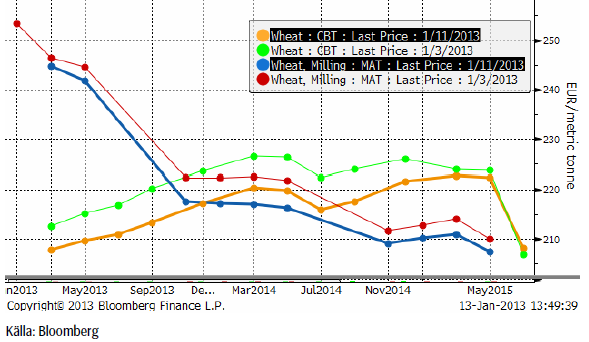
Av diagrammet ovan ser man att gammal skörd av Matif-vete är avsevärt mycket dyrare än Chicagovetet. Maj-terminen handlas dessutom lägre än mars-terminen. Det säger att den som väntar med att sälja till maj riskerar att få väsentligt sämre betalt – och dessutom får bära ränte- och lagerkostnader fram till dess. Den som vill ta en position på högre priser och har fysiskt vete i lager gör därför sannolikt bäst i att sälja den fysiska varan och istället köpa terminer.
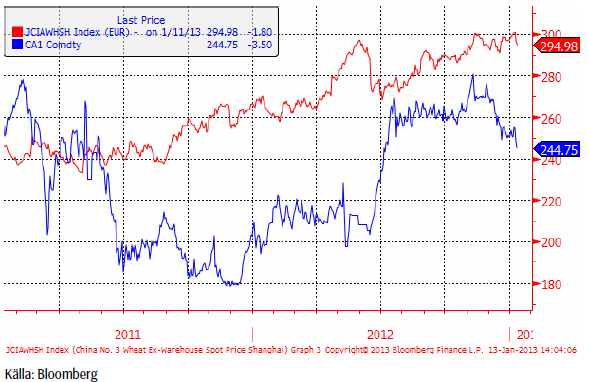
I Kina har priset på vete stigit till en ny rekordnotering. Det har i våra ”mainstream” media helt missats att Kina drabbats av den värsta kylan på över 30 år och den har skadat höstvetet långt söderut i landet. Priset var efter årsskiftet uppe på över 300 euro per ton för spotleverans i Shanghai. I diagrammet är priset omräknat från Renminbi till euro per ton. Vi ser också spotkontraktet på Matif som jämförelse.
Kina har inte varit någon nettoimportör av vete sedan 2004/05, men risken finns att de måste importera mer framöver. I år räknar USDA med att Kina ska importera 3 mt, som vi ser i diagrammet nedan.
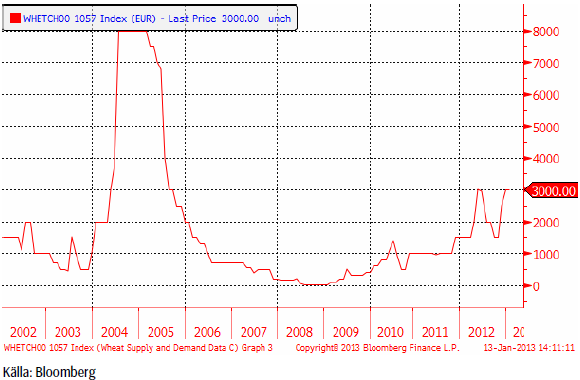
De råvaror som Kina blivit blivit nettoimportör av har rusat iväg i pris.
I fredagens WASDE-rapport sänkte USDA produktionsestimatet för skörden i år med 0.8 mt, fördelat i Argentina och Ryssland/Ukraina.
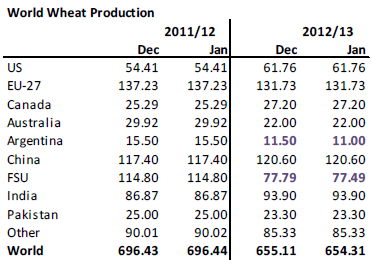
Utgående lager enligt USDA ser vi nedan. Vi ser att det är en liten sänkning. Sänkningar gjordes för USA och Ryssland/Ukraina. Höjningar gjordes däremot för Australien och Kanada på grund av att man antagit lägre export.
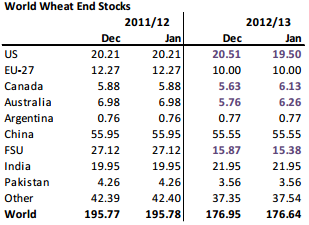
Själva WASDE-rapporten innehöll inget speciellt kursdrivande. Förväntad sådd areal, däremot, som vi gick igenom i inledningen till veckobrevet, indikerade att priset ”bör” kunna gå upp.
Ser vi förhållandet mellan pris och utgående lager i ett historiskt perspektiv, ser vi att priset för spotkontraktet (det med kortast återstående löptid) på CBOT ligger ganska mycket i linje med de senaste årens relation mellan utgående lager och pris.
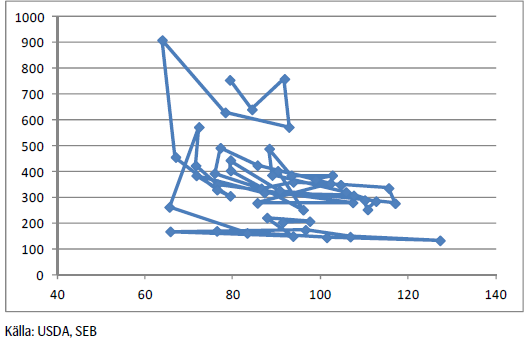
Slutsatsen efter att ha gått igenom såväl den tekniska bilden, som WASDE-rapporten, lager per 1 december och höstvete-areal, är att marknaden bör etablera en botten på de här nivåerna och stabilisera sig. Vi går därför över till en neutral rekommendation. Ytterligare motiv för detta är att situationen i majsmarknaden är ännu mer ”bullish”.
Maltkorn
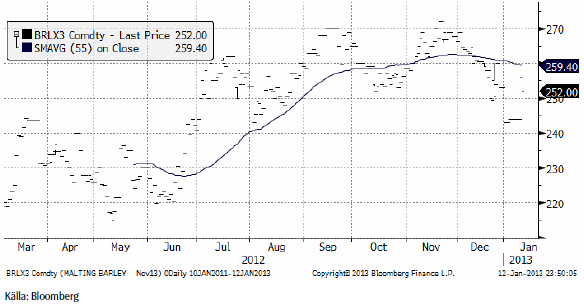
November 2013-kontraktet fortsätter att hoppa sig framåt. I veckan steg priset upp nästan till 260 euro per ton, men föll i fredags ner till 252 euro. 240 euro är en tydlig stödnivå strax under. Det förefaller som om de allra ivrigaste maltkornsköparna har den som ”fyndnivå”. Vi kan också se att de lite mindre ivriga maltkornsköparna tycks vara villiga att köpa kring 220 euro per ton. Det finns alltså ganska gott om stödnivåer för priset strax under dagens prisnivå för kommande skörd.
Potatis
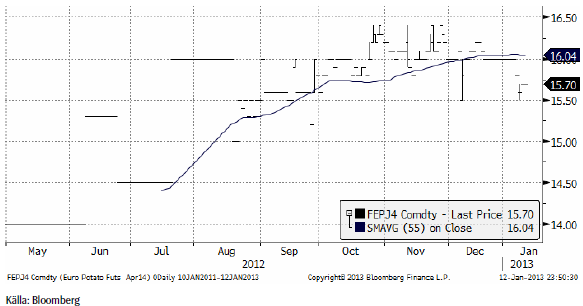
Potatispriset för leverans i april nästa år (2014) har sjunkit något sedan förra veckan och handlas på 15.70 euro per deciton. Det är i den nedre delen av det prisintervall som potatisen som skördas i höst har handlats till sedan september.
Majs
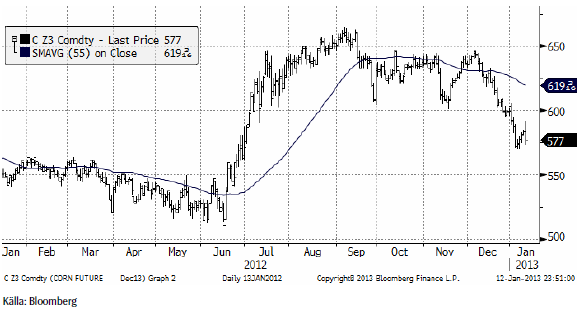
Majspriset (december 2013) reagerade på fredagens WASDE-rapport med att först stiga och sedan falla. Tekniskt stöd finns på 550 cent i decemberkontraktet, som vi ser i diagrammet nedan. Vi tycker inte att rapporten från USDA motiverar lägre pris.
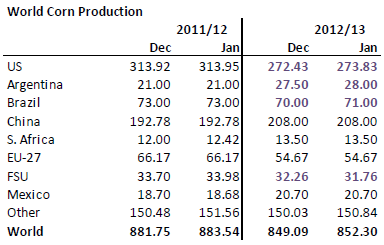
WASDE-rapportens produktionsestimat ser vi nedan och det är alltså en höjning från december med 3 mt på global basis. Höjningarna gjordes för USA, Argentina och Brasilien.
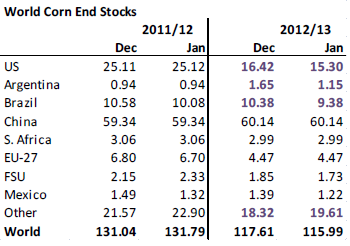
Utgående lager sänktes på global basis till 116 mt från 117.6 beroende på att man antagit en högre foderefterfrågan och för att lagren per 1 december var lägre än vad USDA tidigare antagit. Att foderefterfrågan var högre under det fjärde kvartalet än vad USDA antagit innebär att den kommer att vara det även under det första och kanske andra kvartalet i år också. Med så pass låga som lagren är, behövs en riktigt stor skörd i år. Och för att det ska ske kan inte priset fortsätta att falla.
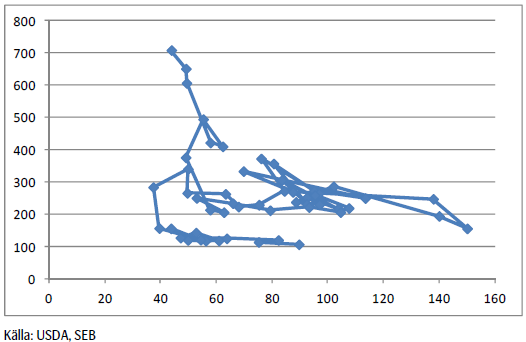
Nedanμ ser vi förhållandet mellan lager och pris. Vi ser att priset är exceptionellt högt i ett historiskt perspektiv, men lagren är också exceptionellt låga.
Vi ska titta på lagren i ett historiskt perspektiv nu i termer av dagars konsumtion:
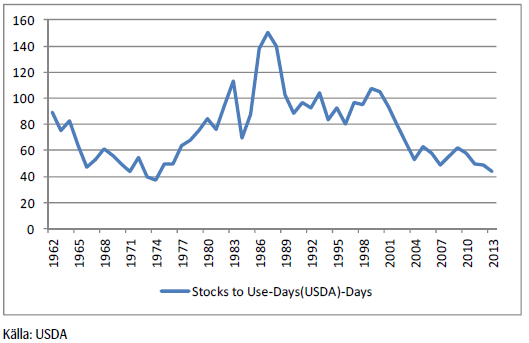
Sammanfattnignsvis: Det behövs en riktigt ordentlig skörd av majs i USA för att utbudet ska återställas. Lagerrapporten tyder på att foderefterfrågan är större än väntat och globala lager är nära rekordlåga nivåer. Vi går därför över till en neutral rekommendation på majsen.
Sojabönor
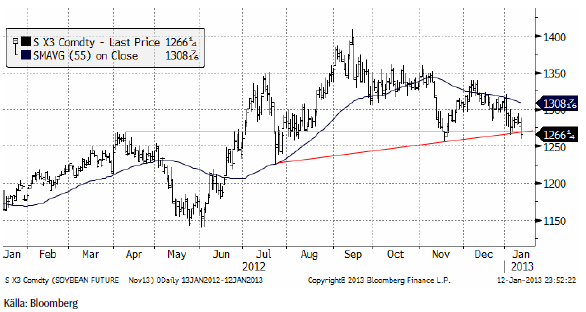
Efter lager- och WASDE-rapporten i fredags föll priset på sojabönor. Lagerrapporten indikerade högre priser, men WASDE-rapportens utbuds- och efterfrågebalans (sammanfattad som utgående lager) innehöll inget som skrämde marknaden. Priset i förhållande till utgående lager visar att priset ligger något ”högt” i förhållande till väntad lagernivå.
Tekniskt gjorde prisfallet i fredags ett en stödlinje bröts, vilket signalerar att ytterligare prisfall kan väntas de närmaste dagarna då säljarna verkar vara mer motiverade än köparna. 1225 cent / bushel på novemberkontraktet kan kanske tas som en första målkurs.
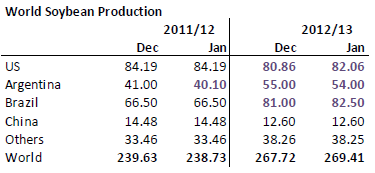
USDA justerade upp sojabönsproduktionen 2012/13 i fredagens WASDE-rapport. Brasilien höjdes, vilket är i linje med lokala prognoser. USA höjdes också, men Argentina sänktes. USDA sänkte även Argentinas uppskattade skörd förra året, vilket då slår på utgående lager för 12/13.
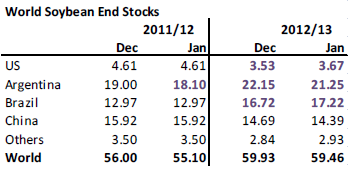
Nedan ser vi USDA:s uppskattning av utgående lager 2011/12 och prognos för 2012/13. Som vi ser resulterade det i en liten sänkning, främst i USA och Argentina (pga sänkt ingående lager, huvudsakligen).
Nedan ser vi förhållandet mellan pris och förväntade utgående lager 2012/13 i termer av dagars konsumtion. På basis av den här bilden ser vi att priset ser ”högt” ut.
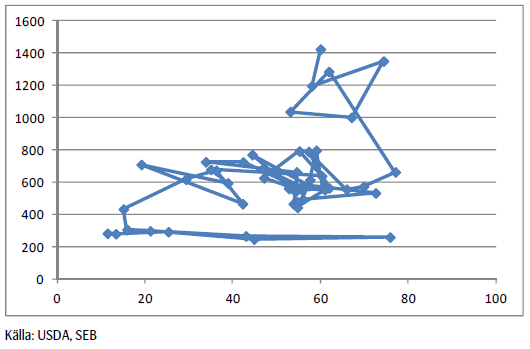
Sammanfattningsvis: Prisfall ner mot 1225 cent på novemberkontraktet ser ut att kunna vara ett riktmärke.
Raps
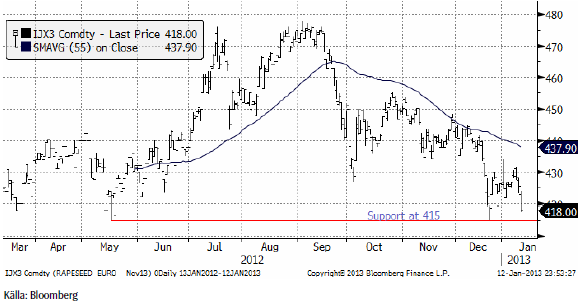
Rapspriset (november 2013) föll i pris i fredags som en följd av prisfallet i sojabönorna. Tekniskt finns en stödnivå på 415 euro per ton. Det är troligt att den ska testas – och kanske brytas på nedsidan – i veckan som kommer.
Gris
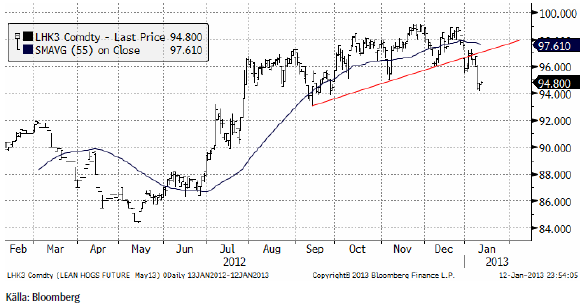
Grispriset (Maj 13), amerikansk Lean Hogs, har brutit en teknisk stödnivå (röd linje i diagrammet nedan). 94 cent per pund var första stödnivån, men antagligen fortsätter priset ner mot 92 cent i första hand.
Mjölk
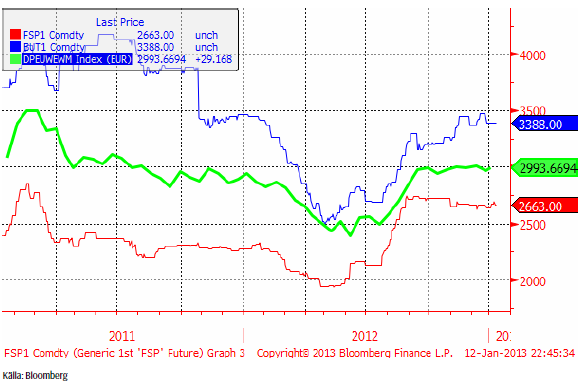
I diagrammet nedan ser vi tre kurvor.Den gröna linjen är priset på skummjölkspulver i euro per ton på Eurex-börsen. Den blå är priset på smör på Eurex börsen. Priserna på Eurex anges i euro per ton.
Slutligen så den gröna linjen. Den visar priset på helmjölkspulver (WMP) FOB Västeuropa. Källan är USDA och priserna uppdateras varannan vecka. Vi ser att WMP-priset legat stabilt det fjärde kvartalet förra året, med en liten nedgång mot slutet av året. 2013 har dock börjat med en liten prisuppgång.
Det börsbaserade priset i svenska kronor beräknas med formeln:
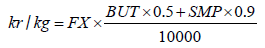
där
BUT = priset på smör i euro per ton
SMP = priset på skummjölkspulver i euro per ton
FX = växelkursen för EURSEK.
SEB erbjuder, som första bank i världen, sina kunder att prissäkra ovanstående pris (marknad) i kronor per kilo med terminskontrakt.
EURSEK
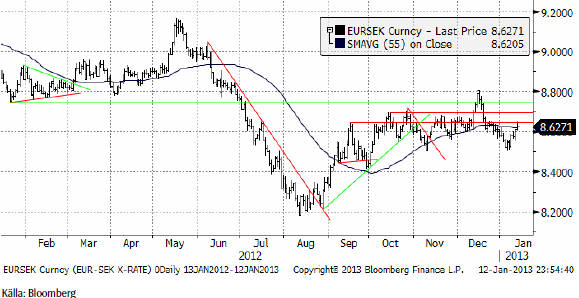
EURSEK stärktes successivt under veckan som gick och nådde upp till de gamla motståndsnivåerna. Det finns inte mycket ny information som ger anledning till att anta annat än att den ”sidledes” rörelse vi sett de senaste månaderna ska fortsätta.
USDSEK
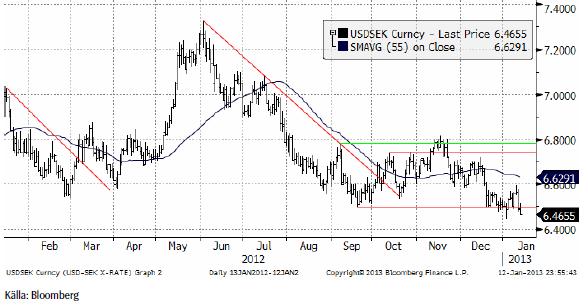
Dollarn föll mot kronan i veckan som gick. Det är fortsatt instabilt finansiellt och politiskt i USA. Stödnivån från botten i september är bruten och det ser ut som om vi ska vänta oss ytterligare dollarförsvagning i veckan som kommer.
[box]SEB Veckobrev Jordbruksprodukter är producerat av SEB Merchant Banking och publiceras i samarbete och med tillstånd på Råvarumarknaden.se[/box]
Disclaimer
The information in this document has been compiled by SEB Merchant Banking, a division within Skandinaviska Enskilda Banken AB (publ) (“SEB”).
Opinions contained in this report represent the bank’s present opinion only and are subject to change without notice. All information contained in this report has been compiled in good faith from sources believed to be reliable. However, no representation or warranty, expressed or implied, is made with respect to the completeness or accuracy of its contents and the information is not to be relied upon as authoritative. Anyone considering taking actions based upon the content of this document is urged to base his or her investment decisions upon such investigations as he or she deems necessary. This document is being provided as information only, and no specific actions are being solicited as a result of it; to the extent permitted by law, no liability whatsoever is accepted for any direct or consequential loss arising from use of this document or its contents.
About SEB
SEB is a public company incorporated in Stockholm, Sweden, with limited liability. It is a participant at major Nordic and other European Regulated Markets and Multilateral Trading Facilities (as well as some non-European equivalent markets) for trading in financial instruments, such as markets operated by NASDAQ OMX, NYSE Euronext, London Stock Exchange, Deutsche Börse, Swiss Exchanges, Turquoise and Chi-X. SEB is authorized and regulated by Finansinspektionen in Sweden; it is authorized and subject to limited regulation by the Financial Services Authority for the conduct of designated investment business in the UK, and is subject to the provisions of relevant regulators in all other jurisdictions where SEB conducts operations. SEB Merchant Banking. All rights reserved.


Brent higher last week and today as fresh attacks by Iran and the Houthis shattered a sense of temporary normality exports from the Persian Gulf. Brent crude traded in a range of $97.06 – 105.92/b and closed the week at $104.72/b. The Brent Dec contract gained $2.47/b on the week. Fresh attacks by Iran on ships in the Gulf and the SoH probably reduced exports of oil through the SoH last week. Exports from the Persian Gulf had reached close to normal levels in the second half of September and into early October. This has led to a large increase in oil on water globally which has helped to ease and reduce November and December prices over the past month. The sense of some kind of normality of exports from the SoH was shattered last week. Fresh attacks by the Houthis on Saudi Arabia added to this and helped to lift prices. It is well known that the US and its allies in the Gulf are running low on defensive rockets. Hard choices over what to defend will increasingly have to be made: Oil infrastructure, military installations, royal palaces, civilian airports or other. The US will also have to decide how many defensive rockets it can provide to its ME allies versus what it needs for its own defenses. Ukraine is at least not getting any of these defensive rockets however much needed for defense against a continuous barrage of Russian attacks on Ukraine. The front-month ICE Gasoil 10ppm (essentially ULSFO Diesel) is down 3.8% this morning (due to Trump’s diesel charade) to $1427/ton ($191/b) which is where it traded last Thursday.
Trump’s diesel charade. The site ”535” now puts the probability for control of the US Congress and Senate following the midterm elections at 99% and 61% respectively. Trump’s war in the Middle East with high or record high gasoline and diesel prices at the pump in the US is largely to blame. Trump’s diesel deal with Russia is clearly Trump trying to shift the blame from his own war in the ME to Ukraine instead. He could of course have placed the blame on Putin and Russia for its war against Ukraine, but no, it is Ukraine who gets the blame and not the least Zelenskyy. Physically it is of course correct that it is Ukraine who is destroying Russian refineries to the point where 45% of Russian refineries are out of operation. The result is that there is too little gasoline for domestic Russian consumption and no diesel, VGO and Jet fuel left over for exports. Russia normally (pre-war 2022) exports some 1.3-1.4 mb/d of diesel products of which a lot used to go to Europe.
Russia/Putin would happily export diesel products to the world, but it can’t because Ukraine is destroying its refineries. Russia implemented export restrictions of diesel already in July this year and the plan was to extend that to early 2027.
The only way that Putin/Russia can start sustained diesel exports, is if Trump is able to discipline and prevent Ukraine from attacking and destroying Russian refineries. Then Russian refineries can be repaired, ramp up, produce more diesel and potentially export what ever is of surplus to the world. Trump has threatened Ukraine that if it doesn’t stop its attacks on Russian refineries, then there will be no more indirect sales of weapons from the US via Europe to Ukraine and the intelligence which US currently is providing to Ukraine will stop.
It is clear that if Russia stops its attacks on Ukraine, then Ukraine is prepared for a energy infrastructure cease-fire.
Trump very well knows that he has himself to blame for the terrible stats for the upcoming midterm elections where Republicans looks set to lose both the Senate and the House. This is a charade for the US public to shift the blame over to something or someone else than himself. His easy choice falls on Ukraine and Zelenskyy for which he has shown little love, affection and support. Nothing of the one way bromance which Trump has shown versus Putin.
At most a three-week holdup in Ukrainian attacks on Russian refineries. Ukraine accepting to play scapegoat. Ukraine’s attacks on Russian refineries and oil infrastructure is a key element of Ukraine fighting back and defending itself against Russia. Ukraine has no choice but to continue its attacks as long as Russia keeps attacking Ukraine. But maybe there can be a three week holdup where Ukraine is forced by the US to step down its attacks on Russian refineries to please Trump until the US midterm elections are behind us. I.e. Ukraine accepting to be the scapegoat for Trump’s missteps in the Middle East for a three week period. Thereafter it will revert back to well thought out strategy of attacking Russian oil and refinery installations.
Trump under increasing pressure as there is increasing probability for Democratic victory in US midterm elections. Desperate times and desperate measures from Trump as a result. More to come

Large increase in oil on water heading for consumers around the world following a sharp increase in exports of oil from the Persian Gulf to close to normal from mid-Sep. Lower exports last week after new hostilities most likely.

Crude, products and natural gas prices in USD/boe. ICE gasoil slightly lower today, but still $195/b

Last week’s oil price action distorted by rolling of the November contract last week. The December Brent crude oil contract rose $4.8/b, or 5% last week. Much of that gain was due to the roll-yield as the November contract rolled off as the M1 contract to be replaced by the Dec-26 contract. The backwardation between the Nov and the Dec contract averaged $6.5/b over the last three days before 1 October and the rolling of contract. The ”gain” over the week was thus not much of a gain at all. If we just look at the M1 contract it instead fell 2% Friday to Friday though that disguises the change in the underlying contract over the week. The Brent M1 contract closed the week at $102.25/b. The announcement of 100 mb of oil from G7 SPR helped to ease prices at the end of last week. Though that effect seems to have faded today.
More barrels from Strategic Petroleum Reserves or really barrels which were supposed to be released previously? Nonetheless, Trump seems to be content and is backing down from diesel export ban. Trump threatened the world, but especially Europe with a US diesel export ban unless Europe agreed to release diesel from strategic reserves. G7 last week decided to release 100 million barrels of oil from strategic reserves. But here the obscurity starts. How much of that will be diesel? ”Substantial release of diesel within 20 days” was the statement. If it happens late in this 20 day period, it would bring us very close to the US midterm elections which of course is what Trump is worried about here. IEA members promised to release 425 mb of oil from strategic reserves of which 125 mb was to be oil products. But a significant portion of that was never really released. The question is thus whether these ”new” 100 mb release will really be new or if the lion’s share of the ”new” 100 mb is really just part of the old 425 not yet fully released. Well, it looks like the promise, irrespectively what it really is, has averted a US diesel export ban for now. And it did also help to ease prices a bit at the end of last week. An effect which looks like it has mostly faded this Monday.
$140/b is the price of crude oil in Europe today. Back to the complete distortion of oil and product prices in time and geography. The Dated Brent ”spot” price averaged $123.3/b last week. But that is really the average Day_10 to Day_20 of the ”daily Dated Brent” forward curve. But since this curve is in very steep backwardation, the real prices for physical oil cargoes at the very front-end of this daily curve sits well above the average of this daily curve. The physical premiums for Oseberg and for Fortis crude takes this steep backwardation into account. The full price average for Oseberg and Fortis last week were thus $142.5/b and $140.2/b. That is way, way higher than both the Dated Brent ”spot” price last week and the average of the Brent futures price, the M1 contract, which averaged $103.2/b last week and is trading at $102.4/b
Extreme prompt tightness may fade or get much worse. The extreme prompt tightness and backwardation we see in the market today is a display of today’s prompt situation and not necessarily a guide for the future. The much more relaxed Brent M1 contract (today December) at $102.4/b is maybe a reflection of an oil market either betting or expecting that today’s problems will be resolved somehow over the coming three months. Or, that the current flow of oil out of the SoH at 17.5 mb/d (close to normal) will be sustained or even increase over time. But we don’t know exactly why the flow of crude, products and LNG out of the SoH has been able to sustain at around 17.5 mb/d since mid-September (it seems). Is it because shippers are better at managing the risk or more willing to take the risk of transiting? Is it because the US military assistance is better? Or is it because Iran is paid by exporters and is allowing exports out through the SoH? It seems plausible that Iran expects the US to attack again after the US midterm elections. If so, then Iran may engage with fresh attacks before that date. Physical crude in Europe today is $140/b, or 2x the ”normal” price of $70/b. But if tightness escalates further, then price of crude in Europe could go to 3x, 4x or even 5x the normal level. Let’s hope that the US is able to keep the SoH ”open” at a rate of 17.5 mb/d and that another 100 mb of oil from G7 helps to shield against that upside risk.
The global oil-stock cushion is getting ”scarily thin”. Looking at the Brent M1 Dec-26 contract, one gets the impression that risks may be fairly contained. Looking at physical spot prices in Europe however of around $140/b, the sense of stress rises substantially. The latter better reflects Amin Nasser, CEO of Saudi Aramco, when he recently said that the cushion capacity of global oil stocks are getting ”scarily thin”.
Some key questions helping to keep the Brent M1 price above $100/b: Will Iran initiate fresh attacks before the US midterm elections? Will the US attack Iran after the elections? Will the US be able to keep the SoH close to open at 17.5 mb/d? Will the Houthis re-attack the Saudi east-west pipeline and ships trying to traverse the Bab-el Mandeb Strait as the Saudi-backed Yemen government tries to retake areas along the Red Sea recently taken by the Houthis? How far will this have to go before China finally decides to step in as a peacemaker in ME negotiations?
ARA Crude oil, diesel and nat gas prices in USD/boe

Physical crude oil premiums for Fortis and Oseberg in the NSea in USD/b premium over the Dated Brent index

Spot crude oil prices at very high levels. The Brent 1M (November) contract yesterday traded between $103.76 – 108.83/b before settling the day at $105.28/b. This morning it is trading up 1.4% to $106.8/b. That is not much of a price given that the ME crisis has been ongoing since 28 February. The Dated Brent spot price however settled yesterday at $123.78/b and averaged $120.6/b last week. Even stronger were the individual North Sea spot crude prices where Johan Sverdrup crude averaged $144/b from 21 to 24 September. And Johan Castberg was said to have traded at a premium of $32/b to the Dated Brent price last week which potentially would have placed it closer to $150/b.
A steady trend higher since $70/b in early July. Crude oil prices have been on a steady trend upwards since they bottomed out at around $70/b in early July following the discharge of some 200 million barrels of crude, products and liquids from the Persian Gulf during a two week MoU window. from 20 June to 7 July when hostilities again resumed.
The oil market today is split apart in time, space and molecules. Financial crude oil prices for November delivery are trading at $106/b (Brent) and $93.3/b (US WTI) and $107/b (Oman). But spot crude oil prices are much higher at $120-150/b as described above. But consumers do not consume crude oil, they consume diesel and gasoline and other products. And diesel prices are closer to $200/b in ARA due to destruction of Russian refineries and locked-in refineries in the Persian Gulf. Oil markets are very stressed with respect to products, but not so stressed with respect to crude oil. But refineries are eager to pay up for crude deliveries right here and now so they can convert that crude to products and make a killing profit. They are not willing to pay up for November crude deliveries in the same way as uncertainties on the Middle East situation is so high. Exorbitantly expensive VLCC freight rates is also driving prices apart. VLCC freight rates are today running at 500,000 to 1,000,000 dollar a day rather than the normal 20,000 a day. This typically adds $10-20/b for crude oil between the point of origin and the point of delivery some 30-50 days out in time when the crude is delivered. This creates a lot of confusion of what really is the price of crude oil these days. Prices are very different in time and space.
Bonds and equity markets are starting to feel the heat. The Middle East crisis is starting to feed risk and pain into financial markets where the US 10-year rate is rising along with crude and product prices with equity market indices starting to pull back in response.
The risk is rising that the ”Trump war” in the Middle East may lead to the ”Trump recession”. A legacy Trump would not likely want to have. Feed-through to financial markets, rising risks for US financial and economic recession, rising risk to Trump’s legacy, declining US stocks of Patriot and THAAD rockets could be forcing mechanisms towards a resolution of the Middle East crisis.
A picture of the future Middle East order is starting to emerge. There seems to be a lot of discussions between different parties going on and a picture of a new Middle East order is starting to emerge. A post Middle East pax Americana order. Where the different countries in the Middle East are taking much more responsibility for the security order in the region. The US provides intelligence and sell weapons to the region but is reducing its military presence. Iran is recognized as a regional power, but not the dominant one and is part of the security order in some ways. Trump can say that he reshaped the Middle East order. Exports of oil restored. The region now paying for its own defense. US soldiers pulled out to a minimum. China part of the diplomatic solution and taking some responsibility for keeping Iran in check.
Time to some kind of ME resolution? Forcing mechanisms: Declining stocks of defensive US rockets + rising crude and product prices + rising economic and financial pain and rising risk to Trump’s legacy. A window of resolution could be November to January maybe. Markets will likely increasingly price in a resolution as the picture of the future security order in the Middle East emerges further.
Crude and diesel prices in USD/b

European M1 refinery margins at record high.





The Trump diesel charade

Viscariagruvan får strategisk status av EU

Miljöpartiet i England slutar vara motståndare till kärnkraft
The price of crude oil in Europe today is $140/b

Kanada vill få fart på oljesanden igen

År 2035 kan datacenter i USA förbruka mer naturgas än Japan och Tyskland tillsammans

Varför det en gång så mäktiga OPEC förlorar inflytande
Kanada vill få fart på oljesanden igen
Oil prices are rising, but a picture of the future ME order may start to emerge
Viscariagruvan får strategisk status av EU
-
 Nyheter3 veckor sedan
År 2035 kan datacenter i USA förbruka mer naturgas än Japan och Tyskland tillsammans
-
 Nyheter4 veckor sedan
Varför det en gång så mäktiga OPEC förlorar inflytande
-
 Nyheter2 veckor sedan
Kanada vill få fart på oljesanden igen
-
Analys2 veckor sedan
Oil prices are rising, but a picture of the future ME order may start to emerge
-
 Nyheter5 dagar sedan
Viscariagruvan får strategisk status av EU
-
 Nyheter1 vecka sedan
Miljöpartiet i England slutar vara motståndare till kärnkraft
-
Analys1 vecka sedan
The price of crude oil in Europe today is $140/b
-
Analys1 dag sedan
The Trump diesel charade