

Analys
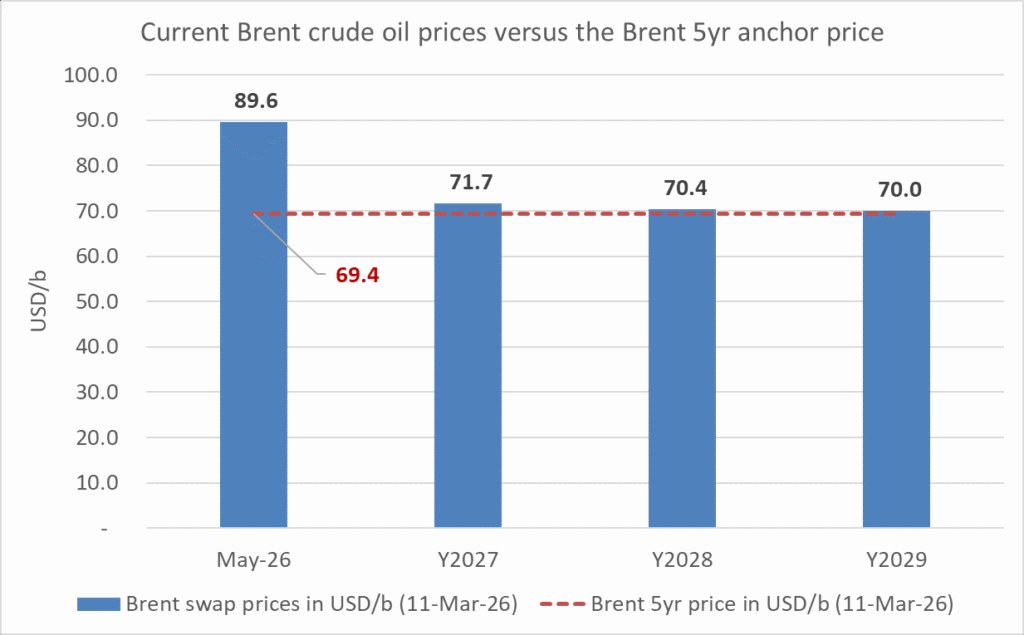
It is like the market believes in magic. That makes Brent 2027 such a bargain


IEA Proposes Largest Ever Oil Release From Strategic Reserves (WSJ). Brent up 3.3%. Doesn’t look like the oil market thinks that ”largest ever” release of strategic reserves will help much against current crisis. Brent up 4% to $91.3/b.

Buy Brent 2027 at close to ”neutral price”. Brent crude for year 2027 is trading at $71.6/b. That is just $3.6/b above the ”neutral price” of $68/b. When the global oil market fluctuates between surplus and deficit, the Brent spot price will swing below or above this ”neutral price” of $68/b. Sometimes way below as in spring of 2020 and sometimes way above.
Brent spot is trading $22/b above the ”neutral price” of $68/b. The Brent 1M price is trading at $90/b this morning and $22/b above the ”neutral price” in an expression of risk, stress and disruption of oil logistics as the Persian Gulf is closed. But the market is pricing Brent Y2027 at $71.6/b and a premium of only $3.6/b above the neutral price. Implicitly assuming that the oil market will be normal in 2027 with normal inventories and normal supply. Everything restored.
If global stocks draws down 500 mb, then $80/b 2027 is the price. More if oil infrastructure damaged. Brent averaged $81/b in 2023/24. Then global visible stocks rose 500 mb in 2025. Mostly east of Suez. Brent then averaged $63/b in 4Q25. If the Strait of Hormuz is closed for 25 days, then global stocks will draw down by 500 mb. Brent should then trade around $80/b just due to the inventory drawdown. Higher if inventories are drawn down more and yet higher if installations of oil production, processing, refining or shipping logistics are damaged. Takes significant time to repair and restore.
When the market now prices Brent 2027 at only $71.2/b it thus assumes that inventories will only draw down by some 250 mb. Ops, we are already there as the Strait of Hormuz now has been closed for 11-12 days. It also assumes that there will be absolutely no lasting damage to oil infrastructure in the Persian Gulf.
Risk that Israel will damage Iranian oil infrastructure. It is increasingly argued that Israel and the US have different strategic goals. The US/Trump wants to end this as quickly as possible. Wants to see oil prices fall quickly back to normal. Israel however probably wants to use this once in a lifetime opportunity to totally destroy and degrade Iran altogether. High or ultrahigh oil price not so important. Leaving Iran with no water, no oil, no money, no economy and very limited capability to rebuild its country (and weapons systems and nuclear facilities) after the war.
Brent 2027 is just one Israeli bomb away from jumping to $80/b or higher. Brent crude calendar 2027 today trading at $71.6/b is just one Israeli bomb (hitting Iranian oil infrastructure) away from trading at $80/b or higher. Global inventories have already suffered 11-12 days of Hormuz closure. I.e. the world has lost 220 – 240 mb of oil stocks. And as stated above, the price of $71.6/b is only $3.6/b above the ”everything is normal price”. What a bargain. Buy it!
Fear is starting to rush through the veins Birol. Looking back at recent events. Fathi Birol (IEA) last week: ”Plenty of oil in the market. No need to release strategic reserves.” Then G7 preparing for release. And now ”IEA Proposes Largest Ever Oil Release From Strategic Reserves (WSJ)”. This shows how the sense of fear is starting to rush through the veins Birol.
Oil price spike forced Trump to the podium. Another is on Monday. Brent spiked to $119.5/b. That forced Trump to jump to the podium reading a statement (quite rare that he reads a pre-written note) of how great everything is going. That all will soon be over. Any issues with the oil market and oil prices will be solved. Trump has the oil markets back. Market believed him and Brent fell sharply. This shows the power of oil. It makes even the most powerful person in the world jump to the podium in an effort to try to talk away the physical problems of the world. It shows that Trump is not in control. Iran declared right after the speech that it is not up to Trump to decide when the war is over. Iran will decide when it is over. Trump might declare victory, pack up and go home. That will however not give any guarantees for the opening of the Strait of Hormuz. That is up to Iran.
Iran has the upper hand. They control the Strait of Hormuz. They control the oil. Trump, Birol and the rest are basically talking about it.
No signs that the world is able to open the Strait of Hormuz by force as promised. We have seen reassurances over the past week that insurance schemes will be set up to cover the war risks so that ships can go through. And that warships will provide safe passage in convoys. Nothing of that so far. It doesn’t take very expensive weapons (Iran has loads of Shahed drones) to shoot at the VLCCs going through. A drone now and then will keep flow of oil through the Strait of Hormuz muted if not fully closed.
Oil for all or oil for no one. “Strait of Hormuz will either be a Strait of peace and prosperity for all,” Ali Larijani, Iran’s top national security official, said in a social media post on Tuesday. “Or it will be a Strait of defeat and suffering for warmongers.”
Brent Y2027 and beyond is such a bargain!

Oil markets remain tight as the Strait of Hormuz (SoH) continues to be constrained. Things could become much tighter if it is fully closed. However, the outlook could change rapidly if flows normalise in early 2027. A large underlying surplus, rebuilding supply and the risk of more volume from OPEC+ could turn today’s tightness into a significantly weaker oil market in 2027-28.
Eventual reopening looks set to bring surplus
The SoH is constrained, not fully closed. Enough crude is escaping, while alternative pipelines, decreased Chinese imports and SPR releases have helped keep Brent at c. USD 90/bbl. Oil products are much tighter. A full reopening of the SoH would flip the market into surplus. We assume SoH flows normalise from early 2027. The market could then face a 4-5m bbl/d surplus before restocking. We forecast Brent at USD 75/bbl in 2027 and USD 70/bbl in 2028.
We expect OPEC+ to opt for more volume once SoH exports normalise
OPEC+ will likely opt for more volume. The UAE has already chosen volume, Iraq wants to expand and Venezuela looks set to exit. There is a clear risk of controlled OPEC+ supply growth, adding to downside risks for 2027-28.
Natural gas market: Winter risk ahead, yet LNG balance to loosen from 2026
Natural gas inventories in Europe are well below normal. The market had hoped for a revival in Persian Gulf LNG exports from Qatar. However, with no signs of any imminent reopening of the SoH, it might be too late for Middle East LNG cargoes to arrive in Europe before the end of winter 2026/27. TTF natural gas winter prices have rallied in response, but that is predominantly a winter risk with prices trading sharply lower after March 2027. Growing global LNG export capacity in the years to come should push prices lower.
Brent crude converging to technical levels. Brent crude has traded in a range of $90-95/b over the past five days. It pulled back 2.4% yesterday to a close of $92.17/b. This morning it is trading close to unchanged at $92.1/b. That is just above the 100dma of $91.9/b and the 50% Fibo level of $92.6/b. The next technical level would be $100/b. Vortexa stated in a report ydy that ”Record crude shortfall building – and market may miss it in summer lull”. If so, then $100/b is maybe where we are heading in the near term. Argus reported however on Friday that CPC Blend exports (Kazakhstan) has increased to 1.8 mb/d from only 0.85 mb/d in the second half of July. This has eased the crude tightness in Europe as it coincides with lower crude processing by European refineries due to maintenance and seasonal turnarounds.
China is standing in the way for US sanctions towards Iran. The US is threatening Iran with economic destruction via sanctions. But China is normally buying 90% of Iran’s crude and is strongly opposed to sanctions arguing that they don’t work. China cannot allow the US to dictate from whom it can buy crude oil or not. Xi Jinping is set to meet Trump in the US in a couple of weeks from now. There is no chance that the US will hit secondary sanctions on Chinese entities dealing in Iranian oil. How to make economic sanctions against Iran work when China is not a part of if is Trump’s big headache.
Natural gas – Winter panic sets in as there is no opening of Hormuz in sight. European natural gas is rallying amid low seasonal nat gas stocks and no reopening of the SoH in sight. European nat gas for December delivery is trading at EUR 67.5/MWh or about $136/boe. That is more than a 50% premium to Brent crude delivered in December. That measure traded in a range of 30% to 40% premium from mid-July to mid-August but has now jumped straight to 50%.
European natural gas inventories are currently at 63% versus a seasonal norm of 80.6%. That is 17.6% lower than 2010-2025 average.
The European nat gas market has stayed relatively calm for a long time in the hope that the Strait of Hormuz would open ”very soon” as Trump insisted all the time. Assuming that stocks ahead of winter could be rebuilt rapidly once the SoH was reopened. Now, however, there is no clarity on a reopening. No one expects it to happen anytime soon. As a result, the European nat gas market has run into a bit of a winter-panic over the past week.
Asian LNG buyers are part of the winter bidding-war. The European nat gas prices are however not set by European nat gas buyers alone. It is set in a cross-bidding for LNG cargoes between Asia and Europe. The fact that nat gas for December delivery has rallied to a 50% premium to Brent crude is probably indicating that Asian buyers are bidding strongly into this rally as well.
There are no strategic reserves for natural gas. The problem with natural gas is that there are no large inventories since gas is difficult and expensive to store. That is why the nat gas market is much more stressed over having lost 20% of seaborn supply normally coming from the SoH.
Dry rivers and low hydroelectric levels adds to Europe’s winter risk. Europe has also gotten into trouble due to the record hot and dry summer. Hydroelectric reservoirs are unusually low ahead of winter while low river levels are holding back nuclear and other thermal power plants from running.
A warm 2026/27 winter would help a lot. But the 2026/27 winter looks set to be warmer than normal according to seasonal forecasts for what they are worth.
European natural gas inventories are significantly below the 2010-2025 average

TTF nat gas for December delivery has jumped to a 53% premium to Brent crude.

Nat gas forward prices versus Brent crude forward prices. Nat gas is about winter risk as there are no strategic reserves (inventories) of natural gas other than commercial stocks.

Brent rose 6% last week as hopes for a reopening faded. Brent crude rose 6% last week as hopes for ”an imminent reopening” of the SoH, as heralded by Trump again and again, faded completely. Brent traded in a range of $81.5 – 90.07/b before closing the week at $88.52/b. That is very close to the average Brent price year to date with Brent 1 month contract having averaged $86.9/b and the Dated Brent spot price having averaged $91.5/b. This morning Brent is trading close to unchanged at $88.6/b
The ceasefire between the US and Iran is today officially over. Trump of course has declared Iran for badly beaten and that the SoH could soon become ”a territory of the United States”. Trump is for sure a great entertainer! Iran’s response: ”The Strait of Hormuz cannot be seized by tweet.”
Economic sanctions isn’t going to change things. The fact is that the US is out of options and low on critical defensive ammunition to the point that it cannot any longer go on attacking Iran. Instead the path forward will be economic sanctions which everyone knows is a very lengthy process with highly uncertain outcome. If Iran doesn’t bow to bombs it will for sure not bow to sanctions. The general thinking and experience is that sanctions do not work. Trump desperately wants to extricate himself from the war with Iran in order to focus on the US midterm elections. But Iran won’t let him.
Netanyahu is not sitting still and bombed Lebanon over the weekend. Strikes have also resumed in Gaza while Israeli settlers are making trouble in the west bank. Trump doesn’t control any of it while Iran is demanding a resolution to these conflicts and end of hostilities. This of course complicates things further for Trump.
Iran and Oman continues to discuss how the SoH is going to be administrated in the future. They agreeing does not imply a reopening though has Iran stated.
For the time being there is enough crude oil in the market preventing crude oil stocks from falling sharply and preventing Brent crude from rallying higher.
Back of the envelope calculations of how the loss of 14 mb/d of crude normally passing through the SoH are currently compensated by different elements.

Helps to explain why Brent hasn’t rallied to $150/b or higher. This table helps to explain why global crude stocks are not falling rapidly and why Brent crude is not rising exponentially as a result.
Two very important elements. What stands out here is the importance of two elements. 1) The escape of oil out of the SoH of maybe as much as 5 mb/d and 2) The Saudi Arabian redirection of 3 mb/d to the Red Sea. Shut these two off and the market is quickly in a significant deficit.
Iran is controlling them both. A powerful threat to Trump’s midterm elections. The big headache for Trump is that Iran directly and indirectly controls them both. For all we know Iran is allowing 5 mb/d to traverse the SoH every day. It probably isn’t all that difficult for Iran to up the game and totally halt the flow at night out of the SoH. Ukraine got better and better at hitting Russian refineries deep inside Russia. Iran will get better at hitting convoys at night trying to sneak out. But maybe Iran isn’t even trying so hard and is just biding its time for when to choke it fully. Iran can also activate the Houthis more aggressively to halt the flow of oil out of the Bab el-Mandeb Strait thus in part also chocking off the Yanbu redirect.
Stay long or buy-on-dips over the coming 2-3 months to the US midterm election. It is very plausible that Iran can fully close of the SoH and and also activate a closure of the Bab el-Mandeb Strait if and when it wants to. Further that it will play with such closures over the coming 2-3 months to the US midterm elections on 3 November. Iran won’t let Trump extricate himself from this war and Iran won’t allow this to be easy sailing for Trump.




Kopparpriset stiger när den fysiska världen gör sig påmind
Tightness today versus risk of surplus tomorrow

Nederländerna flyttar guld från USA och Kanada till London

Ostadigt höstväder kan dämpa de höga elpriserna

Priset på råolja är fel signal att titta på, det är bensin och diesel som visar allvaret
No reopening of SoH anytime soon. Winter could be expensive for oil product consumers

Saskatchewan bygger en av världens största urangruvor, kan stå för en femtedel av den globala produktionen

Pirater från Somalia kapar tankfartyg som fraktat oljeprodukter från Iran

Guldet rör sig i ton, betalningarna rör sig i millisekunder: Vad finansmarknadernas infrastruktur lär oss om digital penningrörelse

Jeffrey Currie – Råvarorna skickar en varningssignal, guld gynnas från två håll
-
Analys4 veckor sedan
No reopening of SoH anytime soon. Winter could be expensive for oil product consumers
-
 Nyheter2 veckor sedan
Saskatchewan bygger en av världens största urangruvor, kan stå för en femtedel av den globala produktionen
-
 Nyheter3 veckor sedan
Pirater från Somalia kapar tankfartyg som fraktat oljeprodukter från Iran
-
 Uncategorized4 veckor sedan
Guldet rör sig i ton, betalningarna rör sig i millisekunder: Vad finansmarknadernas infrastruktur lär oss om digital penningrörelse
-
 Nyheter2 veckor sedan
Jeffrey Currie – Råvarorna skickar en varningssignal, guld gynnas från två håll
-
Analys3 veckor sedan
Stay long or buy-on-dips in the run-up to the US midterm elections on 3 Nov
-

 Nyheter2 veckor sedan
Irland har inlett en debatt om att ta bort förbudet av kärnkraft
-
Analys2 veckor sedan
Oil close to technical levels while EU nat gas is gripped by winter-panic