

Analys
SEB – Råvarukommentarer, 29 oktober 2012

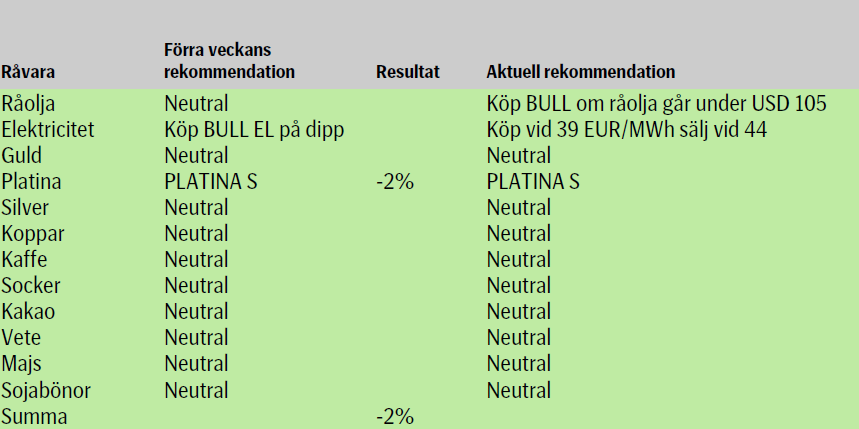
Sammanfattning av rekommendationer
Råolja – Brent
Vi råder att köpa Brent-råolja vid nedgångar till under $105/fat eftersom det verkar osannolikt att priset på råolja kommer att rasa, såvida inte tillväxtprognoserna skrivs ned väsentligt. Vår uppfattning är att oljepriset kommer att fortsätta vara väl understött med tanke på stora geopolitiska risker för tillgången, strama marknader för oljeprodukter, höga incitamentpriser som krävs för att stimulera till tillräckliga investeringar, och behovet av att producentländer försvarar priser för att balansera budgetar. Vi behåller våra prognoser för genomsnittligt pris på Brent-råolja på $110/fat under Q4-12 och $105/fat under H1-13, men väljer att revidera våra uppskattningar för H2-13 och FY-14 från $115/fat till $110/fat. Prognoserna för tillgång förbättras vilket antyder en mindre stram balans på marknaden under de kommande åren, i synnerhet om tillväxten förblir matt.
Medan balansen på råoljemarknaden förblir lös är situationen för mellandestillat annorlunda. Över hela världen är förråden små. Situationen skulle verkligen kunna komma att bli väldigt stram så snart vinterns påfyllnad av bränslelagren accelererar i Europa, som förutsägbart är den stramaste marknaden med tanke på dess fordonspark av dieselbilar. En ännu svårare situation skulle kunna uppstå om temperaturerna på det norra halvklotet blir onormalt låga. Även under normala omständigheter är raffinaderier oförmögna att producera tillräckligt med mellandestillat under uppvärmningssäsongen, vilket gör förråden en nyckelfaktor vid balansering av marknaden. Den långsiktiga strukturella balansen för marknaden för mellandestillat är också oroande eftersom den leder tillväxt avseende efterfrågan. Under tiden har sannolikheten att USA släpper ut strategiska oljereserver uppenbarligen minskat i takt med att politiker inser att höga produktpriser beror på motsvarande strama marknader, och att uttömning av lager av råolja skulle vara ett ineffektivt sätt att pressa ned dem (till skillnad från deras europeiska motparter består amerikanska strategiska oljereserver nästan uteslutande av råolja).
Iran verkar vara alltmer ovilliga att återvända till förhandlingsbordet då försämringen av deras inhemska levnadsstandard fortsätter att accelerera, med potentiell baissebetonade priskonsekvenser om detta stämmer. Den stora frågan kvarstår: finns det en möjlig kompromiss som skulle kunna blidka världsopinionen samtidigt som den gör det möjligt för det iranska ledarskapet att undvika att offentligt förlora anseendet.
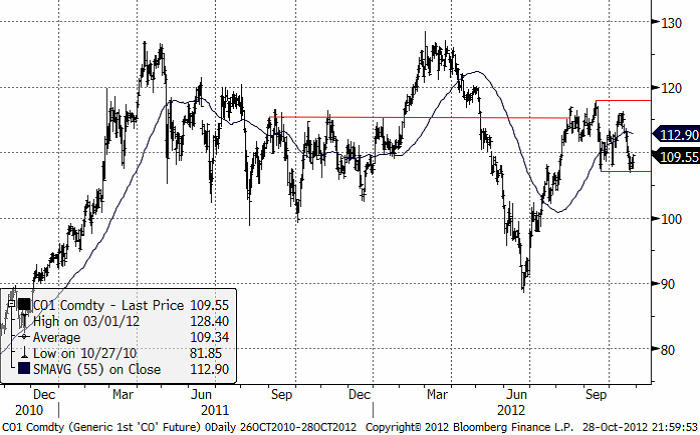
I kursdiagrammet ovan ser vi att 107 dollar har visat sig vara ett förhållandevis starkt stöd. 100 dollar är nästa stöd på nedsidan. Skulle 107 brytas är det inte uteslutet att marknaden vill testa 100 dollar. Det skulle i så fall vara ett köptillfälle, anser vi.
Elektricitet
Vi sänker vår föredragna utgångspunkt för haussepositioner till €39/MWh för Q1-2013-kontraktet på Nord Pool på grund av minskade marginalkostnader för kolkraftproduktion i Tyskland. Vi föredrar att handla kontraktet från haussesidan under november om denna utgångsnivå uppnås. Å andra sidan verkar €43/MWh till €44/MWh vara bra utgångspunkter för de som tar risken att handla vinterkontraktet NELFQ3 från säljsidan med BEAR EL X2 S eller med BEAR EL X4 S.
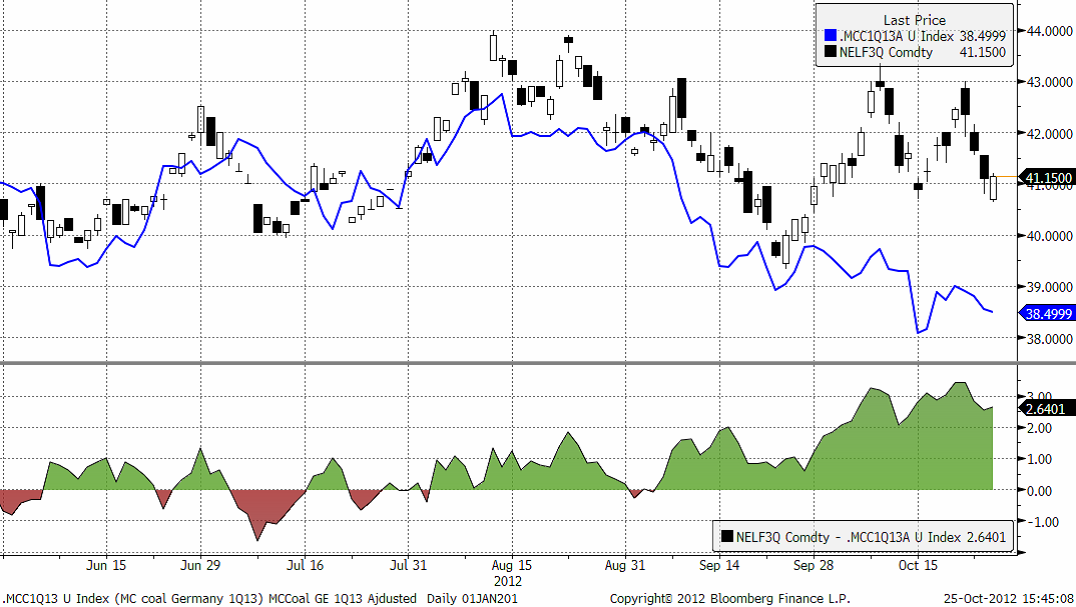
Hittills i oktober har Q1-2013-kontraktet (NELF3Q) på Nord Pool handlats för mellan €40,65/MWh och €43,35/MWh. Under den senaste veckan nådde det så högt som €43/MWh på grund av prognoser för kallare och torrare väderlek samt en studs i marginalkostnaden för kolkraftproduktion (MCCP). I skrivande stund har NELF3Q återigen fallit tillbaka på blöt väderlek och lägre marginalkostnadspriser och har faktiskt handlats på dess lägsta pris hittills i oktober. I och med att prognoser för blöt väderlek har återkommit står det totala vattenöverskottet stadigt på cirka 10 TWh mer än det normala för den här årstiden. Situationen med vattenöverskott naggar kraftkontrakten i frontmånaden i kanten och driver ned dem, samtidigt som NELF3Q-kontraktet fortsätter att upprätthålla riskpremien för vintern. Vi tror att kontraktet troligtvis kommer att bibehålla sin premie i åtminstone en månad innan ett eventuellt vattenöverskott till slut kommer att börja tära på kontraktet när tiden för leverans till snittet av de faktiska spotpriserna närmar sig. Fram till dess kommer de oundvikliga och tillfälliga torra och blöta väderperioderna att lyfta kontraktet tillbaka till nivån på €43/MWh eller högre.
Det som är oroande är att stödet från MCCP har fortsatt att försämras under oktober. Den tekniska bilden för kolpriser är direkt baissebetonad och priserna på koldioxid ser också svaga ut. Spridningen mellan NELF3Q och vårt MCCP-index (.MCC1Q13) har vidgats. Enligt vår uppfattning ökar detta nedåtrisken, vilket betyder att NELF3Q har längre väg att falla om det förlorar en del av sin riskpremie för vintern.
Vi tror fortfarande att det är tillrådligt att handla NELF3Q från haussesidan i november på grund av vintern och risken för brist på kärnkraft framöver. Vi har dock flyttat ned vår föredragna utgångsnivå från €40/MWh till €39/MW tillsammans med det lägre MCCP-indexet (.MCC1Q13). Å andra sidan verkar €43/MWh till €44/WMh vara bra utgångspunkter för de som tar risken att handla vinterkontraktet NELF3Q från säljsidan.
Guld och Silver
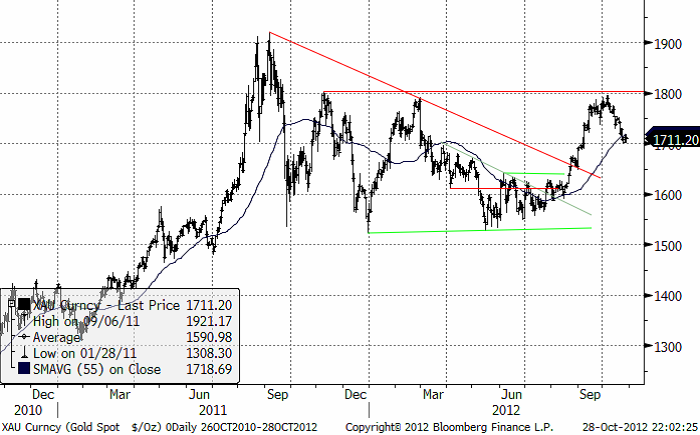
Kommentaren från förra veckan får stå kvar. ”Statistiken som kommer in nu är lite ”för stark” för guldet”. Veckans statistik har fortsatt på samma tema: en stadig, om än lite långsam återhämtning i USA. Frågan är dock om det räcker. centralbanken i USA, och i andra delar av världen för den delen, har tryck på sig att fortsätta med stimulanserna. Det ryktas om förestående ”paket” i Japan. Många ekonomer tror på ett amerikanskt QE4 före årsskiftet.
Nedan ser vi kursdiagrammet för guld.
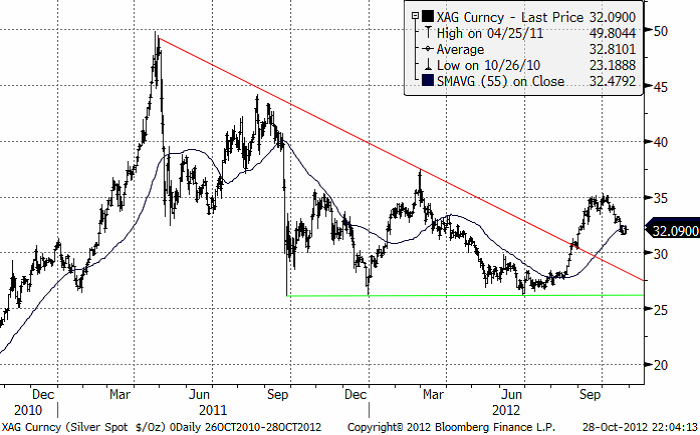
Nedan ser vi kursdiagrammet för silver i dollar per troy ounce. Vi ser att 35 dollar är ett viktigt motstånd och att 30 dollar är ett viktigt stöd. En fortsatt nedgång till 30 dollar skulle vara ett bra köptillfälle. En stopp-loss-order bör då placeras strax under 30 dollar.
Platina
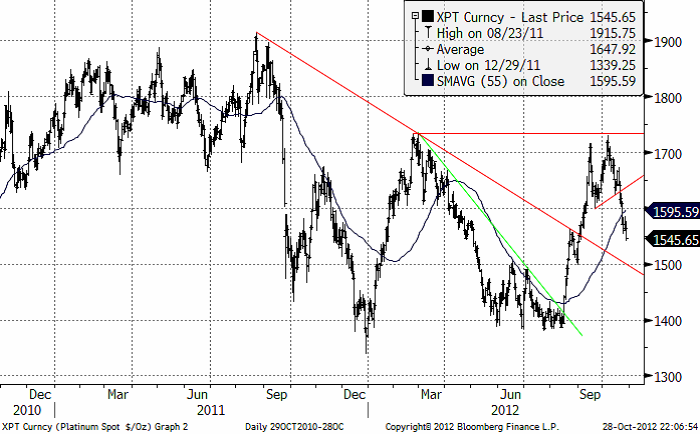
När både guld och basmetaller faller är det svårt för Platinametallerna att hålla emot. Proppen gick ur och vi såg ett kraftigt fall för både Platina och Palladium under veckan. Utbudsfaktorerna (kopplade till problemen i Sydafrika) hjälper inte när investerarkollektivet säljer. Londonnoteringen är ner ca 5 % i veckan till $1550/oz. Kortsiktigt finns risk för ytterligare fall. Med den tekniska analysen som vägledning bör marknaden hitta en bra stödnivå kring $1500. Kursen ligger nu just ovanför den konsolidering marknaden gjorde mellan 1500 och 1560 vid månadsskiftet augusti-september, innan marknaden bröt den nedåtgående trendlinjen. Det skulle inte förvåna om kursfallet bromsas upp, och kanske rent av vänder uppåt efter viss sidledes rörelse på de här nivåerna.
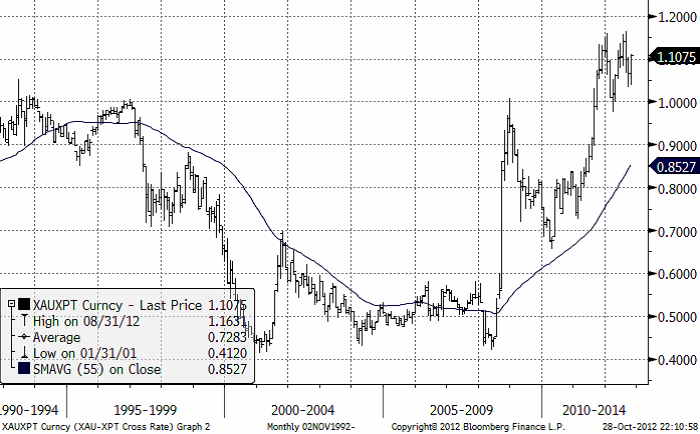
Nedan ser vi priset på guld dividerat med priset på platina. Platina har blivit billigare i förhållande till guld den senaste veckan. Vi anser att detta är ett bra argument för att sälja guld och köpa platina, allt annat lika, eller att köpa platina enbart.
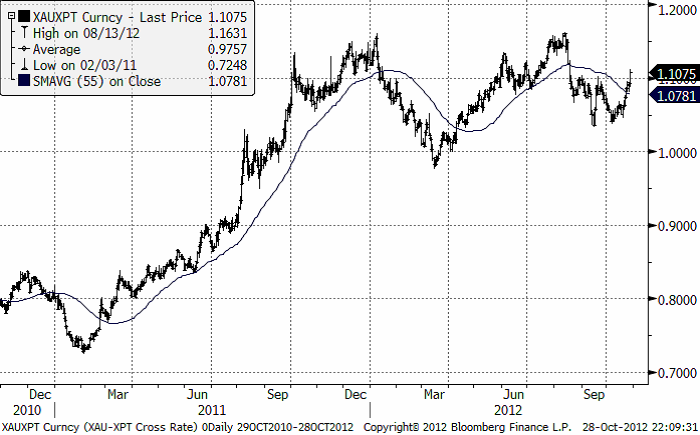
Nedan ser vi kvoten mellan guld och platina för de senaste 20 åren. Vi ser att platina är exceptionellt dyrt i förhållande till guld ur ett historiskt perspektiv. Och vi bör komma ihåg att priser på råvaror på lång sikt bestäms av produktionskostnad. Medan platinagruvorna i Sydafrika inte går med vinst nu, är lönsamheten god för guldgruvorna i världen. På lång sikt talar detta för att platina är en bättre placering än vad guld är.
Koppar
Det negativa stämningsläget från LME-veckan tog överhanden för basmetallerna. Priserna har konstant fallit, inga direkta ras, men metallerna har sakta men säkert tuggat sig ner under veckan. Prisuppgången efter stimulansrundan i september är nu i de flesta fall nästa helt utraderad. Om priserna överreagerade på de kortsiktigt realekonomiska effekterna av penningstimulanserna, så känns det som en överreaktion på nedsidan nu istället. Det finns flera tecken på en makroekonomisk förbättring. Igår fredag redovisades amerikansk BNP för Q3 som kom in bättre än väntat och visar på en uppgång från 2:a kvartalet från 1,3 till 2,0 % i årstakt. Det går långsamt men åt rätt håll. Även i Kina ser det ut att bottna ur. Industriproduktionen ökar och inflationen är låg. Marknadens oro gäller inte beslutade infrastrukturinvesteringar, utan de lokala myndigheternas brist på finansiering. Ledningsbytet i Kina inger förhoppningar, men det återstår att se vad de kommer att presentera, och det kan dröja till installationen av den nya ledningen i början av nästa år. Metallimporten ökade i september, vilket är ett gott tecken (se nedan).
Koppar
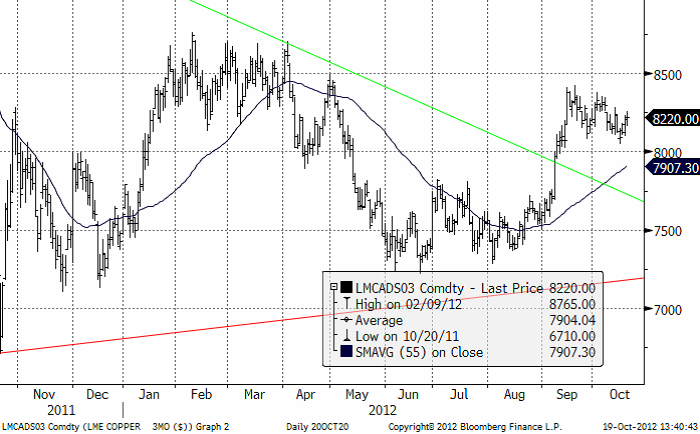
Priset föll ca 2 % i veckan, från $8000 ned till ca 7800 för 3 månaders koppar på LME. De innebär att vi är tillbaka vid nivåerna i början av september. Kinas import av koppar kom in på fyramånadershögsta i september till ca 394 tton, upp från augustis 355 tton, eller ca 11 %. Under årets nio första månader har importen ökat med 32 % jämfört med förra året. Det ska inte glömmas bort att Kina har en fortsatt stor aptit på metallen. Kommentarer från Nexans, världens nästa största kabeltillverkare i veckan, noterade att substitutionseffekten mellan koppar och aluminium (koppar 4 ggr dyrare) i kablar än så länge är begränsad, och särskilt i Kina där kopparbaserad kabel är klart favoriserad. Vi föredrar att betrakta koppar som en köpvärdmetall. Kortsiktigt har vi den senaste veckan hållit oss neutrala men grundinställningen är att hitta köptillfällen.
För spannmål och övriga jordbruksprodukter hänvisas till förra veckans nyhetsbrev om Jordbruksprodukter.
[box]SEB Veckobrev Veckans råvarukommentar är producerat av SEB Merchant Banking och publiceras i samarbete och med tillstånd på Råvarumarknaden.se[/box]
Disclaimer
The information in this document has been compiled by SEB Merchant Banking, a division within Skandinaviska Enskilda Banken AB (publ) (“SEB”).
Opinions contained in this report represent the bank’s present opinion only and are subject to change without notice. All information contained in this report has been compiled in good faith from sources believed to be reliable. However, no representation or warranty, expressed or implied, is made with respect to the completeness or accuracy of its contents and the information is not to be relied upon as authoritative. Anyone considering taking actions based upon the content of this document is urged to base his or her investment decisions upon such investigations as he or she deems necessary. This document is being provided as information only, and no specific actions are being solicited as a result of it; to the extent permitted by law, no liability whatsoever is accepted for any direct or consequential loss arising from use of this document or its contents.
About SEB
SEB is a public company incorporated in Stockholm, Sweden, with limited liability. It is a participant at major Nordic and other European Regulated Markets and Multilateral Trading Facilities (as well as some non-European equivalent markets) for trading in financial instruments, such as markets operated by NASDAQ OMX, NYSE Euronext, London Stock Exchange, Deutsche Börse, Swiss Exchanges, Turquoise and Chi-X. SEB is authorized and regulated by Finansinspektionen in Sweden; it is authorized and subject to limited regulation by the Financial Services Authority for the conduct of designated investment business in the UK, and is subject to the provisions of relevant regulators in all other jurisdictions where SEB conducts operations. SEB Merchant Banking. All rights reserved.


Oil markets remain tight as the Strait of Hormuz (SoH) continues to be constrained. Things could become much tighter if it is fully closed. However, the outlook could change rapidly if flows normalise in early 2027. A large underlying surplus, rebuilding supply and the risk of more volume from OPEC+ could turn today’s tightness into a significantly weaker oil market in 2027-28.

Eventual reopening looks set to bring surplus
The SoH is constrained, not fully closed. Enough crude is escaping, while alternative pipelines, decreased Chinese imports and SPR releases have helped keep Brent at c. USD 90/bbl. Oil products are much tighter. A full reopening of the SoH would flip the market into surplus. We assume SoH flows normalise from early 2027. The market could then face a 4-5m bbl/d surplus before restocking. We forecast Brent at USD 75/bbl in 2027 and USD 70/bbl in 2028.
We expect OPEC+ to opt for more volume once SoH exports normalise
OPEC+ will likely opt for more volume. The UAE has already chosen volume, Iraq wants to expand and Venezuela looks set to exit. There is a clear risk of controlled OPEC+ supply growth, adding to downside risks for 2027-28.
Natural gas market: Winter risk ahead, yet LNG balance to loosen from 2026
Natural gas inventories in Europe are well below normal. The market had hoped for a revival in Persian Gulf LNG exports from Qatar. However, with no signs of any imminent reopening of the SoH, it might be too late for Middle East LNG cargoes to arrive in Europe before the end of winter 2026/27. TTF natural gas winter prices have rallied in response, but that is predominantly a winter risk with prices trading sharply lower after March 2027. Growing global LNG export capacity in the years to come should push prices lower.
Brent crude converging to technical levels. Brent crude has traded in a range of $90-95/b over the past five days. It pulled back 2.4% yesterday to a close of $92.17/b. This morning it is trading close to unchanged at $92.1/b. That is just above the 100dma of $91.9/b and the 50% Fibo level of $92.6/b. The next technical level would be $100/b. Vortexa stated in a report ydy that ”Record crude shortfall building – and market may miss it in summer lull”. If so, then $100/b is maybe where we are heading in the near term. Argus reported however on Friday that CPC Blend exports (Kazakhstan) has increased to 1.8 mb/d from only 0.85 mb/d in the second half of July. This has eased the crude tightness in Europe as it coincides with lower crude processing by European refineries due to maintenance and seasonal turnarounds.
China is standing in the way for US sanctions towards Iran. The US is threatening Iran with economic destruction via sanctions. But China is normally buying 90% of Iran’s crude and is strongly opposed to sanctions arguing that they don’t work. China cannot allow the US to dictate from whom it can buy crude oil or not. Xi Jinping is set to meet Trump in the US in a couple of weeks from now. There is no chance that the US will hit secondary sanctions on Chinese entities dealing in Iranian oil. How to make economic sanctions against Iran work when China is not a part of if is Trump’s big headache.
Natural gas – Winter panic sets in as there is no opening of Hormuz in sight. European natural gas is rallying amid low seasonal nat gas stocks and no reopening of the SoH in sight. European nat gas for December delivery is trading at EUR 67.5/MWh or about $136/boe. That is more than a 50% premium to Brent crude delivered in December. That measure traded in a range of 30% to 40% premium from mid-July to mid-August but has now jumped straight to 50%.
European natural gas inventories are currently at 63% versus a seasonal norm of 80.6%. That is 17.6% lower than 2010-2025 average.
The European nat gas market has stayed relatively calm for a long time in the hope that the Strait of Hormuz would open ”very soon” as Trump insisted all the time. Assuming that stocks ahead of winter could be rebuilt rapidly once the SoH was reopened. Now, however, there is no clarity on a reopening. No one expects it to happen anytime soon. As a result, the European nat gas market has run into a bit of a winter-panic over the past week.
Asian LNG buyers are part of the winter bidding-war. The European nat gas prices are however not set by European nat gas buyers alone. It is set in a cross-bidding for LNG cargoes between Asia and Europe. The fact that nat gas for December delivery has rallied to a 50% premium to Brent crude is probably indicating that Asian buyers are bidding strongly into this rally as well.
There are no strategic reserves for natural gas. The problem with natural gas is that there are no large inventories since gas is difficult and expensive to store. That is why the nat gas market is much more stressed over having lost 20% of seaborn supply normally coming from the SoH.
Dry rivers and low hydroelectric levels adds to Europe’s winter risk. Europe has also gotten into trouble due to the record hot and dry summer. Hydroelectric reservoirs are unusually low ahead of winter while low river levels are holding back nuclear and other thermal power plants from running.
A warm 2026/27 winter would help a lot. But the 2026/27 winter looks set to be warmer than normal according to seasonal forecasts for what they are worth.
European natural gas inventories are significantly below the 2010-2025 average

TTF nat gas for December delivery has jumped to a 53% premium to Brent crude.

Nat gas forward prices versus Brent crude forward prices. Nat gas is about winter risk as there are no strategic reserves (inventories) of natural gas other than commercial stocks.

Brent rose 6% last week as hopes for a reopening faded. Brent crude rose 6% last week as hopes for ”an imminent reopening” of the SoH, as heralded by Trump again and again, faded completely. Brent traded in a range of $81.5 – 90.07/b before closing the week at $88.52/b. That is very close to the average Brent price year to date with Brent 1 month contract having averaged $86.9/b and the Dated Brent spot price having averaged $91.5/b. This morning Brent is trading close to unchanged at $88.6/b
The ceasefire between the US and Iran is today officially over. Trump of course has declared Iran for badly beaten and that the SoH could soon become ”a territory of the United States”. Trump is for sure a great entertainer! Iran’s response: ”The Strait of Hormuz cannot be seized by tweet.”
Economic sanctions isn’t going to change things. The fact is that the US is out of options and low on critical defensive ammunition to the point that it cannot any longer go on attacking Iran. Instead the path forward will be economic sanctions which everyone knows is a very lengthy process with highly uncertain outcome. If Iran doesn’t bow to bombs it will for sure not bow to sanctions. The general thinking and experience is that sanctions do not work. Trump desperately wants to extricate himself from the war with Iran in order to focus on the US midterm elections. But Iran won’t let him.
Netanyahu is not sitting still and bombed Lebanon over the weekend. Strikes have also resumed in Gaza while Israeli settlers are making trouble in the west bank. Trump doesn’t control any of it while Iran is demanding a resolution to these conflicts and end of hostilities. This of course complicates things further for Trump.
Iran and Oman continues to discuss how the SoH is going to be administrated in the future. They agreeing does not imply a reopening though has Iran stated.
For the time being there is enough crude oil in the market preventing crude oil stocks from falling sharply and preventing Brent crude from rallying higher.
Back of the envelope calculations of how the loss of 14 mb/d of crude normally passing through the SoH are currently compensated by different elements.

Helps to explain why Brent hasn’t rallied to $150/b or higher. This table helps to explain why global crude stocks are not falling rapidly and why Brent crude is not rising exponentially as a result.
Two very important elements. What stands out here is the importance of two elements. 1) The escape of oil out of the SoH of maybe as much as 5 mb/d and 2) The Saudi Arabian redirection of 3 mb/d to the Red Sea. Shut these two off and the market is quickly in a significant deficit.
Iran is controlling them both. A powerful threat to Trump’s midterm elections. The big headache for Trump is that Iran directly and indirectly controls them both. For all we know Iran is allowing 5 mb/d to traverse the SoH every day. It probably isn’t all that difficult for Iran to up the game and totally halt the flow at night out of the SoH. Ukraine got better and better at hitting Russian refineries deep inside Russia. Iran will get better at hitting convoys at night trying to sneak out. But maybe Iran isn’t even trying so hard and is just biding its time for when to choke it fully. Iran can also activate the Houthis more aggressively to halt the flow of oil out of the Bab el-Mandeb Strait thus in part also chocking off the Yanbu redirect.
Stay long or buy-on-dips over the coming 2-3 months to the US midterm election. It is very plausible that Iran can fully close of the SoH and and also activate a closure of the Bab el-Mandeb Strait if and when it wants to. Further that it will play with such closures over the coming 2-3 months to the US midterm elections on 3 November. Iran won’t let Trump extricate himself from this war and Iran won’t allow this to be easy sailing for Trump.




Tightness today versus risk of surplus tomorrow

Nederländerna flyttar guld från USA och Kanada till London

Ostadigt höstväder kan dämpa de höga elpriserna

Priset på råolja är fel signal att titta på, det är bensin och diesel som visar allvaret
Oil close to technical levels while EU nat gas is gripped by winter-panic
No reopening of SoH anytime soon. Winter could be expensive for oil product consumers

Guldet rör sig i ton, betalningarna rör sig i millisekunder: Vad finansmarknadernas infrastruktur lär oss om digital penningrörelse

Pirater från Somalia kapar tankfartyg som fraktat oljeprodukter från Iran

Saskatchewan bygger en av världens största urangruvor, kan stå för en femtedel av den globala produktionen
Stay long or buy-on-dips in the run-up to the US midterm elections on 3 Nov
-
Analys4 veckor sedan
No reopening of SoH anytime soon. Winter could be expensive for oil product consumers
-
 Uncategorized4 veckor sedan
Guldet rör sig i ton, betalningarna rör sig i millisekunder: Vad finansmarknadernas infrastruktur lär oss om digital penningrörelse
-
 Nyheter2 veckor sedan
Pirater från Somalia kapar tankfartyg som fraktat oljeprodukter från Iran
-
 Nyheter2 veckor sedan
Saskatchewan bygger en av världens största urangruvor, kan stå för en femtedel av den globala produktionen
-
Analys3 veckor sedan
Stay long or buy-on-dips in the run-up to the US midterm elections on 3 Nov
-

 Nyheter2 veckor sedan
Jeffrey Currie – Råvarorna skickar en varningssignal, guld gynnas från två håll
-

 Nyheter2 veckor sedan
Irland har inlett en debatt om att ta bort förbudet av kärnkraft
-
Analys2 veckor sedan
Oil close to technical levels while EU nat gas is gripped by winter-panic