
Analys
SEB Jordbruksprodukter, 25 juni 2013

 Odlingsväder
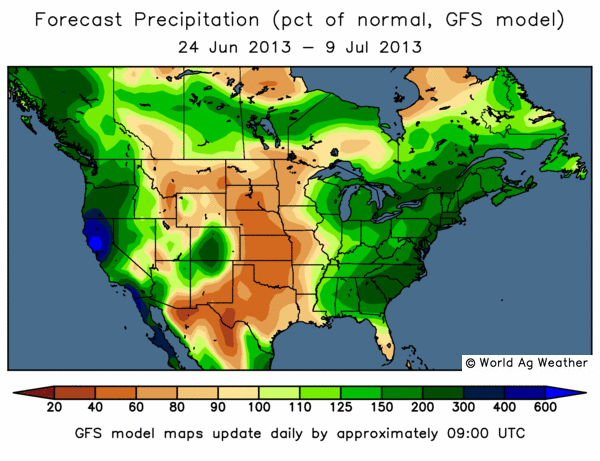
GFS-modellens prognos för de kommande två veckorna visar på ordentlig nederbörd längs väst- och östkusterna i USA och i södra Kanada. GFS-modellen (Global Forecast System) används av de amerikanska vädercentralerna för att göra globala väderleksprognoser. Kalifornien har varit torrt i ungefär tio år, men får nu ordentligt med nederbörd. Däremot fortsätter klassiska vete-områden i USA att vara torrare än normalt.
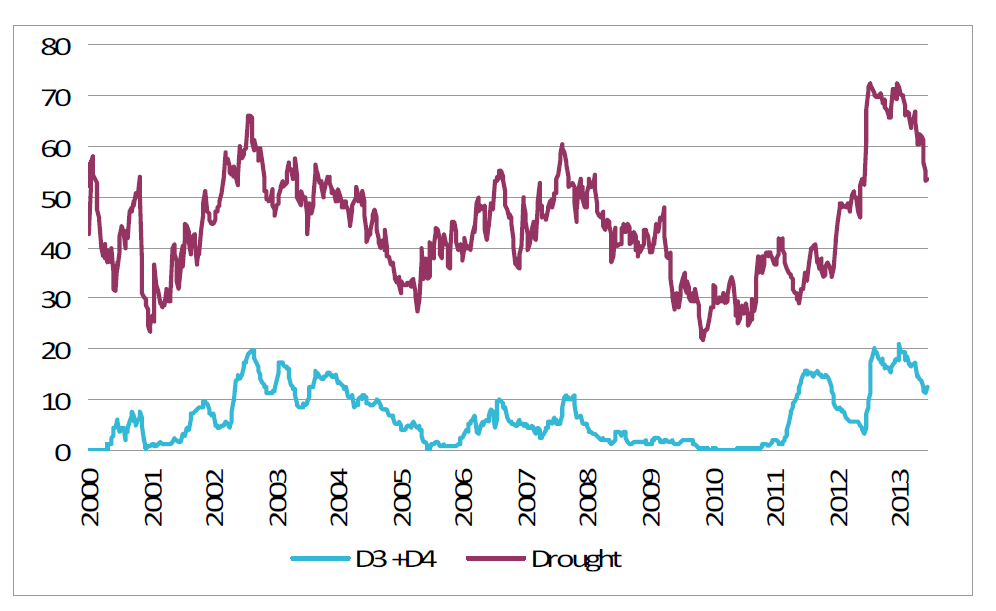
Som vi ser i nedanstående uppdaterade diagram över hur många procent av USA som är drabbat av torka, ser vi att andelen visserligen fallit snabbt, men att det allt jämt är mycket torrare än normalt.
Nedan ser vi en prognoskarta för norra Sydamerika. Vi ser att det nederbördsmönster Brasilien haft tidigare väntas fortsätta. São Paulo-staten får dock nu upp till sex gånger den normala nederbörden. I SP odlas nuförtiden mest sockerrör, då kaffet trängts undan.
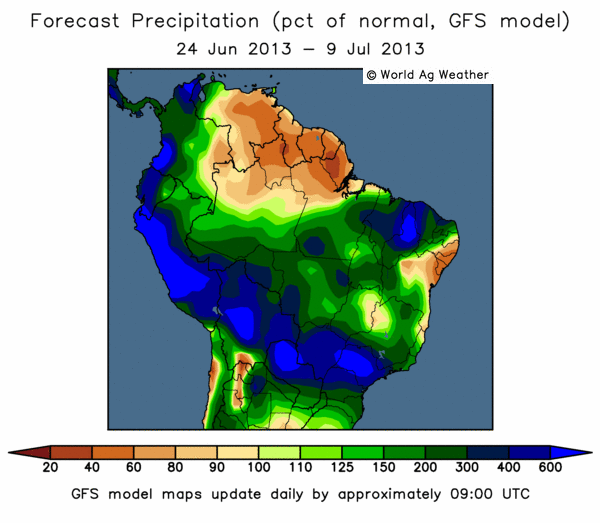
Argentina fortsätter dock att få 60-80% av normal nederbörd.
Indiens monsun har börjat rekordtidigt och täcker hela landet med nederbörd.
Vete
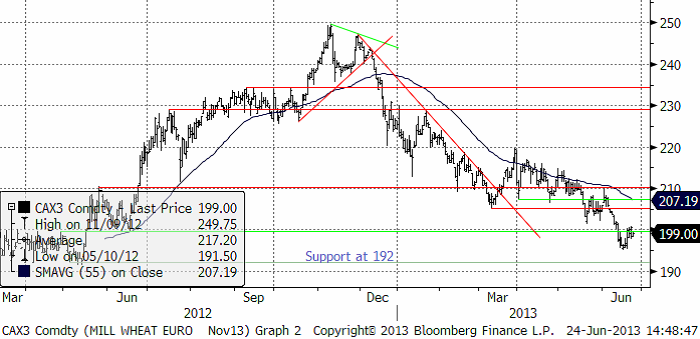
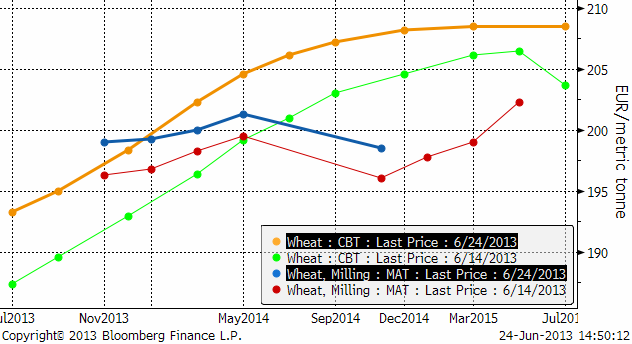
Nyheten att Kina köpt 200 kt vete från Frankrike fick prisfallet på Matifs novembertermin att stanna upp. GASC meddelade att de kommer att bjuda in till en tender före 30 juni. De har varit borta från marknaden sedan i februari. Vi betraktar rekylen upp mot 200 euro som just en rekyl mot trenden och att prisfallet fortsätter.
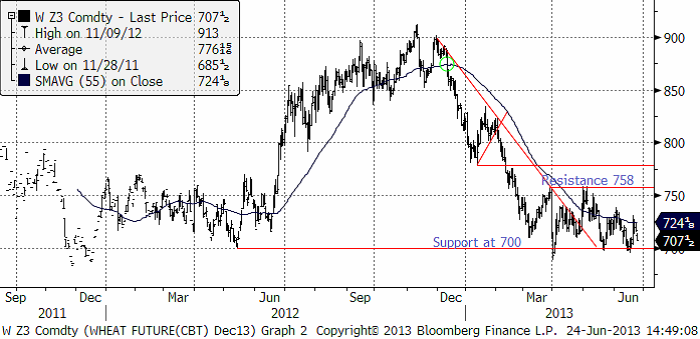
Decemberkontraktet på CBOT har funnit stöd på 700 cent och priset har inte velat gå under den nivån.
Nedan ser vi förändringen i terminskurvorna från fredagen för drygt en vecka sedan, till måndag.
Vädret i Europa är huvudsakligen gynnsamt för produktionen av vete.
Coceral, den europeiska branschföreningen för spannmåls- och oljeväxthandlare, justerar upp sitt estimat för EU-28:s veteproduktion 2013/14 till 130.7 mt, vilket är en ökning från den tidigare prognosen i mars på 127.8 mt och från förra årets 125.4 mt. Revideringen kommer från såväl ökad areal som ökad avkastning. Även estimatet för EU-28:s produktion av korn förväntas öka, trots lägre areal än förra året men på indikationer att avkastningen återhämtar sig i år. Den totala produktionen av korn förväntas uppgå till 56.3 mt, en ökning från det tidigare estimatet på 54.8 mt och förra årets 54.4 mt. Produktionen av majs förväntas uppgå till 66.2 mt, en ökning med 9 mt jämfört med förra året.
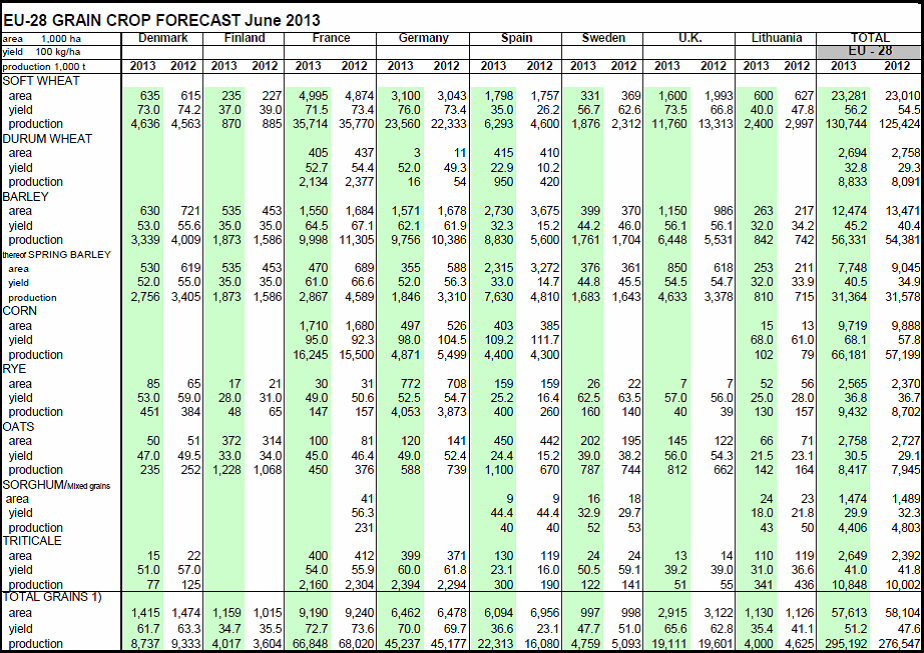
EU Kommissionens MARS-enhet gjorde även de en marginell justering uppåt i sin senaste rapport gällande den genomsnittliga avkastningen för vete. För majs och korn gjordes också justeringar uppåt medan avkastningen för raps justeras marginellt nedåt. Rapporteringsperioden har präglats av skarpa väderkontraster i hela Europa, där nederbörd och kalla temperaturer har hämmat grödornas utveckling stora delar av Centraleuropa. Däremot har väderförhållandena varit gynnsamma i Rumänien, Ungern och framförallt i Spanien där en utmärkt säsong ökar estimatet för avkastningen av vårkorn i EU-27. Mest utmärkande för perioden har dock varit de skyfall i Centraleuropa, som ledde till stora översvämningar i närheten av floder och ökad markfuktighet till kritiska nivåer, vilket ökar risken för skadedjur och begränsar grödornas utveckling.
Prognosen för hektarskörden avseende vete inom EU-27 lämnades i stort sett oförändrad på 5.55 t/ha från förra månadens 5.54 t/ha, vilket fortfarande är en ökning med 2.3% jämfört med förra året men strax under det femåriga genomsnittet på 5.63 t/ha. Detta som en följd av en betydande uppjustering av hektarskörden i Spanien, Rumänien och Ungern, som kompenserar för nedjusteringar i Tyskland, Slovakien och Tjeckien. Estimatet för Storbritannien fortsätter att justeras ner, den här gången från 7.68 t/ha till 7.63 t/ha. Grödorna har blivit hårt drabbade av förra årets rekordregn, som inte bara påverkade förra årets skörd utan även sådden av årets grödor.
Rapporten från USDA på fredag handlar mest om majs och sojabönor. Vetemarknaden kommer dock att ta intryck av situationen för majs.
Majs
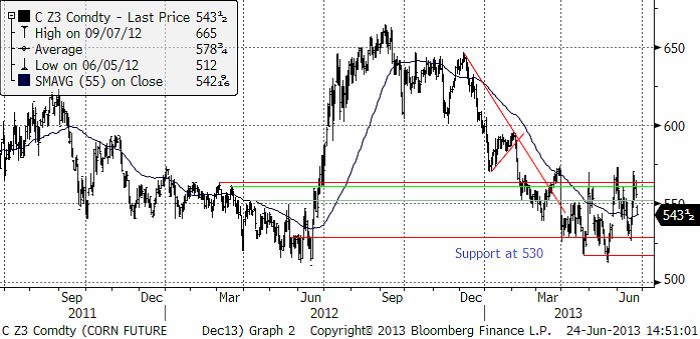
Majspriset (december 2013) har liksom vetet på Chicago funnit stöd på förra årets bottennivåer med 530 cent som den huvudsakliga bottennivån. Marknaden har visat en tendens att försöka stiga de senaste månaderna. Vi har noterat högre toppar och lägre bottnar i de senaste månadernas handel. Helhetsbilden ser dock ut som en rekyl efter den stora prisnedgången från 650 cent / bu. Om det handlar om det, kan nästa prisrörelse bli nedåt, mot 400 cent.
EU-Kommissionens MARS-enhet reviderade i sin senaste rapport upp hektarskörden avseende majs inom EU-27, från förra månadens 6.87 t/ha till 7.13 t/ha. På årsbasis är det en ökning med 16.3% i förhållande till förra årets 6.13. Det är även högre än det femåriga genomsnittet på 7.01 t/ha. Förklaringen är de väsentligt förbättrade utsikterna för Rumänien och Ungern. Sådden av majs i norra Italien blev kraftigt försenad och låga temperaturer i kombination med kraftig nederbörd gav grödorna en dålig start på säsongen. Väderförhållandena under den kommande månaden kommer att vara avgörande för avkastningen.
Brasilianska Safras prognosticerar att Brasiliens majsskörd hamnar på 82.7 mt. USDA estimerade i den senaste WASDE-rapporten en skörd på 77 mt (en höjning från 76 mt i maj-rapporten). USDA estimerar också att skörden i Brasilien nästa år (2013/14) blir 72 mt. Efter det fall i den brasilianska valutan de senaste månaderna finns dock anledning att tro att produktionen kan bli större än 72 mt, eftersom priset i Brasilien automatiskt har stigit med valutans fall. Se nedanstående diagram, som visar decemberkontraktet på CME uttryckt i BRL / bushel.
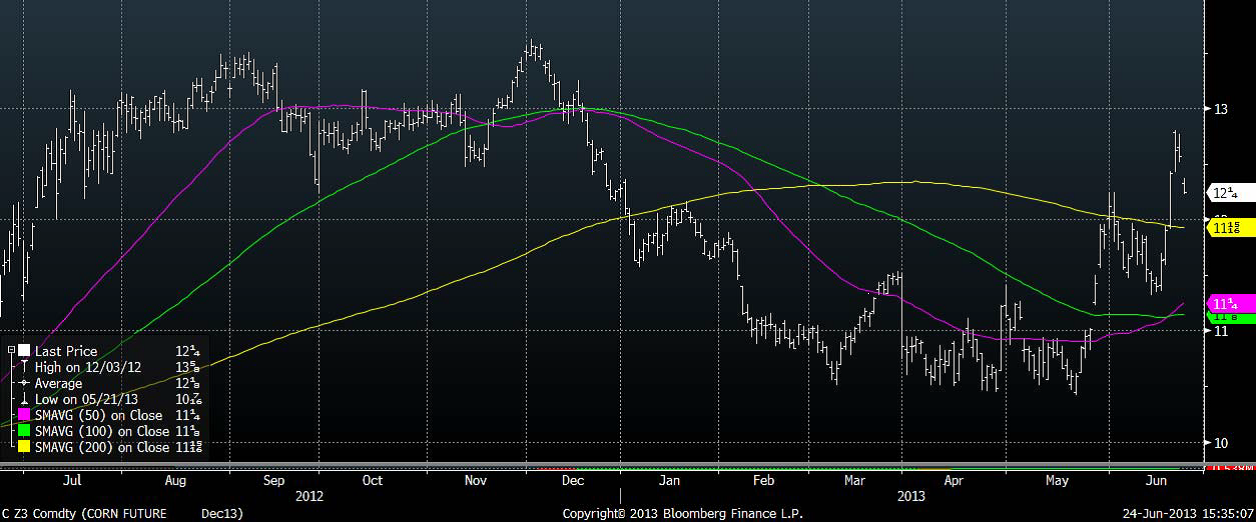
Slutsatsen är att vi behåller vår säljrekommendation på majs.
Sojabönor
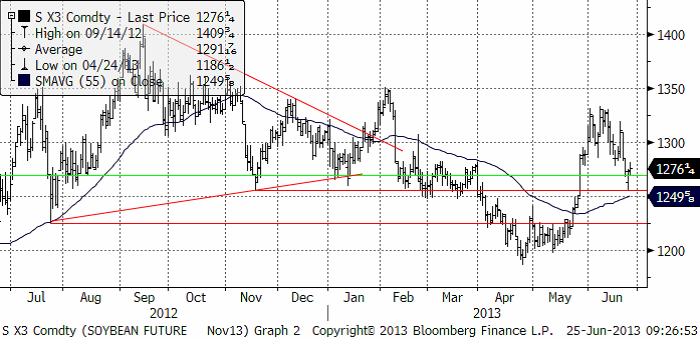
Priset på novemberkontraktet på sojabönor har rekylerat ner till stödet på 1250 cent. Teknisk analys säger egentligen ”köp”. Nästan all fundamental information säger sälj. Vi har övervägt om vi skulle gå över till åtminstone ”neutral” rekommendation, men väljer på grund av följande faktorer att behålla säljrekommendationen: 1. USDA förutspår väsentligt högre lager, 2. Brasiliens valuta har fallit kraftigt vilket torde öka produktionen i landet, 3. Kinas ekonomi bromsar in ännu mer enligt PMI. 4. Stigande obligationsräntor efter FED:s besked om ett slut på QE dämpar konsumtionen av dyrare mat.
Sådden av sojabönor hade i måndags förra veckan nått till 85% färdigt. Det ska jämföras med 98% samma vecka förra året och 91% som femårigt medelvärde. Däremot är sojabönorna i utmärkt skick. 64% är i good eller excellent kondition. Samma tid förra året var 56% i samma klass.
På fredag publicerar USDA statistik på sådd areal och lager. Det spekuleras i att den sena sådden har minskat arealen, men den sena sådden kan också ha minskat majsarealen och ökat sojaarealen. Marknaden förväntar sig faktiskt att sojaarealen har ökat. Den förväntar sig också att exportsiffrorna har varit för höga och att lagren därmed är större än man tidigare trott. Detta skulle kunna få priset att falla ner mot 10 dollar per bushel, resonerar man.
Den brasilianska valutans fall får liksom för majs, förmodligen konsekvenser för produktionen. Ett högre pris leder till högre produktion, allt annat lika. Nedan ser vi priset på sojabönor (november kontraktet) omräknat till brasilianska reais (BRL):
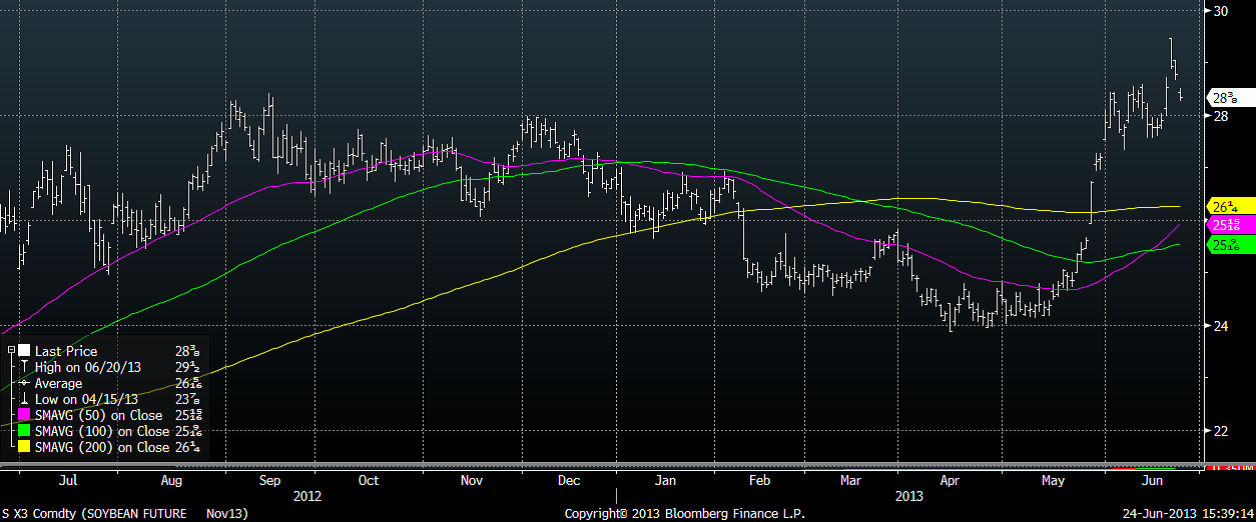
Det är som vi ser ett pris som är högre än förra året, som stimulerade till en produktion av 82 mt. USDA förväntar sig i den senaste WASDE-rapporten att produktionen i vinter (2013/14) stiger till 85 mt, men det kan faktiskt bli ännu mer, eftersom priset har stigit så kraftigt den senaste månaden.
Vi väljer alltså att ligga kvar med ”sälj” rekommendation på sojabönor.
Raps
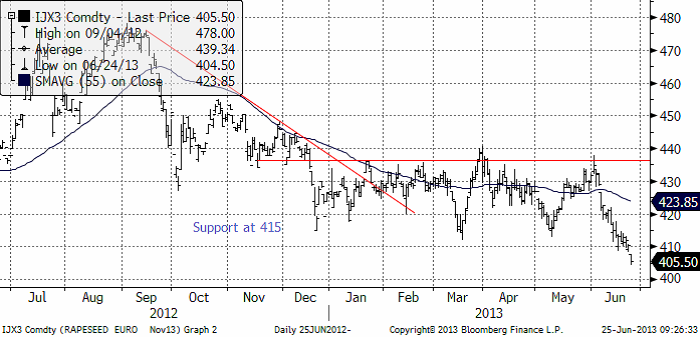
Rapspriset (November 2013) bröt genom stödet som hållit i ett halvår. När ett så ihärdigt stöd bryts är det alltid viktigt. Om inget ”bullish” kommer ur fredagens rapport om areal och lager för sojabönor på fredag, bör vi kunna se rapspriset testa och kanske falla under 400 euro per ton.
COCERAL justerar i sin senaste rapport i juni upp väntad produktion av oljeväxter marginellt från estimatet man gjorde i mars om 28.85 mt till 28.89 mt. I denna siffra så har den förväntade produktionen av raps nu glidit under 20 mt-strecket och förväntas uppgå till 19.9 mt – ner från mars månads prognos på 20.1 mt men fortfarande högre än förra årets 19.5 mt.
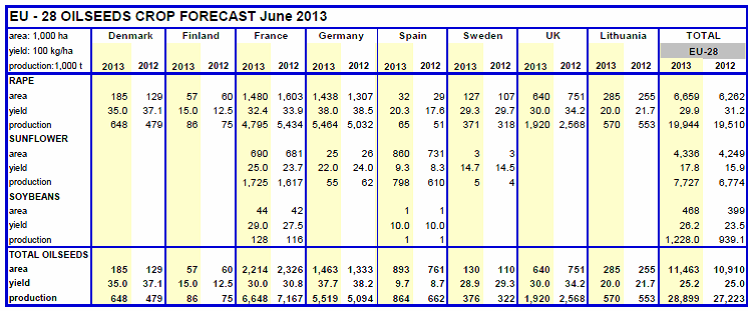
EU-Kommissionens MARS-enhet justerade i sin juni-rapport ner hektarskörden för raps och rybs 3.06 t/ha till 3.02 t/ha. Den bedöms för närvarande att bli lägre än förra året. Utsikterna för EU:s tre största producentländer Tyskland, Frankrike och Polen har försämrats. Om prognosen besannas blir det här året i så fall det fjärde året i rad för Frankrike med medioker avkastning. Även för mindre producenter som Bulgarien, Slovakien och Tjeckien görs betydande nedjusteringar (med mer än 5%).
Kaffe
Kaffepriset har fallit ytterligare och har nu uppnått den storlek på prisfall som en nedgångsfas i kaffe brukar uppnå (-60%).
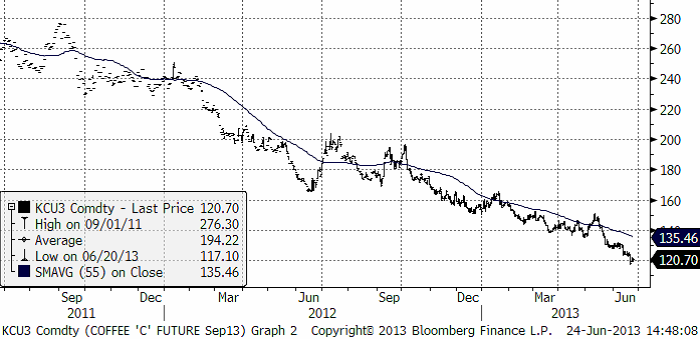
Skörden av robusta i nordöstra Brasilien väntas bli mindre och av sämre kvalitet än normalt. Bönorna är både mindre än normalt och mörkare än normalt. Detta beror på att området har varit ovanligt torrt. CEPEA rapporterar att lagren är i stort sett tömda från förra året. Ett positivt tecken, trots allt.
Socker
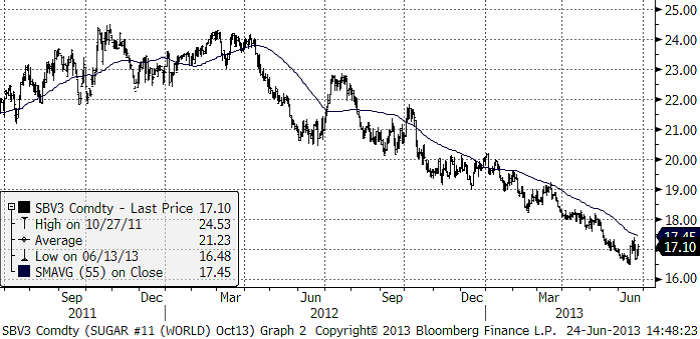
Priset på socker som tvärvände uppåt för en dryg vecka sedan, föll tillbaka, men inte hela vägen ner. Därefter har priset faktiskt vänt uppåt igen. Detta är en mikrorörelse i förhållande till det stora prisfallet som har pågått i över två år, men eftersom det sker på en så låg nivå att en botten kan vara nära, är det värt att hålla ett öga på utvecklingen framöver. Vi fortsätter tills vidare med neutral rekommendation. En uppgång till 18 cent skulle nog göra att vi bytte till köprekommendation.
[box]SEB Veckobrev Jordbruksprodukter är producerat av SEB Merchant Banking och publiceras i samarbete och med tillstånd på Råvarumarknaden.se[/box]
Disclaimer
The information in this document has been compiled by SEB Merchant Banking, a division within Skandinaviska Enskilda Banken AB (publ) (“SEB”).
Opinions contained in this report represent the bank’s present opinion only and are subject to change without notice. All information contained in this report has been compiled in good faith from sources believed to be reliable. However, no representation or warranty, expressed or implied, is made with respect to the completeness or accuracy of its contents and the information is not to be relied upon as authoritative. Anyone considering taking actions based upon the content of this document is urged to base his or her investment decisions upon such investigations as he or she deems necessary. This document is being provided as information only, and no specific actions are being solicited as a result of it; to the extent permitted by law, no liability whatsoever is accepted for any direct or consequential loss arising from use of this document or its contents.
About SEB
SEB is a public company incorporated in Stockholm, Sweden, with limited liability. It is a participant at major Nordic and other European Regulated Markets and Multilateral Trading Facilities (as well as some non-European equivalent markets) for trading in financial instruments, such as markets operated by NASDAQ OMX, NYSE Euronext, London Stock Exchange, Deutsche Börse, Swiss Exchanges, Turquoise and Chi-X. SEB is authorized and regulated by Finansinspektionen in Sweden; it is authorized and subject to limited regulation by the Financial Services Authority for the conduct of designated investment business in the UK, and is subject to the provisions of relevant regulators in all other jurisdictions where SEB conducts operations. SEB Merchant Banking. All rights reserved.
Dated Brent and Oman crude are showing the way higher. The Brent crude M1 contract (October) gained another 0.75% yesterday. It traded in a range of $95.97-95.06/b and closed at $97.0/b. This morning it gains another 1.4% to $98.4/b. The Dubai M1 contract which is settled in November is showing the way at $105/b while Dated Brent settled ydy at $106.8/b. Brent crude M1 is now well above both the 50dma, 100dma and 200dma and is heading towards the 61.8% Fibo level of $100.55/b with $110.44/b next in line technical level thereafter.
Tight oil product markets are helping to drive crude oil prices higher as well. The strong push upwards for the Dated Brent price with ydy price reaching $106.8/b. Behind that drive upwards it very tight oil product markets with balance of month diesel refining margins in ARA now close to $90/b and gasoil cracks have been reported to top $100/b for the first time ever. That means extreme profitability for refineries. In response refineries here, there and everywhere want to get their hands on physical crude as quickly as possible. Convert it to oil products and sell the products into the ultra-tight spot oil product markets. Especially the diesel segment (Jet, diesel, gasoil). The economic incentive is huge for refineries.
This drive by refineries to process more crude in response to high refining margins, usually kicks in at much lower levels. Thereby normally transferring tightness from the oil product market over to the crude oil market. That normal mechanism hasn’t really worked properly in this crisis so far since there hasn’t been all that much spare refining capacity left as Ukraine is constantly damaging Russian refineries while the semi-closure of the SoH has sharply reduced oil product exports.
Stronger Chinese crude oil imports but higher oil product exports as well. Chines crude imports rose 6.2% MoM in August to 9.21 mb/d. That was still 2.9 mb/d below the 2025 average of 12.1 mb/d. But China’s net oil product exports rose to 0.91 mb/d in August which is the highest level since February 2023. As a result, Chinese imports of crude and oil products was still 3.5 mb/d below the 2025 average versus 3.6 mb/d in July. That is a strengthening of net imports of only 0.1 mb/d. Not much change in total. But it shows that Chinese refineries, probably with the blessing of government, are importing more crude and re-export these as oil products. That helps to transfer oil product tightness to crude oil tightness. India is doing the same. In July it exported about 1.4 mb/d of oil products and the highest since September.
The Iran-Oman deal on the SoH will give China a forceful political option. The Iran-Oman agreement over how to operate the SoH is just days away from finalization says Iran. The IMO and the US is said to have been involved in the process. Once it is agreed and published, China will have the option to sail a Chinese flagged VLCC through the SoH according to the new, official regulation of the SoH, load oil at Kharg Island and take it back to China. That is a very forceful option for China.
Oil and the SoH will for sure be a hot topic when Trump and Xi Jinping meets in the US on 25 September. And China will have some forceful bargaining chips to play versus Donald Trump regarding the SoH and oil.
ARA balance of month refining margins at close to $90/b giving refineries strong incentives to run hard converting crude to products = stronger refinery crude oil demand

Dated Brent and Oman crude (settled outside of the Persian Gulf) are showing the way upwards

Chinese crude (crude) and net crude and oil product imports (red) versus the 2025 average. Net crude and oil product imports was 3.5 mb/d below the 2025 average in August and 3.6 mb/d below in July. Almost the same. Stronger crude imports but also higher oil product exports

Chinese oil product exports rose to 0.91 mb/d in August and highest since Feb 2023. (numbers in reverse)

Oil markets remain tight as the Strait of Hormuz (SoH) continues to be constrained. Things could become much tighter if it is fully closed. However, the outlook could change rapidly if flows normalise in early 2027. A large underlying surplus, rebuilding supply and the risk of more volume from OPEC+ could turn today’s tightness into a significantly weaker oil market in 2027-28.
Eventual reopening looks set to bring surplus
The SoH is constrained, not fully closed. Enough crude is escaping, while alternative pipelines, decreased Chinese imports and SPR releases have helped keep Brent at c. USD 90/bbl. Oil products are much tighter. A full reopening of the SoH would flip the market into surplus. We assume SoH flows normalise from early 2027. The market could then face a 4-5m bbl/d surplus before restocking. We forecast Brent at USD 75/bbl in 2027 and USD 70/bbl in 2028.
We expect OPEC+ to opt for more volume once SoH exports normalise
OPEC+ will likely opt for more volume. The UAE has already chosen volume, Iraq wants to expand and Venezuela looks set to exit. There is a clear risk of controlled OPEC+ supply growth, adding to downside risks for 2027-28.
Natural gas market: Winter risk ahead, yet LNG balance to loosen from 2026
Natural gas inventories in Europe are well below normal. The market had hoped for a revival in Persian Gulf LNG exports from Qatar. However, with no signs of any imminent reopening of the SoH, it might be too late for Middle East LNG cargoes to arrive in Europe before the end of winter 2026/27. TTF natural gas winter prices have rallied in response, but that is predominantly a winter risk with prices trading sharply lower after March 2027. Growing global LNG export capacity in the years to come should push prices lower.
Brent crude converging to technical levels. Brent crude has traded in a range of $90-95/b over the past five days. It pulled back 2.4% yesterday to a close of $92.17/b. This morning it is trading close to unchanged at $92.1/b. That is just above the 100dma of $91.9/b and the 50% Fibo level of $92.6/b. The next technical level would be $100/b. Vortexa stated in a report ydy that ”Record crude shortfall building – and market may miss it in summer lull”. If so, then $100/b is maybe where we are heading in the near term. Argus reported however on Friday that CPC Blend exports (Kazakhstan) has increased to 1.8 mb/d from only 0.85 mb/d in the second half of July. This has eased the crude tightness in Europe as it coincides with lower crude processing by European refineries due to maintenance and seasonal turnarounds.
China is standing in the way for US sanctions towards Iran. The US is threatening Iran with economic destruction via sanctions. But China is normally buying 90% of Iran’s crude and is strongly opposed to sanctions arguing that they don’t work. China cannot allow the US to dictate from whom it can buy crude oil or not. Xi Jinping is set to meet Trump in the US in a couple of weeks from now. There is no chance that the US will hit secondary sanctions on Chinese entities dealing in Iranian oil. How to make economic sanctions against Iran work when China is not a part of if is Trump’s big headache.
Natural gas – Winter panic sets in as there is no opening of Hormuz in sight. European natural gas is rallying amid low seasonal nat gas stocks and no reopening of the SoH in sight. European nat gas for December delivery is trading at EUR 67.5/MWh or about $136/boe. That is more than a 50% premium to Brent crude delivered in December. That measure traded in a range of 30% to 40% premium from mid-July to mid-August but has now jumped straight to 50%.
European natural gas inventories are currently at 63% versus a seasonal norm of 80.6%. That is 17.6% lower than 2010-2025 average.
The European nat gas market has stayed relatively calm for a long time in the hope that the Strait of Hormuz would open ”very soon” as Trump insisted all the time. Assuming that stocks ahead of winter could be rebuilt rapidly once the SoH was reopened. Now, however, there is no clarity on a reopening. No one expects it to happen anytime soon. As a result, the European nat gas market has run into a bit of a winter-panic over the past week.
Asian LNG buyers are part of the winter bidding-war. The European nat gas prices are however not set by European nat gas buyers alone. It is set in a cross-bidding for LNG cargoes between Asia and Europe. The fact that nat gas for December delivery has rallied to a 50% premium to Brent crude is probably indicating that Asian buyers are bidding strongly into this rally as well.
There are no strategic reserves for natural gas. The problem with natural gas is that there are no large inventories since gas is difficult and expensive to store. That is why the nat gas market is much more stressed over having lost 20% of seaborn supply normally coming from the SoH.
Dry rivers and low hydroelectric levels adds to Europe’s winter risk. Europe has also gotten into trouble due to the record hot and dry summer. Hydroelectric reservoirs are unusually low ahead of winter while low river levels are holding back nuclear and other thermal power plants from running.
A warm 2026/27 winter would help a lot. But the 2026/27 winter looks set to be warmer than normal according to seasonal forecasts for what they are worth.
European natural gas inventories are significantly below the 2010-2025 average

TTF nat gas for December delivery has jumped to a 53% premium to Brent crude.

Nat gas forward prices versus Brent crude forward prices. Nat gas is about winter risk as there are no strategic reserves (inventories) of natural gas other than commercial stocks.



Priset på diesel når sin högsta nivå någonsin i USA

Svenska gurkor växer flexibelt med tillgången på elektricitet

Dieselpriset i USA passerade idag upp över 200 USD per fat

Finska kärnkraftverket Loviisa förlänger livstiden till 2050 med hjälp av Google
Dated Brent and Oman crude are showing the way higher

Irland har inlett en debatt om att ta bort förbudet av kärnkraft

Saskatchewan bygger en av världens största urangruvor, kan stå för en femtedel av den globala produktionen

Pirater från Somalia kapar tankfartyg som fraktat oljeprodukter från Iran

Jeffrey Currie – Råvarorna skickar en varningssignal, guld gynnas från två håll
Stay long or buy-on-dips in the run-up to the US midterm elections on 3 Nov
-
 Nyheter2 veckor sedan
Irland har inlett en debatt om att ta bort förbudet av kärnkraft
-
 Nyheter3 veckor sedan
Saskatchewan bygger en av världens största urangruvor, kan stå för en femtedel av den globala produktionen
-
 Nyheter3 veckor sedan
Pirater från Somalia kapar tankfartyg som fraktat oljeprodukter från Iran
-
 Nyheter3 veckor sedan
Jeffrey Currie – Råvarorna skickar en varningssignal, guld gynnas från två håll
-
Analys4 veckor sedan
Stay long or buy-on-dips in the run-up to the US midterm elections on 3 Nov
-
Analys2 veckor sedan
Oil close to technical levels while EU nat gas is gripped by winter-panic
-

 Nyheter2 veckor sedan
Priset på råolja är fel signal att titta på, det är bensin och diesel som visar allvaret
-

 Nyheter1 vecka sedan
Nederländerna flyttar guld från USA och Kanada till London