

Analys
SEB Jordbruksprodukter, 2 augusti 2012

 Inledning
Den senaste veckan har priserna inte rört sig mycket. Även orderflödet har varit lugnare. Folk verkar ha stannat upp och funderat på vad som kommer att hända härnäst. På fredag nästa vecka publicerar USDA augustis WASDE-rapport. Kanske kommer det att vara lugnt fram tills den rapporten ger mer vägledning.
Vi fortsätter att ha en vy om högre priser på vete, maltkorn, majs, och sojabönor. Priset på socker står och väger, vid ett vägskäl, kan man säga.
Odlingsväder
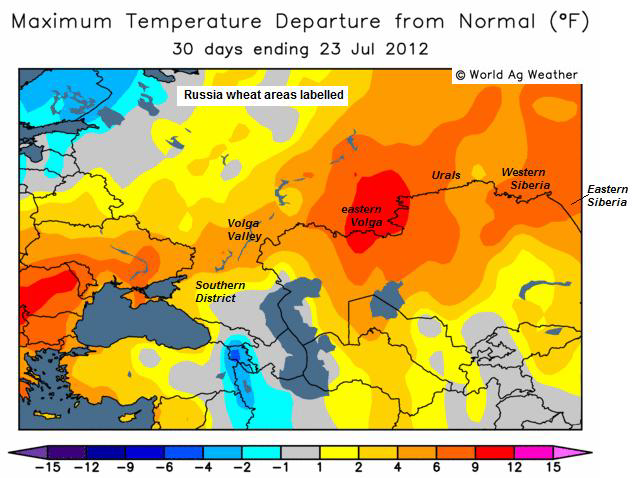
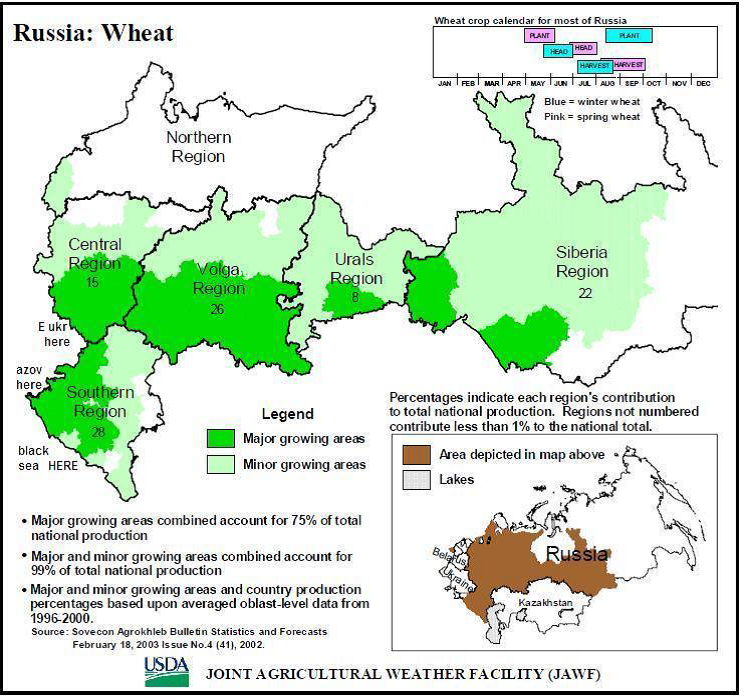
Bilder på det varma vädret i Ryssland och Svartahavsområdet börjar komma ut nu. Nedan ser vi en kartbild publicerad av Martell Crop Projections.
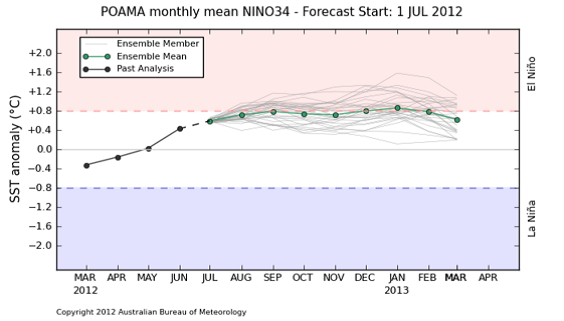
Southern Oscillation Index har tagit sig upp till neutrala förhållanden igen, men det anses vara temporärt, eftersom de flesta prognosmodeller pekar på att ENSO ska vara nära El Niño-förhållanden, dvs med SOI närmare eller lägre än -8.
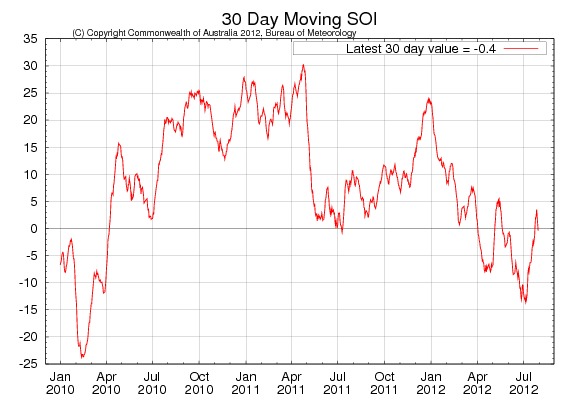
Australiensarnas prognos för ENSO pekar som vi ser nedan på att El Niño kan utveckla sig under hösten, men att det än så länge är osäkert. ENSO surfar precis på gränsen till El Niño.
Eurokrisen
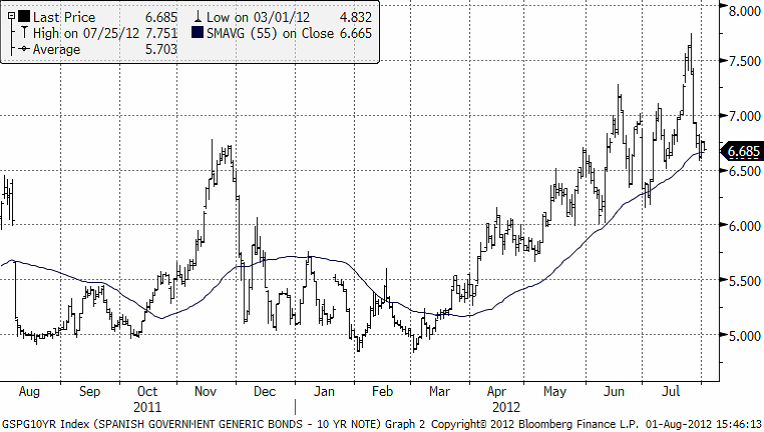
Vad som sker i EU är att det finns en social acceptans att banker tas över av staten därför att man inte vill uppleva obehaget av att bankerna går under var och en för sig, Detta gör att det är rimligt att anta att staternas i fråga egentliga skulder är deras egen statsskuld + bankernas skulder. När man studerar den typen av skuldberg i förhållande till de här ländernas skatteintäkter, får man en skrämmande bild. Än så länge försöker man skjuta upp det oundvikliga. ECB:s satsning på att få ner räntorna i Spanien är det senaste och främsta exemplet på detta. Vi ser nedan hur räntorna har på deras tioårs statsobligation har fallit från 7.75 till 6.68. Förmodligen får vi se räntemarknaden ta ett nytt kliv uppåt inom kort. Skuldberg av den här storleken blir man av med genom att inte betala (skuldnedskrivning / konkurs) eller genom att betala med nytryckta pengar (inflation).
Inköpschefsindex, PMI, för de stora ekonomierna har sjunkit stadigt det senaste året. Tysklands PMI för tillverkningsindustrin ligger nu under Frankrikes, på 43 mot 43.4. Eurozonen ligger på 44. Storbritannien har bromsat in fort de senaste tre månaderna och har sjunkit från 50.2 i april till 45.4 i juli. USA har halkat under 50. Endast Kina ligger över 50. Gårdagens kinesiska PMI kom in på 50.1, vilket är en tiondel lägre än i juni (50.2). PMI anses vara en ”ledande indikator” för ekonomins utveckling.
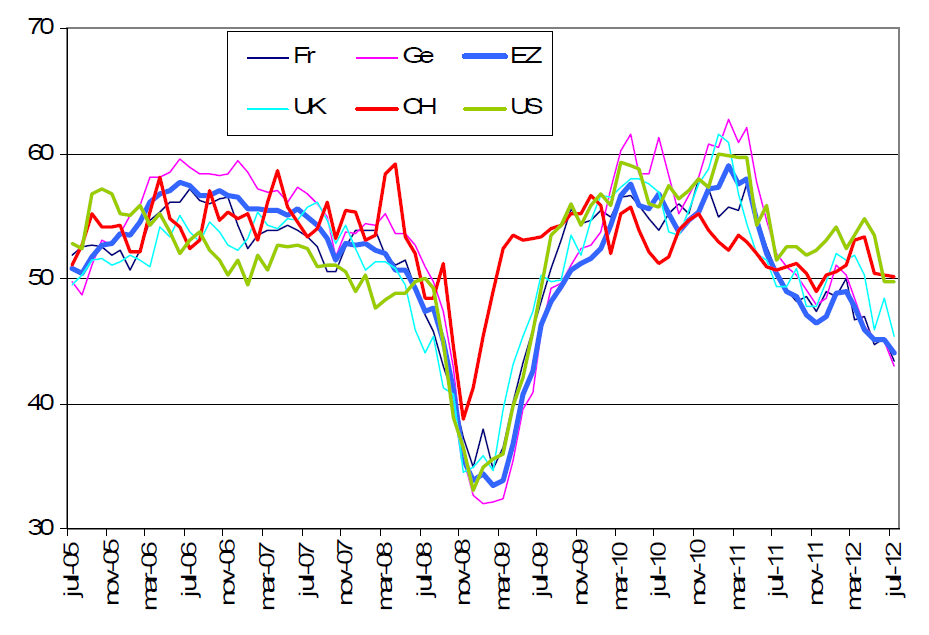
PMI, som är en ledande indikator, är för Eurozonen på samma nivå som månaden före Lehmankraschen 2008.
Vete
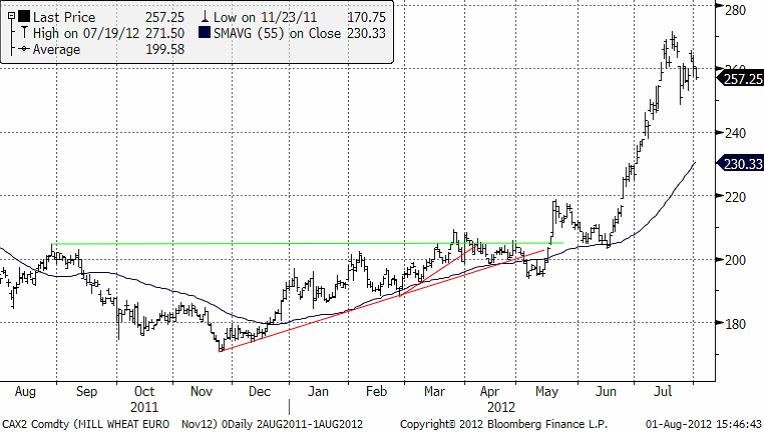
Matifvetet med novemberleverans nådde upp till 271.50 den 19 juli, men har sedan dess rekylerat ner till 257.25 euro i skrivande stund. Det är en nedgång med undefär 2.5 euro sedan förra veckobrevet. Frågan är om det här är en konsolidering inför vidare uppgång eller en toppnivå? Vi tror att marknaden kan komma att röra sig sidledes ännu en liten tid, men att priset sedan kommer att gå ännu högre.
IGC (International Grains Council) kom med sin rapport i förra veckan. Den globala produktionen av vete 2012/13 beräknas uppgå till 665 mt, vilket är oförändrat från tidigare prognos men lägre än förra årets 696 mt. Prognosen för veteproduktionen i Ryssland och Kazakstan justeras ned med 4 mt till 45 mt respektive 3 mt till 12 mt, medan utsikterna för produktionen i Kina och Indien justeras upp. Globala vete lager i slutet på säsongen 2012/13 justeras upp med 1 mt till 183 mt, vilket dock kvarstår som ett fyra-årslägsta. Nedan ser vi Chicagovetet med leverans i december. Dollarn stärks hela tiden mot euron, som faller stadigt i takt med att euroland blir mindre värt. Därför tyngs prisutvecklingen i cent mer än på Matif. På den punkten, betänk också att eurons fall gör att jordbruksmarken faller i pris i dessa länder; kostnaden rent allmänt utom för drivmedel och gödsel, för att producera spannmål sjunker.
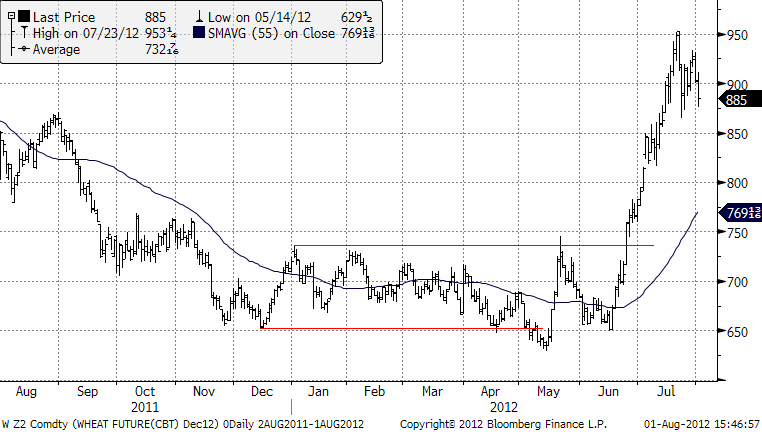
Nedan ser vi hur terminspriserna på Matif och Chicago förändrats den senaste veckan. Det är på terminer med kort löptid vi sett att priset gått ner. De längre terminspriserna är i praktiken oförändrade. Det är naturligt eftersom det är den här skörden just nu, som är föremål för osäkerhet om hur stor den blir.
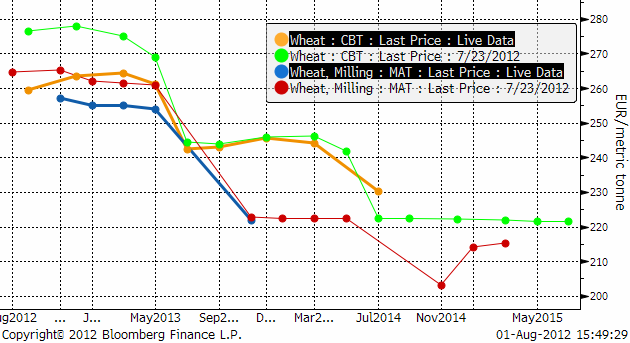
Vi ser i terminskurvorna ovan att Chicago fortfarande ligger över Matif för alla löptider. Ska man prissäkra framåt i tiden ger Chicago alltså ett högre pris än Matif.
Antalet artiklar på global basis som handlar om wheat+export+ban minskade den senaste veckan till 70 artiklar. Förra veckan var det 102 artiklar.
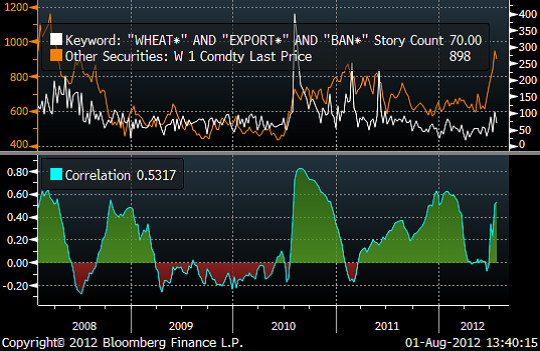
Vi ser att när det blir populärt att prata om wheat+export+ban i nyheterna, stiger vetepriset mot riktigt höga höjder. En panel av indiska (delstats) ministrar träffades i tisdags för att diskutera torkan i landet. De värst drabbade områdena är Punjab, Haryana, Karnataka och delar av Maharashtra och Gujarat. Andra delar av landet har fått för mycket nederbörd och istället drabbats av översvämningar. Punjab och Haryana är stora producenter av ris, medan de västra delstaterna Maharashtra och Gujarat är betydande producenter av oljeväxter och bomull.
 Centralbanken har också precis sänkt landets tillväxtprognos pga torkan. De åtgärder som ministrarna beslutade sig för var att öka stödet för dieselkonsumtion för jordbrukare, ökade stödet för utsäde. Man tog också bort importskatten på proteinmjöl. Man hade nämnt att man skulle diskutera att införa begränsningar i terminshandeln innan mötet, men detta gjorde man alltså inte. Skörden av linser, etc väntas bli avsevärt lägre i år än förra året, men landet har betydande lager sedan rekordskörden år 2007.
I Ryssland har den södra Krasnodar-regionen, en av få som nu är klara, skördat ca 5 mt spannmål, ungefär en tredjedel av förra årets skörd. På vissa ställen i västra Sibirien och Ural har temperaturen inte gått under 30 grader på över en månad, vilket också har lett till skogsbränder. Även om den ryska torkan är långt ifrån lika allvarlig som den i USA, har den extrema värmen fått landets jordbruksministerium att förra månaden sänka sin prognos för produktionen av spannmål till 80 mt, en minskning med 15 procent från förra året. I måndags sänkte Federal Metereorological and Environmental Monitoring Service sin prognos till 77 mt från 80 mt, något som förväntas följas av jordbruksministeriet. Ryssland behöver ca 72 mt spannmål för inhemska behov, och exporterar i allmänhet det som blir över. Oron över att Ryssland ska inför exportförbud eller exportrestriktioner kvarstår, men skulle kunna vara något som blir svårare för landet att införa i och med Rysslands inträde i WTO där reglerna för den globala handeln begränsar sådana genomföranden.
En nybildad kommission för tryggad livsmedelsförsöjning, som leds av Rysslands vice premiärminister Arkady Dvorkovich, kommer att träffas den 8 augusti för att diskutera spannmålssituationen i Ryssland.
Som ett resultat av det mycket torra vädret i vissa delar av Kazakstan förväntas landets spannmålsproduktion 2012 att sjunka kraftigt till drygt hälften av fjolårets rekordnivå. Men trots kraftigt minskad produktion, kommer sannolikt välfyllda lager att tillåta fortsatta höga exportvolymer under 2012/13. Per den 1 juli 2012 uppgick spannmåls-lagren till 9.8 mt, varav 9.4 mt vete.
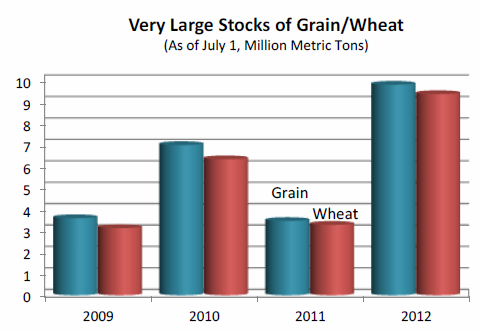
Produktionen av vete förväntas sjunka till 12 mt, jämfört med rekordet på nästan 23 mt under 2011. Medan spannmålsarealen kvarstår stadigt på 16.3 miljoner hektar, ser man däremot betydande förändringar mellan grödor. Arealen för vete har sjunkit med 2%, medan den totala arealen för korn har ökat kraftigt med 140 000 hektar till 1.8 miljoner hektar med den största ökningen i de nordliga regionerna.
Torka i vissa norra delar av Buenos Aires, den provins där mer än hälften av all vete produceras, och i södra Cordoba provinsen i Argentina har börjat påverka 2012/13 års gröda, där lantbrukarna ännu inte är klara med sådden. Landet är världens 6:e största vete exportör och den största leverantören till grannlandet Brasilien. Regeringen uppskattar att landets lantbrukare kommer att så 3.8 miljoner hektar med grödan denna säsong, en minskning från 4.6 miljoner hektar förra säsongen. I förra veckan hade lantbrukarna sått 88% av den estimerade arealen, upp 9% från veckan innan. BAGE estimerar landets vete areal till 3,6 miljoner hektar och USDA beräknar Argentinas veteproduktion till 12 mt under 2012/13, en minskning från 14.5 mt förra säsongen.
Maltkorn
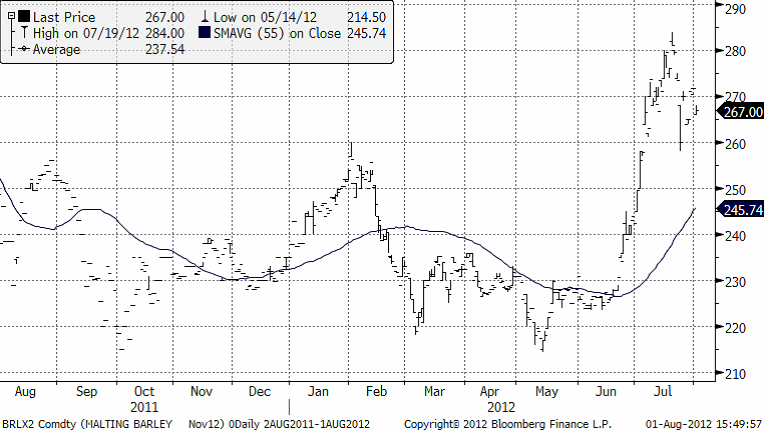
Novemberkontraktet på maltkorn ligger kvar över stödet på 260 euro. Så länge priset håller sig över den nivån tror vi att man bör avvakta med att sälja för att se om priset kan gå högre.
Potatis
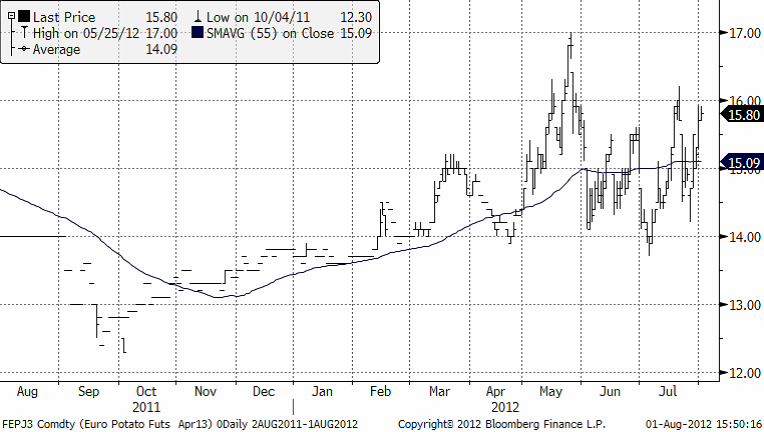
Potatispriset för leverans nästa år, har fortsatt att röta sig i det prisintervall vi skrivit om tidigare, mellan 14 och 16 euro per deciton. Om priset går utanför intervallet är det en signal om att priset kan dra iväg, men så länge priset håller sig inom intervallet är 16 = högt pris och 14 = billigt pris.
Majs
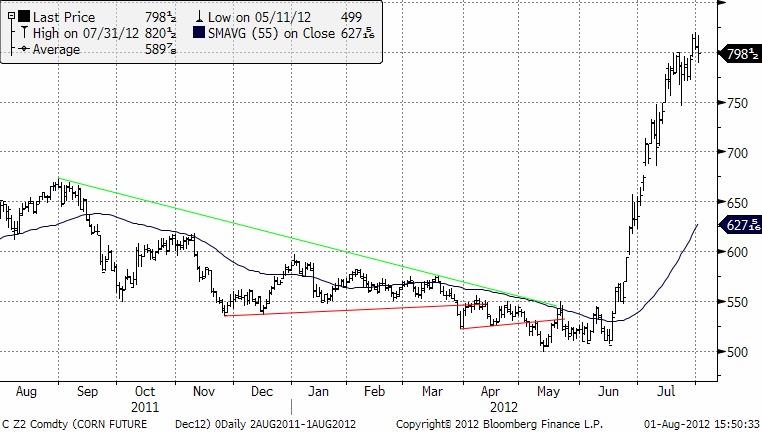
Priset på decembermajs ligger nu kring 800 cent. Jämna siffror brukar dra till sig mycket handel, eftersom det är psykologiskt lättare för folk att lägga en order på ”800 cent”, än t ex ”792.25”. 800 cent är alltså ett motstånd. Det har gått mycket fort att handla upp priset och någon slags rekyl eller konsolidering ”borde” kunna äga rum.
Nedan ser vi den av USDA enligt WASDE-rapporterna väntade avkastningen i bushels per acre i USA.
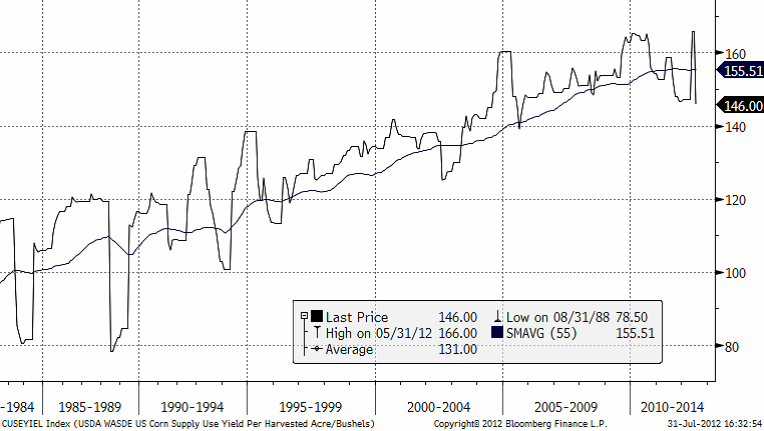
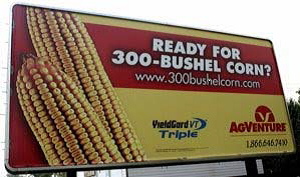
Som vi ser är trenden stadigt uppåtriktad och Monsanto, t ex förutspår att det kommer att vara normalt med 300 bushels per acre år 2030. Längs vägarna i ”corn belt” kan man se skyltar som den reklamskylt vi ser nedanför:
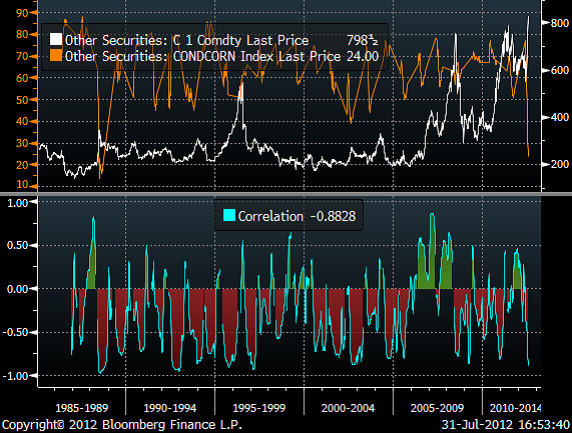
Crop conditions rapporterades i måndags kväll som 24% av majsskörden i good eller excellent condition. Detta fick priserna naturligtvis att stiga ännu mer. Studerar vi förhållandet mellan crop condition och majspris ser vi att korrelationen över tiden mellan förändringar i crop condition och majspris är kraftigt negativ, som den borde vara. Vi ser detta nedan, med de faktiska noteringarna i den övre delen och korrelationen dem emellan i den nedre.
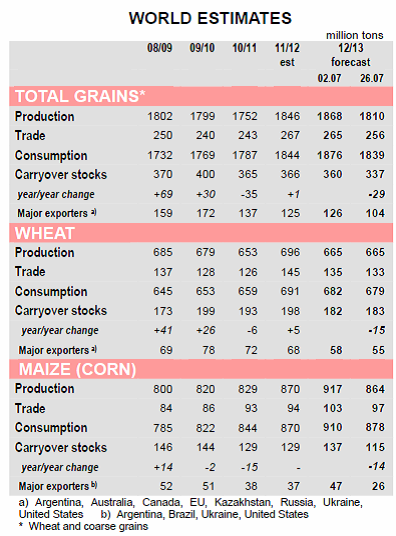
IGC (International Grains Council) kom med sin rapport i förra veckan och sänkte sin prognos kraftigt för den globala majsproduktionen 2012/13, med hänvisning till den värsta amerikanska torkan sedan 1956, och estimerar samtidigt att majslagren kommer att sjunka till ett sex-års-lägsta i slutet av säsongen. Den globala majsproduktionen beräknas nu uppgå till 864 mt, en nedjustering med 53 mt från tidigare prognos, vilket också är lägre än föregående säsongs 870 mt. Majsproduktionen i USA justeras ned med 50 mt till 300 mt, vilket är lägre än USDA’s senaste estimat på 329.5 mt.
Sojabönor
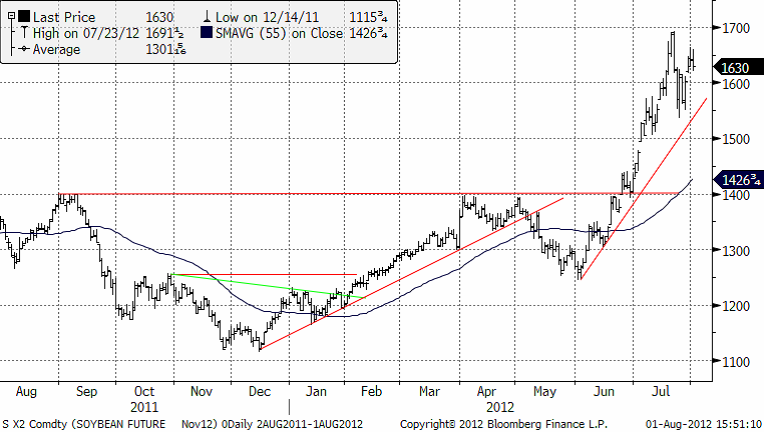
IGC (International Grains Council) kom med sin rapport i förra veckan (se tabellen ovan). Prognosen för den globala produktionen av sojabönor förväntas återhämta sig kraftigt under 2012/13, med en uppgång på 9% på årsbasis till 259 mt, även om prognosen hänger på en stark återhämtning av produktionen i Sydamerika där sådden börjar i fjärde kvartalet 2012. Däremot så justeras produktionen i USA ned med 8.3 mt till 79 mt. Nedan ser vi kursgrafen för november-bönorna. Vi ser att pristrenden är obruten uppåtriktad.
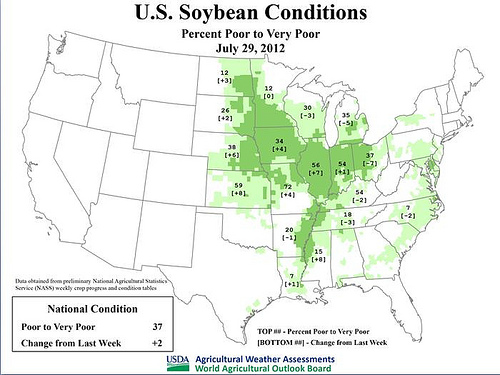
Nedan ser vi sojabönsodlarnas situation i USA. Det är ovanligt stora arealer som är i poor eller very poor condition. Andelen har ökat med 2%-enheter sedan förra veckan.
Celeres rapport visar att 41% av den brasilianska sojabönsskörden för 2012/13 har sålts, jämfört med 39% förra veckan och jämfört med 10% för ett år sedan. 97% av skörden 2011/12 har sålts, oförändrat från förra veckan och jämfört med 79% för ett år sedan.
Raps
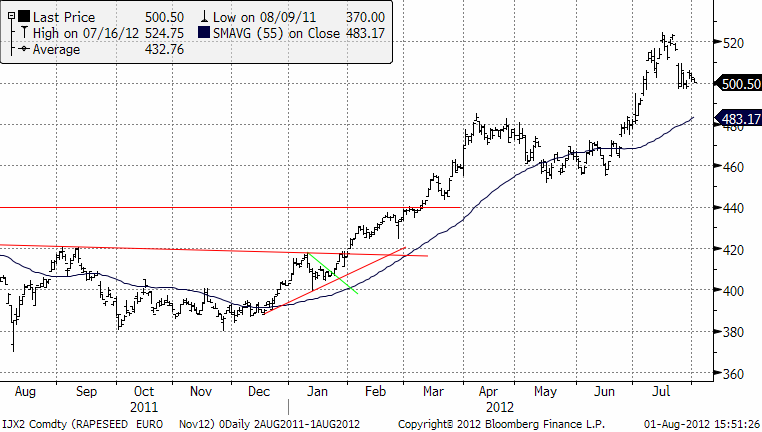
Priset på novemberterminen befinner sig alltjämt i en obruten uppåtgående trend. 500 euro fungerar som ett starkt stöd. Skulle den nivån brytas finns nästa stöd på 480 euro.
Oil World höjer sin prognos för EU’s rapsproduktion, för andra gången på två veckor, till åtminstone 19.0 mt från tidigare 18.2 mt. Det blöta vårvädret har gynnat grödorna hos de ledande rapsproducenterna i Europa och den förväntade ökade avkastningen har justerats upp framförallt i Tyskland där produktionen beräknas uppgå till ca 4.9-5.0 mt och skörden där är nu avklarad till 20-25%. Produktionen i Frankrike beräknas uppgå till 5.4-5.5 mt, jämfört med förra årets 5.37 mt, utifrån en avkastning på 3.4-3.5 ton per hektar.
I Storbritannien däremot förväntas en minskning med 100 000 ton från förra årets rekordskörd på 2.7 mt, trots ökad sådd, men det är fortfarande oklart hur de senaste tidens kraftiga regn kommer att påverka grödorna. Med tanke på att rapsen noteras i euro, som är svag, kan man tänka sig högre priser (i euro) framöver.
Gris
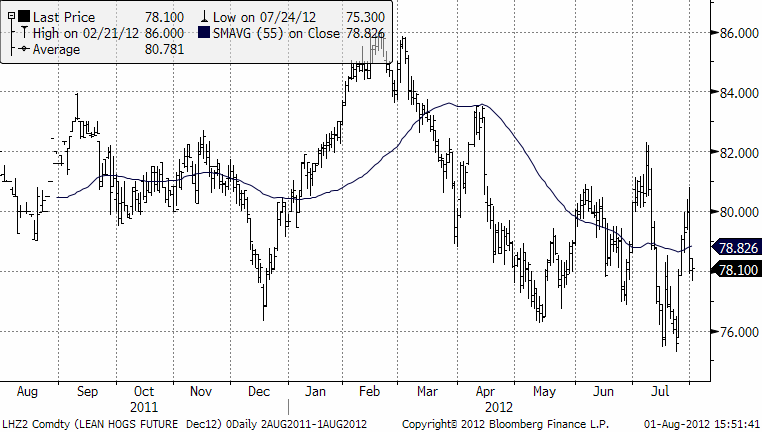
Decemberkontraktet har etablerat ett bekräftat stödområde på 76 – 77 cent. Med högre foderkostnader och den minskande lönsamheten för grisproducenterna bör det finnas utsikter för ett högre pris på lean hogs.
Mjölk
Mjölkpriset drivs naturligtvis upp pga av torkan i USA och Ryssland, som även drabbar höproduktionen. Priset på skimmed milk powder på tyska börsen har fått från 1950 i maj till 2275 euro per ton idag, som vi ser i diagrammet för priset på spotkontraktet på tyska Eurex nedan.
Samtidigt kunde vi läsa på ATL.nu igår att Arla sänkt avräkningspriset till mjölbönder med motivationen ”Det är mycket, mycket mjölk i marknaden just nu och det pressar priserna hos alla bolag”.
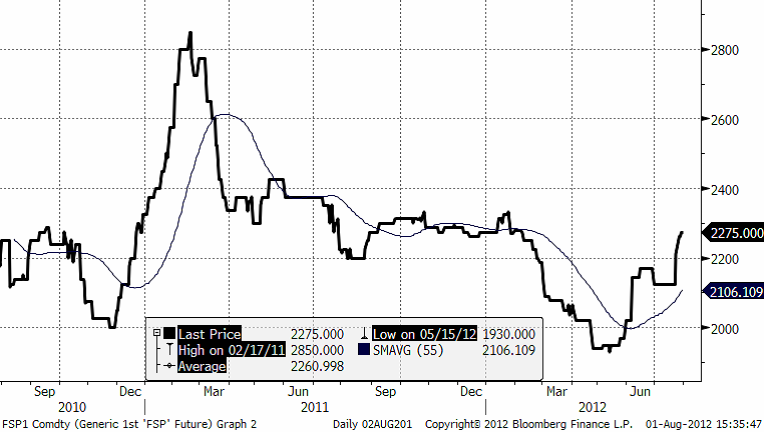
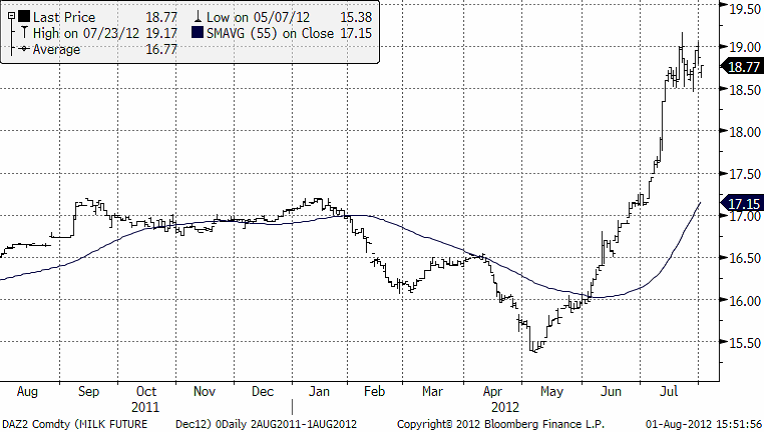
På den amerikanska börsen, där torkan som drabbat foderproduktionen är mycket allvarligare än i Europa, har priset rusat. Nedan ser vi decemberkontraktet.
Socker
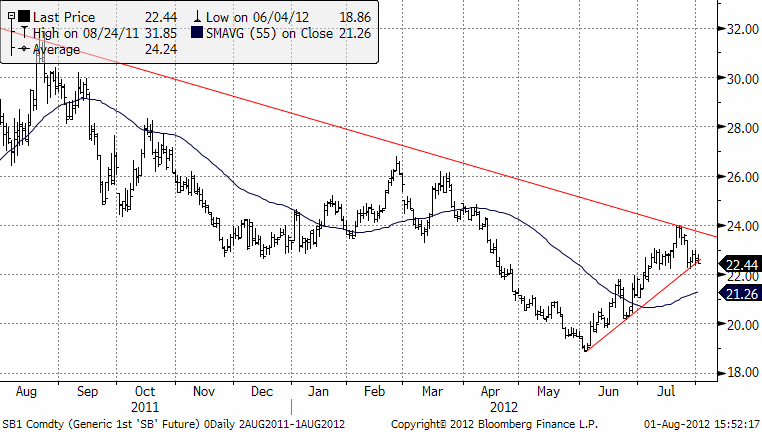
Priset på socker ligger fortfarande och balanserar: antingen bryts stödet och då för vi troligtvis en större prisnedgång mot 19 cent. – Eller så bryts motståndet som nu ligger på ca 23 cent, och då får vi antagligen en prisuppgång till 26 cent i första hand, kanske ännu mer.
[box]SEB Veckobrev Jordbruksprodukter är producerat av SEB Merchant Banking och publiceras i samarbete och med tillstånd på Råvarumarknaden.se[/box]
Disclaimer
The information in this document has been compiled by SEB Merchant Banking, a division within Skandinaviska Enskilda Banken AB (publ) (“SEB”).
Opinions contained in this report represent the bank’s present opinion only and are subject to change without notice. All information contained in this report has been compiled in good faith from sources believed to be reliable. However, no representation or warranty, expressed or implied, is made with respect to the completeness or accuracy of its contents and the information is not to be relied upon as authoritative. Anyone considering taking actions based upon the content of this document is urged to base his or her investment decisions upon such investigations as he or she deems necessary. This document is being provided as information only, and no specific actions are being solicited as a result of it; to the extent permitted by law, no liability whatsoever is accepted for any direct or consequential loss arising from use of this document or its contents.
About SEB
SEB is a public company incorporated in Stockholm, Sweden, with limited liability. It is a participant at major Nordic and other European Regulated Markets and Multilateral Trading Facilities (as well as some non-European equivalent markets) for trading in financial instruments, such as markets operated by NASDAQ OMX, NYSE Euronext, London Stock Exchange, Deutsche Börse, Swiss Exchanges, Turquoise and Chi-X. SEB is authorized and regulated by Finansinspektionen in Sweden; it is authorized and subject to limited regulation by the Financial Services Authority for the conduct of designated investment business in the UK, and is subject to the provisions of relevant regulators in all other jurisdictions where SEB conducts operations. SEB Merchant Banking. All rights reserved.


Brent higher last week and today as fresh attacks by Iran and the Houthis shattered a sense of temporary normality exports from the Persian Gulf. Brent crude traded in a range of $97.06 – 105.92/b and closed the week at $104.72/b. The Brent Dec contract gained $2.47/b on the week. Fresh attacks by Iran on ships in the Gulf and the SoH probably reduced exports of oil through the SoH last week. Exports from the Persian Gulf had reached close to normal levels in the second half of September and into early October. This has led to a large increase in oil on water globally which has helped to ease and reduce November and December prices over the past month. The sense of some kind of normality of exports from the SoH was shattered last week. Fresh attacks by the Houthis on Saudi Arabia added to this and helped to lift prices. It is well known that the US and its allies in the Gulf are running low on defensive rockets. Hard choices over what to defend will increasingly have to be made: Oil infrastructure, military installations, royal palaces, civilian airports or other. The US will also have to decide how many defensive rockets it can provide to its ME allies versus what it needs for its own defenses. Ukraine is at least not getting any of these defensive rockets however much needed for defense against a continuous barrage of Russian attacks on Ukraine. The front-month ICE Gasoil 10ppm (essentially ULSFO Diesel) is down 3.8% this morning (due to Trump’s diesel charade) to $1427/ton ($191/b) which is where it traded last Thursday.
Trump’s diesel charade. The site ”535” now puts the probability for control of the US Congress and Senate following the midterm elections at 99% and 61% respectively. Trump’s war in the Middle East with high or record high gasoline and diesel prices at the pump in the US is largely to blame. Trump’s diesel deal with Russia is clearly Trump trying to shift the blame from his own war in the ME to Ukraine instead. He could of course have placed the blame on Putin and Russia for its war against Ukraine, but no, it is Ukraine who gets the blame and not the least Zelenskyy. Physically it is of course correct that it is Ukraine who is destroying Russian refineries to the point where 45% of Russian refineries are out of operation. The result is that there is too little gasoline for domestic Russian consumption and no diesel, VGO and Jet fuel left over for exports. Russia normally (pre-war 2022) exports some 1.3-1.4 mb/d of diesel products of which a lot used to go to Europe.
Russia/Putin would happily export diesel products to the world, but it can’t because Ukraine is destroying its refineries. Russia implemented export restrictions of diesel already in July this year and the plan was to extend that to early 2027.
The only way that Putin/Russia can start sustained diesel exports, is if Trump is able to discipline and prevent Ukraine from attacking and destroying Russian refineries. Then Russian refineries can be repaired, ramp up, produce more diesel and potentially export what ever is of surplus to the world. Trump has threatened Ukraine that if it doesn’t stop its attacks on Russian refineries, then there will be no more indirect sales of weapons from the US via Europe to Ukraine and the intelligence which US currently is providing to Ukraine will stop.
It is clear that if Russia stops its attacks on Ukraine, then Ukraine is prepared for a energy infrastructure cease-fire.
Trump very well knows that he has himself to blame for the terrible stats for the upcoming midterm elections where Republicans looks set to lose both the Senate and the House. This is a charade for the US public to shift the blame over to something or someone else than himself. His easy choice falls on Ukraine and Zelenskyy for which he has shown little love, affection and support. Nothing of the one way bromance which Trump has shown versus Putin.
At most a three-week holdup in Ukrainian attacks on Russian refineries. Ukraine accepting to play scapegoat. Ukraine’s attacks on Russian refineries and oil infrastructure is a key element of Ukraine fighting back and defending itself against Russia. Ukraine has no choice but to continue its attacks as long as Russia keeps attacking Ukraine. But maybe there can be a three week holdup where Ukraine is forced by the US to step down its attacks on Russian refineries to please Trump until the US midterm elections are behind us. I.e. Ukraine accepting to be the scapegoat for Trump’s missteps in the Middle East for a three week period. Thereafter it will revert back to well thought out strategy of attacking Russian oil and refinery installations.
Trump under increasing pressure as there is increasing probability for Democratic victory in US midterm elections. Desperate times and desperate measures from Trump as a result. More to come

Large increase in oil on water heading for consumers around the world following a sharp increase in exports of oil from the Persian Gulf to close to normal from mid-Sep. Lower exports last week after new hostilities most likely.

Crude, products and natural gas prices in USD/boe. ICE gasoil slightly lower today, but still $195/b

Last week’s oil price action distorted by rolling of the November contract last week. The December Brent crude oil contract rose $4.8/b, or 5% last week. Much of that gain was due to the roll-yield as the November contract rolled off as the M1 contract to be replaced by the Dec-26 contract. The backwardation between the Nov and the Dec contract averaged $6.5/b over the last three days before 1 October and the rolling of contract. The ”gain” over the week was thus not much of a gain at all. If we just look at the M1 contract it instead fell 2% Friday to Friday though that disguises the change in the underlying contract over the week. The Brent M1 contract closed the week at $102.25/b. The announcement of 100 mb of oil from G7 SPR helped to ease prices at the end of last week. Though that effect seems to have faded today.
More barrels from Strategic Petroleum Reserves or really barrels which were supposed to be released previously? Nonetheless, Trump seems to be content and is backing down from diesel export ban. Trump threatened the world, but especially Europe with a US diesel export ban unless Europe agreed to release diesel from strategic reserves. G7 last week decided to release 100 million barrels of oil from strategic reserves. But here the obscurity starts. How much of that will be diesel? ”Substantial release of diesel within 20 days” was the statement. If it happens late in this 20 day period, it would bring us very close to the US midterm elections which of course is what Trump is worried about here. IEA members promised to release 425 mb of oil from strategic reserves of which 125 mb was to be oil products. But a significant portion of that was never really released. The question is thus whether these ”new” 100 mb release will really be new or if the lion’s share of the ”new” 100 mb is really just part of the old 425 not yet fully released. Well, it looks like the promise, irrespectively what it really is, has averted a US diesel export ban for now. And it did also help to ease prices a bit at the end of last week. An effect which looks like it has mostly faded this Monday.
$140/b is the price of crude oil in Europe today. Back to the complete distortion of oil and product prices in time and geography. The Dated Brent ”spot” price averaged $123.3/b last week. But that is really the average Day_10 to Day_20 of the ”daily Dated Brent” forward curve. But since this curve is in very steep backwardation, the real prices for physical oil cargoes at the very front-end of this daily curve sits well above the average of this daily curve. The physical premiums for Oseberg and for Fortis crude takes this steep backwardation into account. The full price average for Oseberg and Fortis last week were thus $142.5/b and $140.2/b. That is way, way higher than both the Dated Brent ”spot” price last week and the average of the Brent futures price, the M1 contract, which averaged $103.2/b last week and is trading at $102.4/b
Extreme prompt tightness may fade or get much worse. The extreme prompt tightness and backwardation we see in the market today is a display of today’s prompt situation and not necessarily a guide for the future. The much more relaxed Brent M1 contract (today December) at $102.4/b is maybe a reflection of an oil market either betting or expecting that today’s problems will be resolved somehow over the coming three months. Or, that the current flow of oil out of the SoH at 17.5 mb/d (close to normal) will be sustained or even increase over time. But we don’t know exactly why the flow of crude, products and LNG out of the SoH has been able to sustain at around 17.5 mb/d since mid-September (it seems). Is it because shippers are better at managing the risk or more willing to take the risk of transiting? Is it because the US military assistance is better? Or is it because Iran is paid by exporters and is allowing exports out through the SoH? It seems plausible that Iran expects the US to attack again after the US midterm elections. If so, then Iran may engage with fresh attacks before that date. Physical crude in Europe today is $140/b, or 2x the ”normal” price of $70/b. But if tightness escalates further, then price of crude in Europe could go to 3x, 4x or even 5x the normal level. Let’s hope that the US is able to keep the SoH ”open” at a rate of 17.5 mb/d and that another 100 mb of oil from G7 helps to shield against that upside risk.
The global oil-stock cushion is getting ”scarily thin”. Looking at the Brent M1 Dec-26 contract, one gets the impression that risks may be fairly contained. Looking at physical spot prices in Europe however of around $140/b, the sense of stress rises substantially. The latter better reflects Amin Nasser, CEO of Saudi Aramco, when he recently said that the cushion capacity of global oil stocks are getting ”scarily thin”.
Some key questions helping to keep the Brent M1 price above $100/b: Will Iran initiate fresh attacks before the US midterm elections? Will the US attack Iran after the elections? Will the US be able to keep the SoH close to open at 17.5 mb/d? Will the Houthis re-attack the Saudi east-west pipeline and ships trying to traverse the Bab-el Mandeb Strait as the Saudi-backed Yemen government tries to retake areas along the Red Sea recently taken by the Houthis? How far will this have to go before China finally decides to step in as a peacemaker in ME negotiations?
ARA Crude oil, diesel and nat gas prices in USD/boe

Physical crude oil premiums for Fortis and Oseberg in the NSea in USD/b premium over the Dated Brent index

Spot crude oil prices at very high levels. The Brent 1M (November) contract yesterday traded between $103.76 – 108.83/b before settling the day at $105.28/b. This morning it is trading up 1.4% to $106.8/b. That is not much of a price given that the ME crisis has been ongoing since 28 February. The Dated Brent spot price however settled yesterday at $123.78/b and averaged $120.6/b last week. Even stronger were the individual North Sea spot crude prices where Johan Sverdrup crude averaged $144/b from 21 to 24 September. And Johan Castberg was said to have traded at a premium of $32/b to the Dated Brent price last week which potentially would have placed it closer to $150/b.
A steady trend higher since $70/b in early July. Crude oil prices have been on a steady trend upwards since they bottomed out at around $70/b in early July following the discharge of some 200 million barrels of crude, products and liquids from the Persian Gulf during a two week MoU window. from 20 June to 7 July when hostilities again resumed.
The oil market today is split apart in time, space and molecules. Financial crude oil prices for November delivery are trading at $106/b (Brent) and $93.3/b (US WTI) and $107/b (Oman). But spot crude oil prices are much higher at $120-150/b as described above. But consumers do not consume crude oil, they consume diesel and gasoline and other products. And diesel prices are closer to $200/b in ARA due to destruction of Russian refineries and locked-in refineries in the Persian Gulf. Oil markets are very stressed with respect to products, but not so stressed with respect to crude oil. But refineries are eager to pay up for crude deliveries right here and now so they can convert that crude to products and make a killing profit. They are not willing to pay up for November crude deliveries in the same way as uncertainties on the Middle East situation is so high. Exorbitantly expensive VLCC freight rates is also driving prices apart. VLCC freight rates are today running at 500,000 to 1,000,000 dollar a day rather than the normal 20,000 a day. This typically adds $10-20/b for crude oil between the point of origin and the point of delivery some 30-50 days out in time when the crude is delivered. This creates a lot of confusion of what really is the price of crude oil these days. Prices are very different in time and space.
Bonds and equity markets are starting to feel the heat. The Middle East crisis is starting to feed risk and pain into financial markets where the US 10-year rate is rising along with crude and product prices with equity market indices starting to pull back in response.
The risk is rising that the ”Trump war” in the Middle East may lead to the ”Trump recession”. A legacy Trump would not likely want to have. Feed-through to financial markets, rising risks for US financial and economic recession, rising risk to Trump’s legacy, declining US stocks of Patriot and THAAD rockets could be forcing mechanisms towards a resolution of the Middle East crisis.
A picture of the future Middle East order is starting to emerge. There seems to be a lot of discussions between different parties going on and a picture of a new Middle East order is starting to emerge. A post Middle East pax Americana order. Where the different countries in the Middle East are taking much more responsibility for the security order in the region. The US provides intelligence and sell weapons to the region but is reducing its military presence. Iran is recognized as a regional power, but not the dominant one and is part of the security order in some ways. Trump can say that he reshaped the Middle East order. Exports of oil restored. The region now paying for its own defense. US soldiers pulled out to a minimum. China part of the diplomatic solution and taking some responsibility for keeping Iran in check.
Time to some kind of ME resolution? Forcing mechanisms: Declining stocks of defensive US rockets + rising crude and product prices + rising economic and financial pain and rising risk to Trump’s legacy. A window of resolution could be November to January maybe. Markets will likely increasingly price in a resolution as the picture of the future security order in the Middle East emerges further.
Crude and diesel prices in USD/b

European M1 refinery margins at record high.





The Trump diesel charade

Viscariagruvan får strategisk status av EU

Miljöpartiet i England slutar vara motståndare till kärnkraft
The price of crude oil in Europe today is $140/b

Kanada vill få fart på oljesanden igen

År 2035 kan datacenter i USA förbruka mer naturgas än Japan och Tyskland tillsammans

Varför det en gång så mäktiga OPEC förlorar inflytande
Kanada vill få fart på oljesanden igen
Oil prices are rising, but a picture of the future ME order may start to emerge
Viscariagruvan får strategisk status av EU
-
 Nyheter3 veckor sedan
År 2035 kan datacenter i USA förbruka mer naturgas än Japan och Tyskland tillsammans
-
 Nyheter4 veckor sedan
Varför det en gång så mäktiga OPEC förlorar inflytande
-
 Nyheter2 veckor sedan
Kanada vill få fart på oljesanden igen
-
Analys2 veckor sedan
Oil prices are rising, but a picture of the future ME order may start to emerge
-
 Nyheter5 dagar sedan
Viscariagruvan får strategisk status av EU
-
 Nyheter1 vecka sedan
Miljöpartiet i England slutar vara motståndare till kärnkraft
-
Analys1 vecka sedan
The price of crude oil in Europe today is $140/b
-
Analys1 dag sedan
The Trump diesel charade